The S&P 500 (^GSPC +0.51%) stock market index last traded in bear territory during 2022 and 2023, when a stubbornly high inflation rate forced the U.S. Federal Reserve to aggressively hike interest rates. The index could find itself in a similar position in the near future, because soaring oil prices are stoking inflation once again, prompting the Fed to execute a rate hike at its recent September meeting.
The S&P 500 currently has a Schiller Cyclically Adjusted Price-to-Earnings (CAPE) ratio of 41.2, its second highest valuation since the peak of the dot-com internet bubble in 2000. In my opinion, this increases the odds of a severe downturn if headwinds like higher interest rates negatively impact the economy and investor sentiment.
Last time the S&P 500 entered bear territory, Tesla (TSLA -1.54%) stock plummeted by 75% from its peak to trade as low as $108. Because of the electric vehicle (EV) giant’s shrinking earnings over the past couple of years, I predict it could experience an even sharper decline if the S&P enters another bear market. Read on.

Image source: Tesla.
Tesla stock is trading at an unsustainable valuation
Competition is fierce in the EV industry. Tesla used to be the undisputed global leader, but it has lost ground to Chinese brands like BYD, Geely, and Zeekr over the last few years, because they offer cars with comparable features at much lower starting prices. These manufacturers are not just winning market share in China, but also in important EV battlegrounds like Europe.
Tesla’s EV sales subsequently declined in both 2024 and 2025. Fortunately, they are recovering in 2026 with first-half deliveries climbing by 16% year over year to 838,149 vehicles. However, the entire industry is benefiting from a surge in oil prices that is pushing consumers into the EV camp, so Tesla has simply been in the right place at the right time. Plus, the company has slashed prices across the board to boost sales, sacrificing some of its profitability in the process.
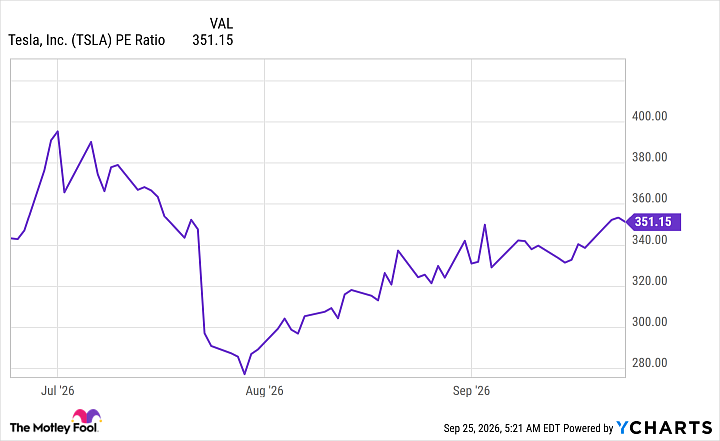
As a result, Tesla’s trailing 12-month earnings have plummeted from $4.30 per share to just $1.08 per share over the last two years, placing its stock at a sky-high price-to-earnings (P/E) ratio of 351. It’s 10 times as expensive as the Nasdaq-100 index, which has a P/E ratio of 34.1, so Tesla looks extremely overvalued compared with a basket of America’s largest tech companies.
TSLA PE Ratio data by YCharts
Investors usually reduce their exposure to stocks during bear markets to minimize risk, and their most expensive holdings are typically the first to go. When Tesla stock plummeted to $108 in late 2022, its P/E ratio compressed to around 30. The stock would have to crash by a whopping 91% from here if history were to repeat, and that assumes the company’s earnings don’t shrink any further (there is a real chance they will).
New products like the Cybercab and Optimus can’t come soon enough
Some investors are willing to pay a premium for Tesla stock today because they believe in the potential of future product platforms like the Cybercab autonomous robotaxi and Optimus humanoid robot.
The Cybercab is designed to provide autonomous rides to consumers on demand, but its underlying full self-driving (FSD) software is still awaiting regulatory approval in the majority of U.S. states. In fact, Tesla’s vice president of artificial intelligence software, Ashok Elluswamy, said its robotaxi program had only completed around 380,000 miles of driverless operation across two states as of June 30, so it’s way behind the competition. Alphabet‘s Waymo, for instance, is already completing over 500,000 paid autonomous trips across 15 major American cities per week.

Today’s Change
Current Price
Optimus is likely even further away from mass commercialization, because Tesla is still building out the supply chain and trying to solve some complex engineering challenges. Meaningful production won’t start until 2027 at the earliest, so this product platform won’t be rescuing the company’s shrinking bottom line any time soon.
With that said, chief executive Elon Musk believes humanoid robots could outnumber actual humans by 2040, making this one of the greatest financial opportunities in Tesla’s history. Last year, he told investors that Optimus has the potential to generate upwards of $10 trillion in revenue for the company over the long term.
But in the here and now, over 70% of Tesla’s revenue still comes from selling passenger EVs, a business that is likely to face even lower profit margins in the future as competition continues to ramp up. Therefore, this probably isn’t a good time to buy Tesla stock, particularly with the broader market on shaky foundations.