Freshpet currently trades at $57.15 per share and has shown little upside over the past six months, posting a middling return of 1%. The stock also fell short of the S&P 500’s 21.1% gain during that period.
Is now the time to buy Freshpet, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is Freshpet Not Exciting?
We’re cautious about Freshpet. Here are three reasons we avoid FRPT, plus one stock we’d rather own.
1. Fewer Distribution Channels Limit Its Ceiling
With $1.18 billion in revenue over the past 12 months, Freshpet is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers. On the bright side, it can grow faster because it has a longer list of untapped store chains to sell into.
2. Mediocre Free Cash Flow Margin Limits Reinvestment Potential
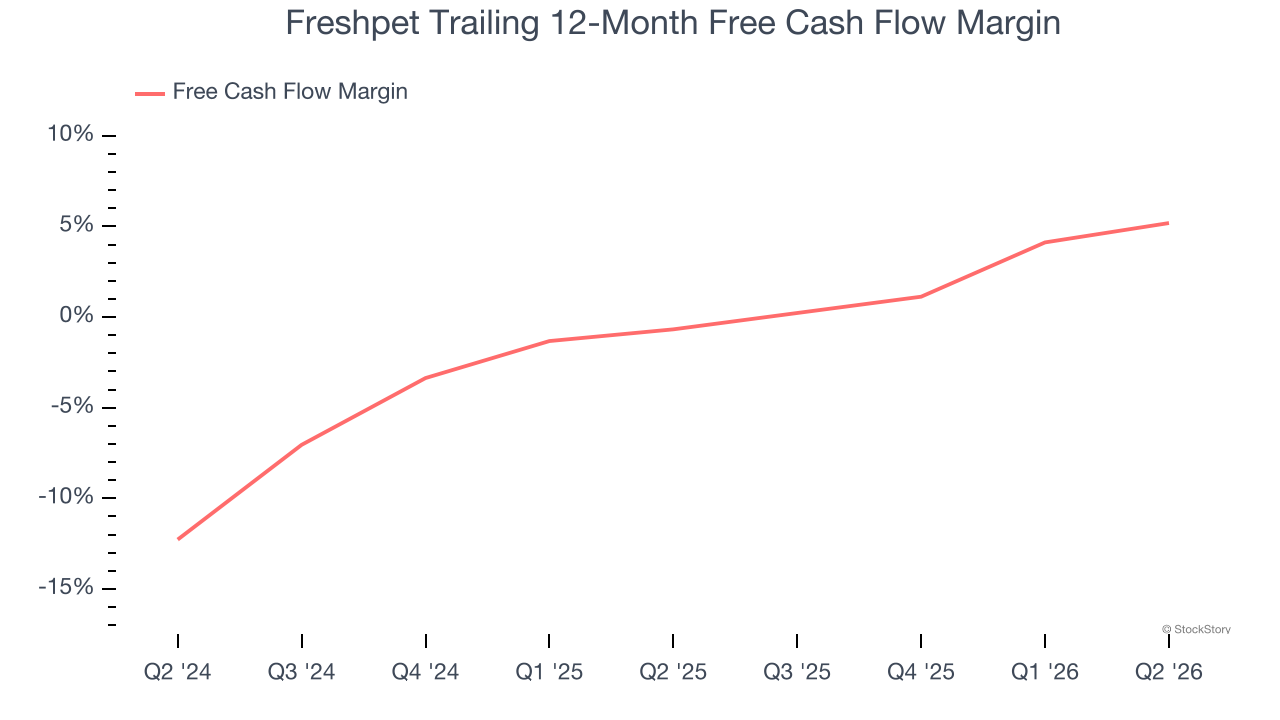
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Freshpet has shown weak cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 2.4%, below what we’d expect for a consumer staples business.
3. Previous Growth Initiatives Haven’t Paid Off Yet
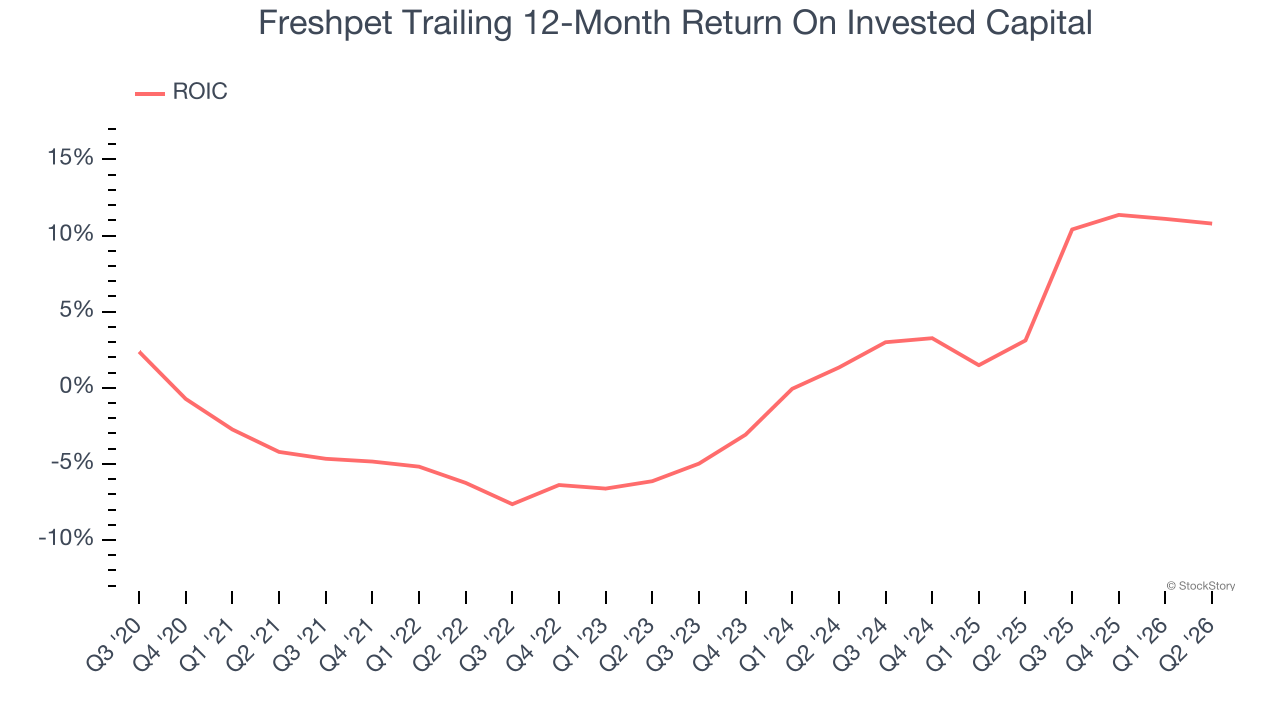
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? A company’s ROIC explains this by showing how much operating profit it makes compared to the money it has raised (debt and equity).
Freshpet historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 0.6%, lower than the typical cost of capital (how much it costs to raise money) for consumer staples companies.
Final Judgment
Freshpet isn’t a terrible business, but it doesn’t pass our quality test. With its shares lagging the market recently, the stock trades at 34.4× forward P/E (or $57.15 per share). This multiple tells us a lot of good news is priced in – we think there are better opportunities elsewhere. Let us point you toward the most entrenched endpoint security platform on the market.
Stocks We Like More Than Freshpet
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.