Marc Guberti, The Motley Fool
5 min read
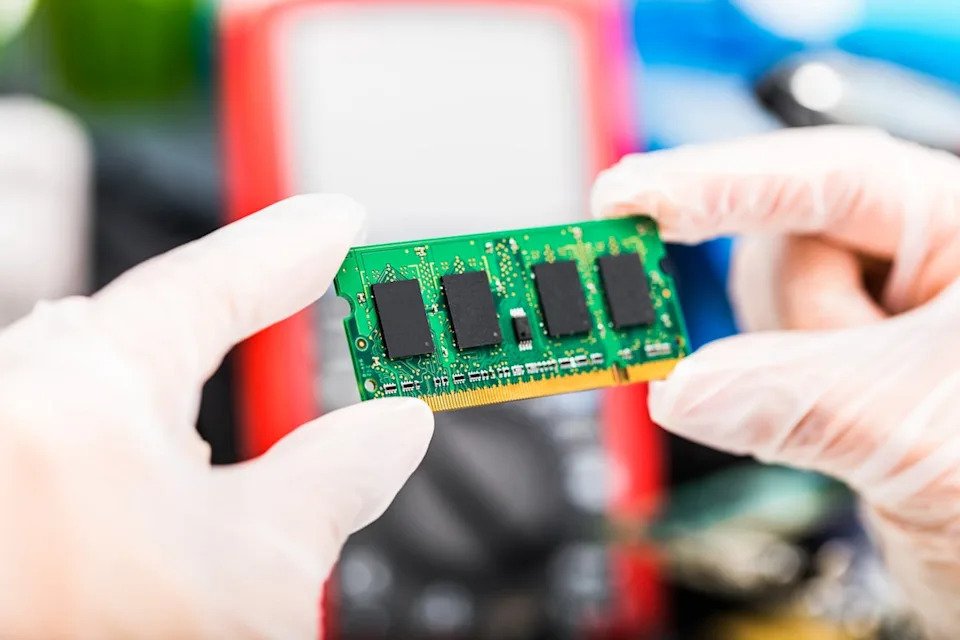
Computer memory and computer data storage products manufacturer Micron Technology (NASDAQ: MU) has been one of the biggest investment stories over the past year. Its memory chips continue to fly off the shelves, and its stock price is up about 350% over that period.
That’s a lot of growth over a relatively short period, and some investors wonder whether the gains will continue. I suspect they will, but I also think investors may actually do better with these three memory stocks instead.
Missed AI’s “Act 1”? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
1. SK Hynix
SK Hynix (NASDAQ: SKHY) is another premier memory chipmaker. Just like Micron, it has also secured multiyear customer agreements. Around 10 key customers reached long-term agreements related to the company’s memory chips in the second quarter. That foundation implies that the 257% year-over-year revenue boost SK Hynix saw in Q2 isn’t a one-off event.
The company generated revenue similar to Micron’s, depending on the currency conversion. The exact number was 79.3 trillion Korean won, and that marked a 51% sequential jump in sales. Micron delivered 31% sequential growth in its most recent quarter, implying that recent growth acceleration favors SK Hynix.
The exchange rate for USD and won at the time SK Hynix reported earnings on July 29 translated into $54.9 billion in Q2 revenue. Both SK Hynix and Micron operate in the same industry and offer similar products. SK Hynix has higher sequential growth, higher revenue, a lower market cap, and a more attractive P/E ratio. That makes SK Hynix more appealing at current levels.
2. Sandisk
Sandisk (NASDAQ: SNDK) is another memory stock that offers faster growth than Micron and a similar valuation when looking at P/E and forward P/E ratios. The NAND flash memory chip provider’s share price has surged more than 800% over the past year, and earnings due at the end of October may be the next catalyst for a renewed rally.
Sandisk’s fiscal 2026 fourth-quarter results are a teaser of what may be possible when the company reports earnings later this month. That quarter saw 51% sequential growth, higher than Micron’s. Furthermore, Sandisk anticipates fiscal 2027 first-quarter revenue will reach $10.8 billion at the high end of its guidance, which implies 20.4% sequential growth. Sandisk has a history of beating the high end of its guidance, and with Micron achieving the feat in its recent results, Sandisk is likely to follow at the end of the month.