Over the past six months, Blue Bird’s stock price fell to $55.78. Shareholders have lost 11.4% of their capital, which is disappointing considering the S&P 500 has climbed by 7.7%. This may have investors wondering how to approach the situation.
Following the drawdown, is this a buying opportunity for BLBD? Find out in our full research report, it’s free.
Why Is BLBD a Good Business?
With around a century of experience, Blue Bird (NASDAQ:BLBD) is a manufacturer of school buses and complementary parts.
1. Rising Sales Volumes Show Elevated Demand
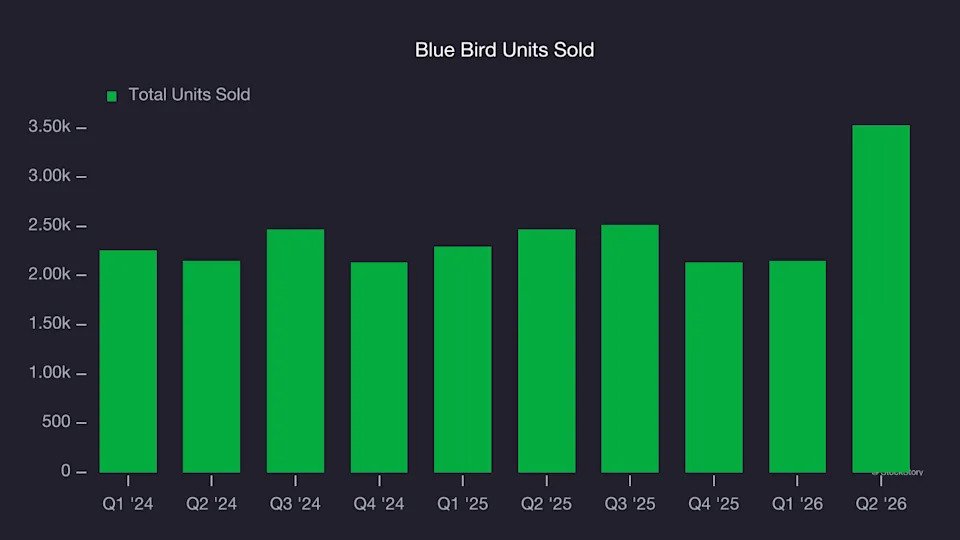
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful Heavy Transportation Equipment company because there’s a ceiling to what customers will pay.
Blue Bird’s units sold punched in at 3,525 in the latest quarter, and over the last two years, averaged 9.2% year-on-year growth. This performance was solid and shows there is something unique about its offerings.
2. Increasing Free Cash Flow Margin Juices Financials
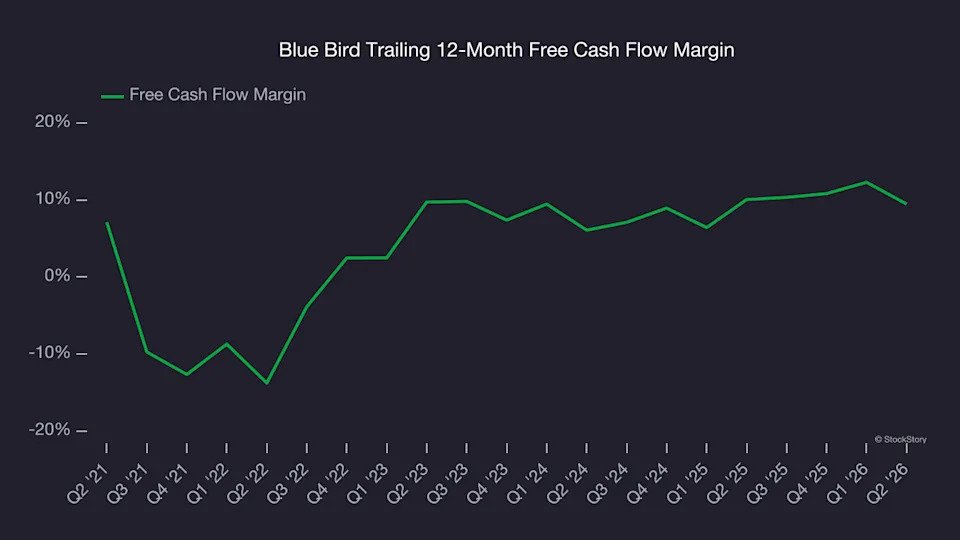
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
As you can see below, Blue Bird’s margin expanded by 23.3 percentage points over the last five years. This is encouraging, and we can see it became a less capital-intensive business because its free cash flow profitability rose more than its operating profitability. Blue Bird’s free cash flow margin for the trailing 12 months was 9.5%.
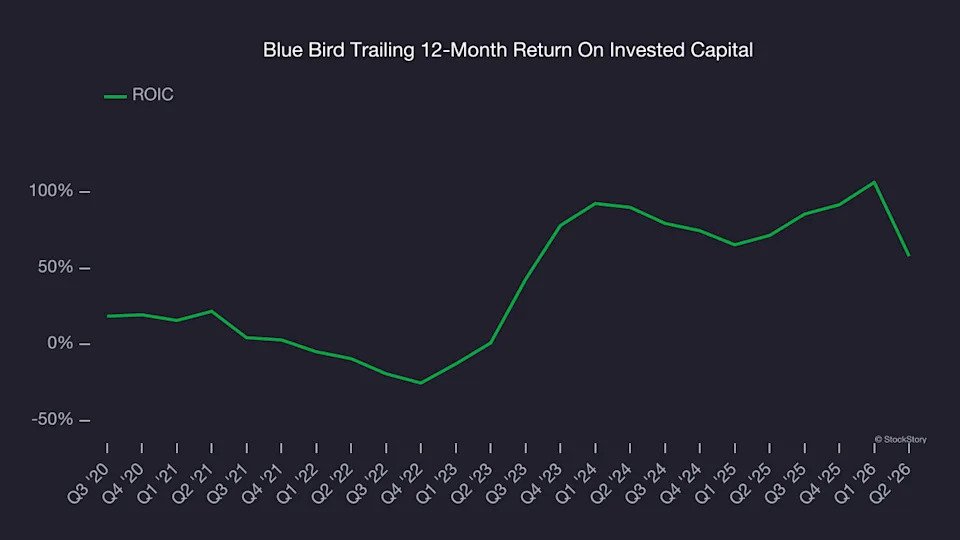
3. New Investments Bear Fruit as ROIC Jumps
A company’s ROIC, or return on invested capital, shows how much operating profit it makes compared to the money it has raised (debt and equity).
Over the last few years, Blue Bird’s ROIC has increased. This is a great sign when paired with its already strong returns, but we also recognize its lack of profitable growth during the COVID era was the primary reason for the change.
Final Judgment
These are just a few reasons why we think Blue Bird is an elite industrials company. With the recent decline, the stock trades at 13.1× forward P/E (or $55.78 per share). Is now the right time to buy? See for yourself in our in-depth research report, it’s free.
High-Quality Stocks for All Market Conditions
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.