Investors don’t know what to make of the AI boom.
Software stocks plunged earlier this year on concerns that AI-native applications from labs like Anthropic and OpenAI would disrupt entrenched software-as-a-service (SaaS) businesses with cheaper and more customizable programs.
Missed Nvidia in 2009? This Rare Signal Is Flashing Again. In 2009, a “Double Down” signal flashed for a little-known chipmaker called Nvidia. For the first time in years, that same “Total Conviction” signal is flashing for a company 1/100th the size of Nvidia. Continue »
The sector has recovered from its losses since then, though some quality stocks have gotten thrown out with the bathwater. One of them is Axon Enterprise (NASDAQ:AXON), the leading law enforcement technology company.
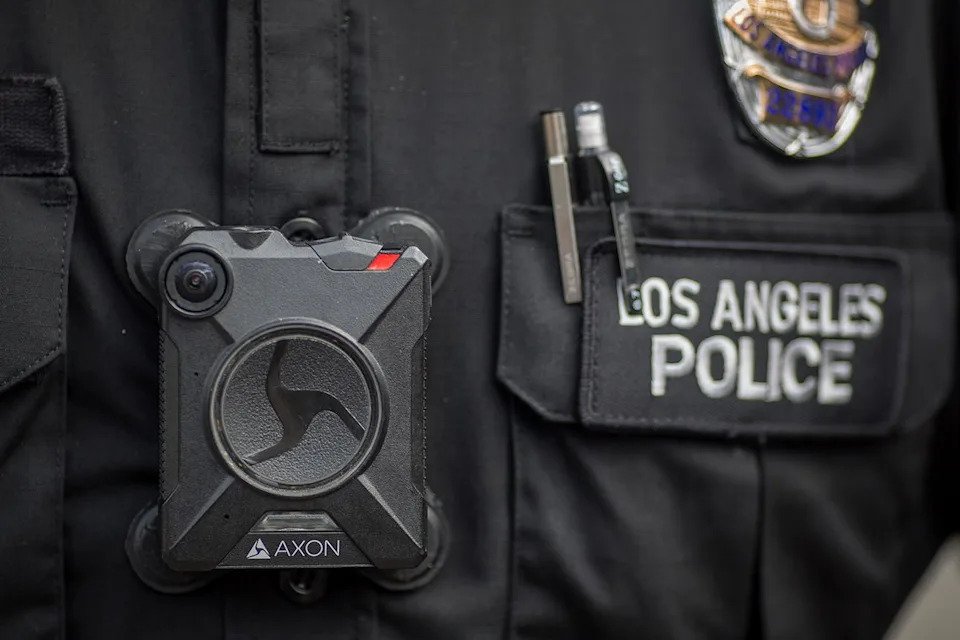
Image source: Getty Images.
All about Axon
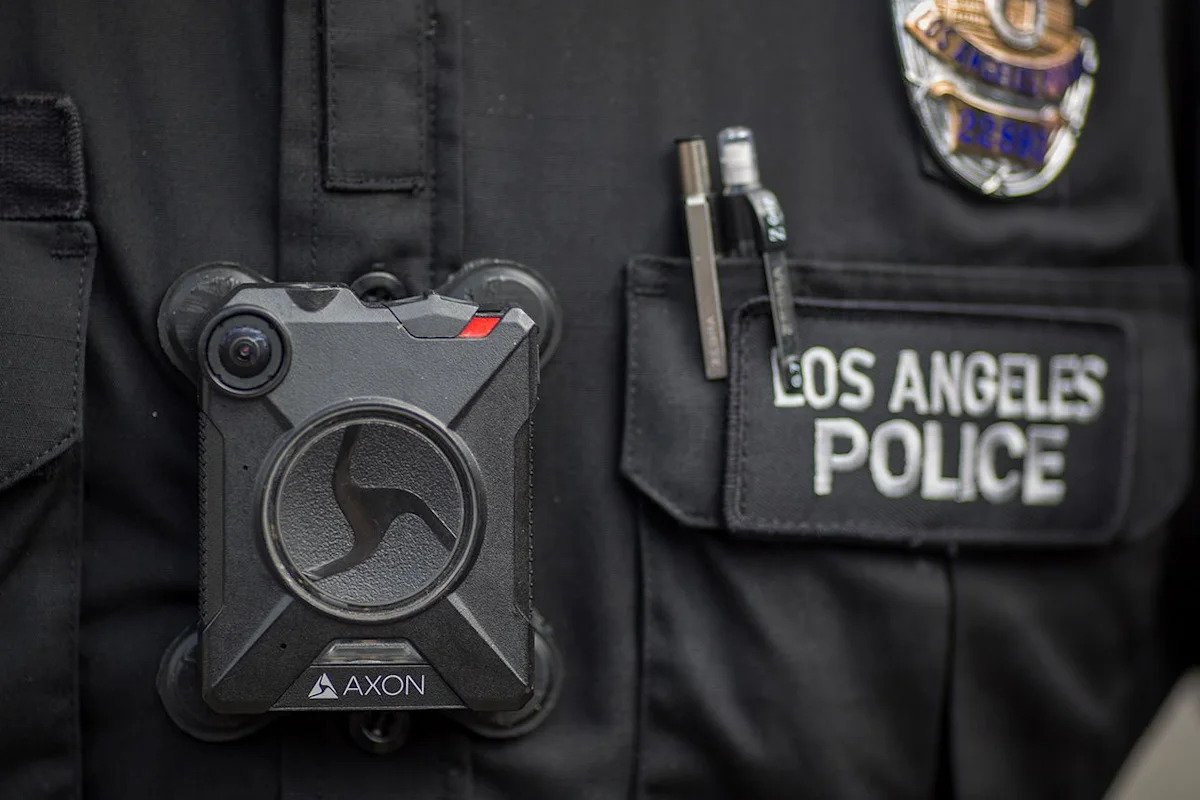
Axon’s shares tend to move with the broader software sector, but it’s not entirely accurate to call it a software company as Axon handles both hardware and software. It makes devices like the Taser electrical weapon and body and dashboard cameras. It also offers a suite of database software to help law enforcement agencies manage things like records, evidence, and investigations.
That combination has given Axon a wide economic moat in serving law enforcement agencies, and it’s reinforced that with a history of acquisitions and an innovative culture that has already rolled out a number of AI products. One of them is Draft One, a generative AI tool that writes first drafts of police reports based on camera footage.
Over its history, Axon has been a top performer in the stock market, delivering consistently strong revenue growth as it expands its market opportunity. Over the last decade, the stock is up more than 1,500%, and since the end of 2019, the company has delivered 25% revenue growth or better in every quarter except one.
Despite that strong track record, Axon stock is down 54% from its peak in 2025, and the stock has fallen 30% year-to-date, even as the broader software sector, as measured by the iShares Expanded Tech-Software Sector ETF, is flat for the year, following a strong rebound from the sell-off earlier this year.
What’s ailing Axon?
There isn’t one specific issue that explains Axon’s sell-off. Among the factors weighing on the stock are its valuation, concerns about margin compression, management’s decision to cut cash flow guidance as it invests in the business, and a recent convertible debt offering.
Axon has long been an expensive stock, and it deserves a premium given its growth rate and industry leadership. Currently, the stock trades at a price-to-sales ratio of 12, which is expensive but not excessively so. Around its peak last year, its P/S ratio was around 30, making it one of the most expensive software stocks on the market.