Sasha Jovanovic
4 min read
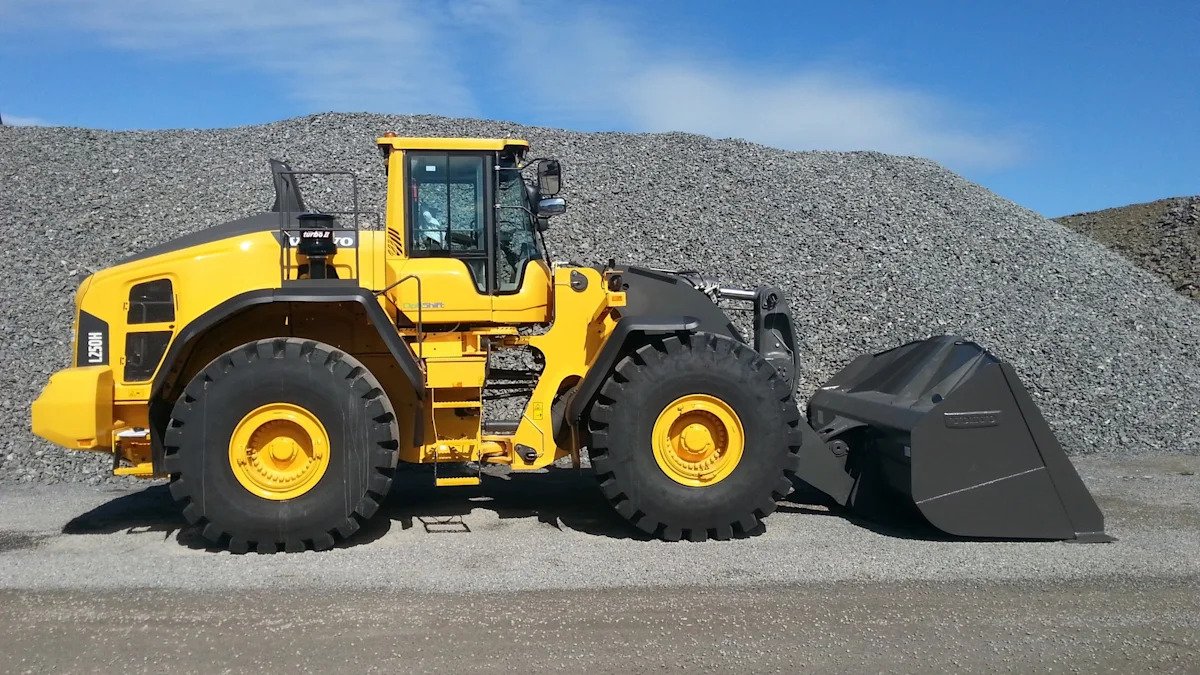
AB Volvo entered this Q3 print on the back foot, with the share price down about 5% over the past week and roughly 13% over three months, even as the stock closed at SEK307.7 on Friday. The headline today is simple: the truck and construction group reported another solid quarter, with Q3 2026 basic earnings per share of SEK5.30 and an adjusted operating margin of 12.3%, which kept return on capital at a robust 27.5% over twelve months.
Short term traders are focused on the recent price drift. Long term holders are looking at a business that still posts SEK119.5b of quarterly revenue and a trailing P/E near 16x, below both industry and peer averages, while carrying balance sheet strains where operating cash flow does not comfortably cover debt or the dividend. That split between market reaction and underlying profitability highlights the key question for Volvo’s next few years.
Love Volvo’s strong margins and returns but concerned that cash generation is not comfortably covering debt and dividends? Compare it with stocks screened for sturdier balance sheets and healthier cash coverage in our list of solid balance sheet and fundamentals stocks (205 results).
Q3 2026 Earnings Summary
-
Revenue (Q3 2026 vs Q3 2025): SEK119,525m vs SEK110,692m (up about 8%)
-
Net Income (Q3 2026 vs Q3 2025): SEK10,767m vs SEK7,540m (up about 43%)
-
Basic EPS (Q3 2026 vs Q3 2025): SEK5.30 vs SEK3.71 (up about 43%)
-
Adjusted Operating Margin (Q3 2026 vs Q3 2025): 12.3% vs prior period not disclosed (solid profitability with double digit margin)
Data center demand is now one‑third of Volvo Penta’s orderbook. Ask Charlie what Volvo Penta’s data center boom means for Volvo.

Evaluating Volvo’s Services And Autonomy Upside
The bullish script says Volvo can turn uptime contracts, data center power and autonomous transport into a higher quality earnings engine.
“The move by Volvo Autonomous Solutions toward removing safety drivers in the United States by early 2027 and scaling to more than 300 autonomous trucks with a Transport as a Service model targeting about US$3b of revenue within five years introduces a new fee based business that could add higher margin, recurring revenue on top of the traditional vehicle P&L.”
Q3 marks early proof points rather than full delivery. Commercial autonomous operations on the Dallas to Houston corridor are live, and Volvo Mining will bundle automation with equipment from 2027. Current group results are still driven mainly by trucks, construction equipment and a 21.1% margin at Volvo Penta.