Inwido (OM:INWI) is back in focus after reporting third quarter 2026 figures on 21 October, with higher sales and net income than in the same period last year. This is reshaping how investors assess the stock.
Investors have been rewarding this stronger third quarter, with Inwido’s share price at SEK189.0 and a 90-day share price return of 10.92% that lines up with a 16.74% year-to-date gain and a 1-year total shareholder return of 29.95%. This signals momentum that builds on a 3-year total shareholder return of 87.62%.
Spot opportunities that mirror Inwido’s operational momentum by scanning our curated list of 195 high quality undervalued stocks featuring companies with proven cash flows and balance sheet strength.
After that run and a stronger recent quarter, the real test for Inwido now is simple: Does the current valuation still skew the risk and reward in favour of new buyers, or has most of the upside already been recognised?
Preferred P/E of 19x: Is it justified?
On simple valuation metrics, Inwido looks cheap compared to its recent share price strength. The stock closed at SEK189, yet it trades on a P/E of 19x that screens as good value versus both peers and the broader European building sector.
The P/E ratio links what investors are paying today to the company’s earnings. For a manufacturer and seller of windows and doors like Inwido, where profit generation is a central focus, P/E is a straightforward way to see how the market is pricing each unit of profit.
At 19x earnings, the market is valuing Inwido below the European Building industry average P/E of 23.1x and well under the peer average of 29.9x. That suggests investors are paying a lower price for each krona of earnings than they are for comparable businesses, even though Inwido is trading at what has been described as 44.2% below an estimated fair value P/E of 22.7x that the market could lean toward over time.
Explore the SWS fair ratio for Inwido.
Result: Price-to-earnings of 19x (UNDERVALUED)
Still, the Inwido story can change quickly if demand for renovation and new builds softens, or if margins come under pressure from higher input costs.
Find out about the key risks to this Inwido narrative.
Another view on Inwido’s value
The SWS DCF model paints a very different picture for Inwido. On that approach, the share price of SEK189.0 sits well below an estimated future cash flow value of SEK338.61. That signals a wide valuation gap. Is this a genuine margin of safety or a sign the model is too optimistic?
Look into how the SWS DCF model arrives at its fair value.
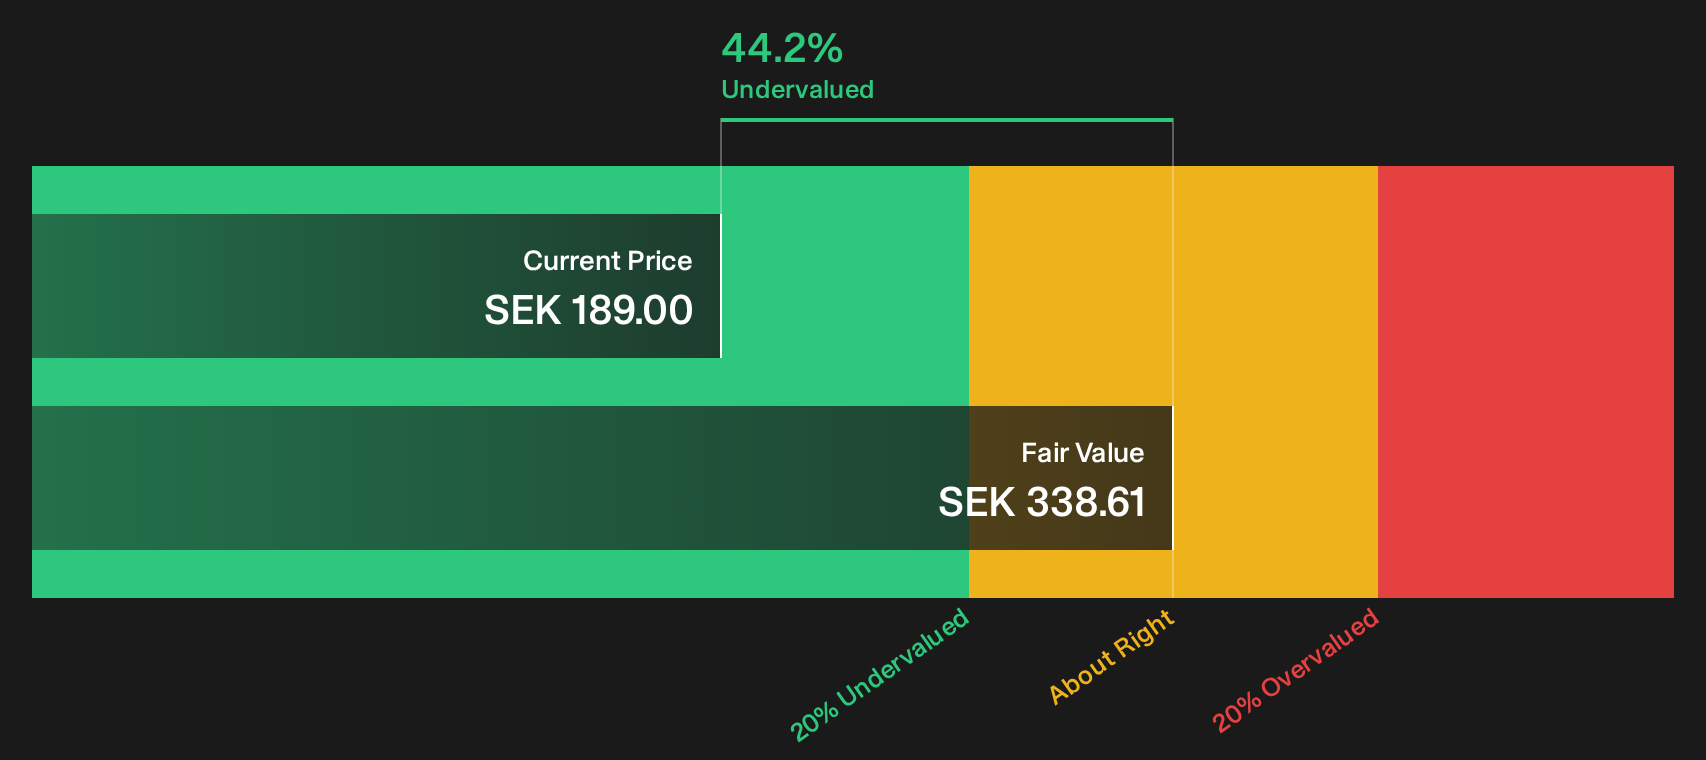
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Inwido for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match – so you never miss a potential opportunity.
Next Steps
If this mix of potential upside and concern around Inwido feels finely balanced, move quickly on your homework and pressure test the data yourself. To weigh both sides in one place, start with our breakdown of 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Inwido?
If Inwido has sharpened your focus, do not stop here. Broaden your watchlist and stress test your portfolio with a few targeted hunting grounds.
- Hunt for potential turnaround opportunities by scanning the 124 elite penny stocks with strong financials that already pair tiny share prices with tangible fundamentals.
- Zero in on quality at a discount by reviewing the 195 high quality undervalued stocks that combine sound cash generation with disciplined balance sheets.
- Lock in consistency by checking the 223 resilient stocks with low risk scores built around resilient financial profiles and lower measured risk scores.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com