Urban Outfitters currently trades at $90.63 and has been a dream stock for shareholders. It’s returned 194% since October 2021, nearly tripling the S&P 500’s 67.4% gain. The company has also beaten the index over the past six months as its stock price is up 25.3%.
Following the strength, is URBN a buy right now? Or is the market overestimating its value? Find out in our full research report, it’s free.
Why does Urban Outfitters spark debate?
Founded as a purveyor of vintage items, Urban Outfitters (NASDAQ:URBN) now largely sells new apparel and accessories to teens and young adults seeking on-trend fashion.
Two things to like:
1. Store growth signals an offensive strategy
A retailer’s store count influences how much it can sell and how quickly revenue can grow.
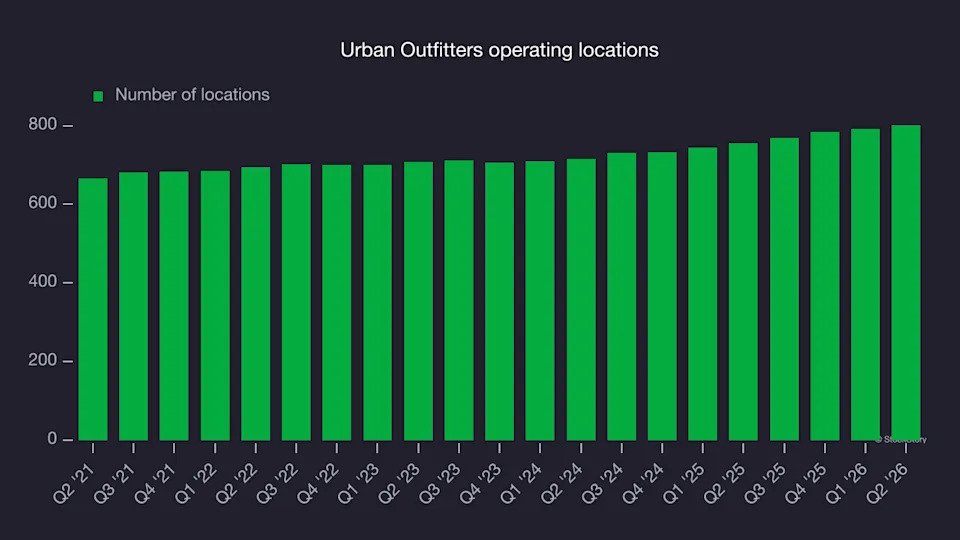
Urban Outfitters operated 801 locations in the latest quarter. It has opened new stores at a rapid clip over the last two years, averaging 5.2% annual growth, much faster than the broader consumer retail sector. This gives it a chance to become a large, scaled business over time.
When a retailer opens new stores, it usually means it’s investing for growth because demand is greater than supply, especially in areas where consumers may not have a store within reasonable driving distance.
2. Surging same-store sales show increasing demand
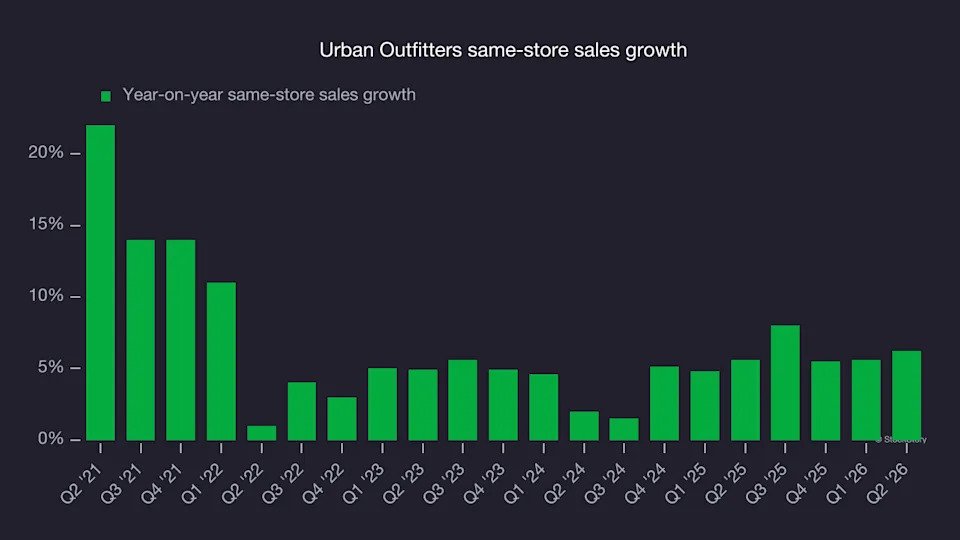
Same-store sales is an industry measure of whether revenue is growing at existing stores, and it is driven by customer visits (often called traffic) and the average spending per customer (ticket).
Urban Outfitters has been one of the most successful retailers over the last two years thanks to skyrocketing demand within its existing locations. On average, the company has posted exceptional year-on-year same-store sales growth of 5.3%.
One reason to be careful:
Long-term revenue growth disappoints
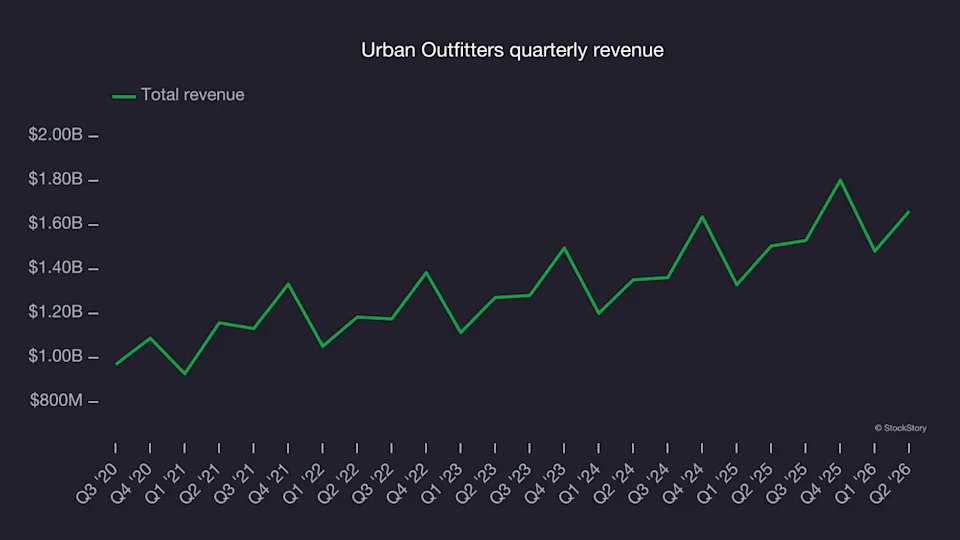
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Unfortunately, Urban Outfitters’s 9.4% annualized revenue growth over the last three years was mediocre. This wasn’t a great result compared to the rest of the consumer retail sector, but there are still things to like about Urban Outfitters.
Final judgment
Urban Outfitters’s positive characteristics outweigh the negatives, and with its shares topping the market in recent months, the stock trades at 13.3× forward P/E (or $90.63 per share). Is now the time to initiate a position? See for yourself in our comprehensive research report, it’s free.