Excelerate Energy currently trades at $33.29 per share and has shown little upside over the past six months, posting a small loss of 0.6%. The stock also fell short of the S&P 500’s 7.5% gain during that period.
Is now the time to buy Excelerate Energy, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why is Excelerate Energy not exciting?
We’re cautious about Excelerate Energy. Here are three reasons we avoid EE, plus one stock we’d rather own.
1. Fewer distribution channels limit its ceiling
In Energy, scale separates fragile single-asset producers from platform-style businesses that generate revenue across entire basins and infrastructure networks.
Excelerate Energy’s $1.47 billion of revenue in the last year is pretty small for the industry, suggesting the company is a subscale business in an industry where scale matters.
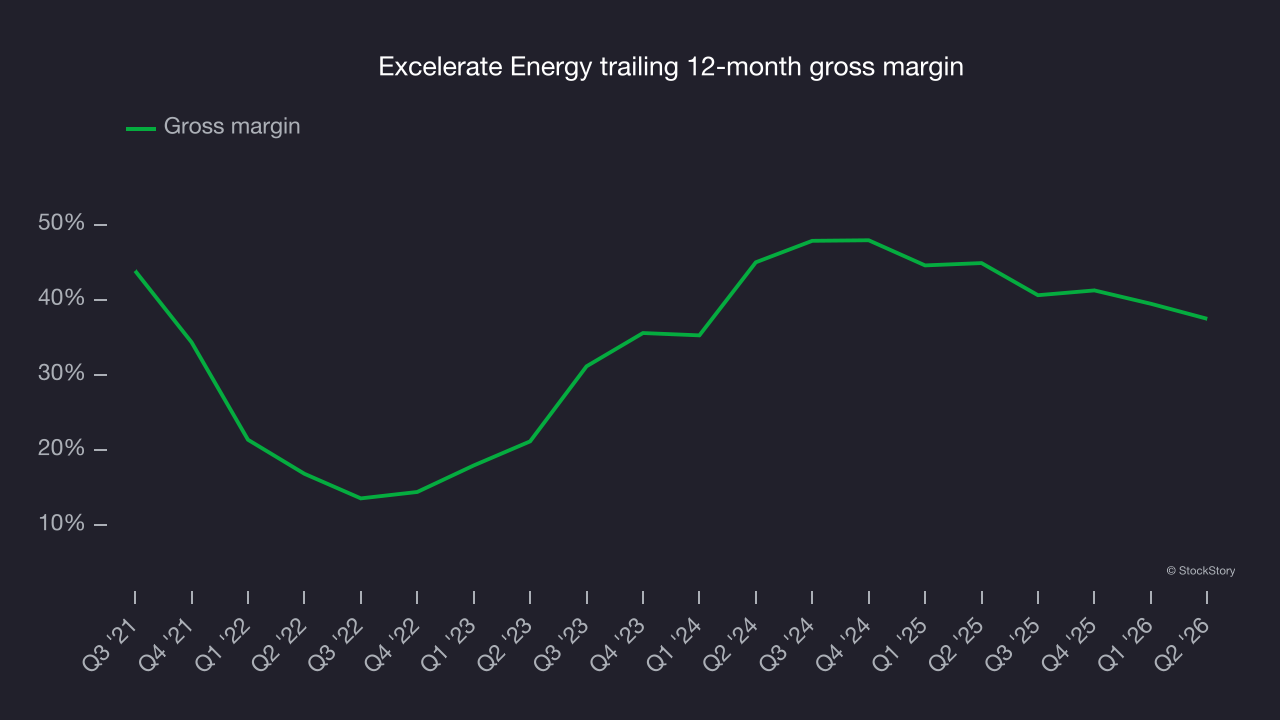
2. Low gross margin reveals weak structural profitability
In a single quarter or year, gross margins in the sector can swing wildly due to commodity prices, hedging, or changes in labor costs. Over a multi-year period across different points in the cycle, gross margin differences can signal whether a company is a structurally-advantaged producer (“rock” quality, takeaway, operating costs) or not.
Excelerate Energy, which averaged 29.9% gross margin over the last five years, exhibited bottom-tier unit economics in the sector. It means the company will struggle at higher commodity prices than peers with better gross margins.
3. Mediocre free cash flow margin limits reinvestment potential
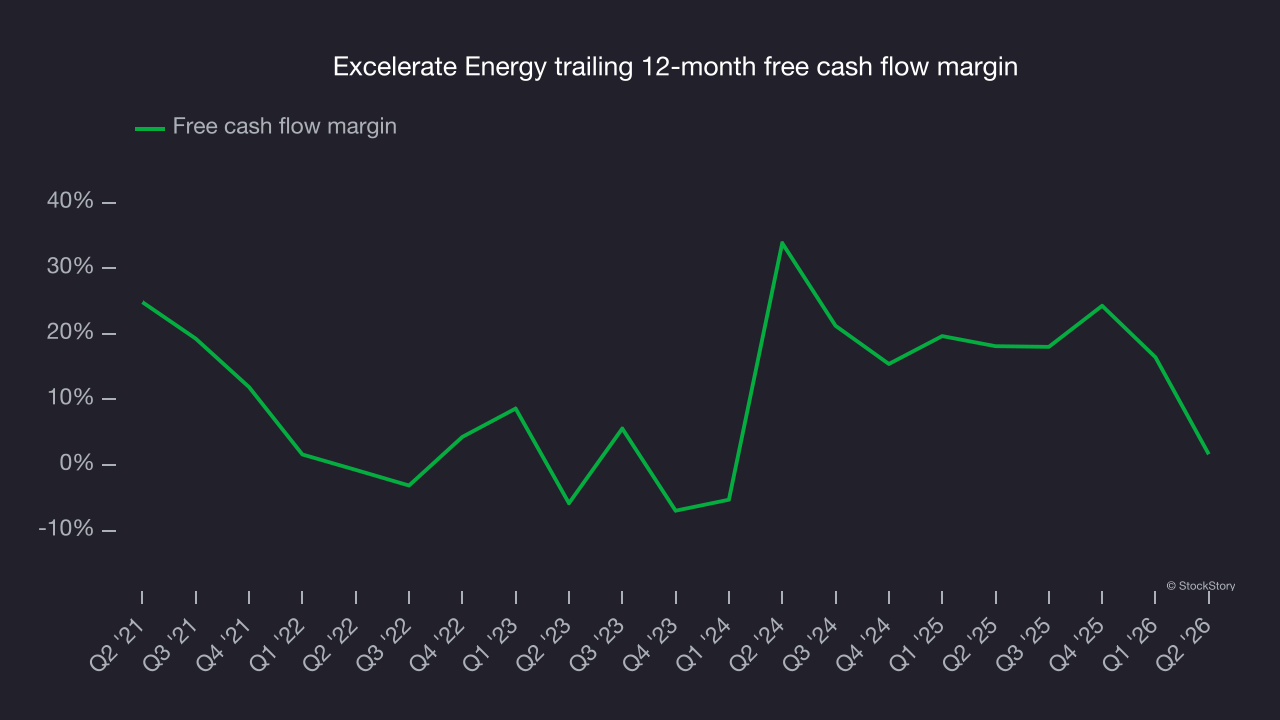
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Excelerate Energy has shown mediocre cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 5.5%, below what we’d expect for an upstream and integrated energy business.
Final judgment
Excelerate Energy’s business quality ultimately falls short of our standards. With its shares lagging the market recently, the stock trades at 16.6× forward P/E (or $33.29 per share). Investors with a higher risk tolerance might like the company, but we think the potential downside is too great. We’re fairly confident there are better stocks to buy right now. Let us point you toward the most dominant software business in the world.
High-quality stocks for all market conditions
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.