Companies developing advanced semiconductors, building data centers, and creating artificial intelligence (AI) applications are attracting historic levels of investment capital. However, some valuation indicators suggest that investors might be getting carried away.
The Shiller cyclically adjusted price-to-earnings (CAPE) ratio, which compares stock prices to average inflation-adjusted earnings over the previous 10 years, currently stands around 41. For perspective, its historical average is approximately 17, and the last time the CAPE ratio consistently exceeded 40 was during the dot-com bubble.
Meanwhile, the Buffett indicator, which measures the total value of the U.S. stock market relative to gross domestic product (GDP), is hovering around 230%. Warren Buffett warns that investors are in dangerous territory when this ratio approaches 200%.
While neither metric guarantees an imminent crash, both suggest that stock valuations are historically expensive. Fortunately, investors don’t necessarily need to abandon growth stocks if the market experiences a downturn.
In fact, two companies held by Berkshire Hathaway could emerge as compelling long-term investments: Apple (AAPL -0.94%) and Alphabet (GOOGL +1.34%)(GOOG +1.60%). Here’s why these Buffett stocks could still thrive even if the broader market struggles.

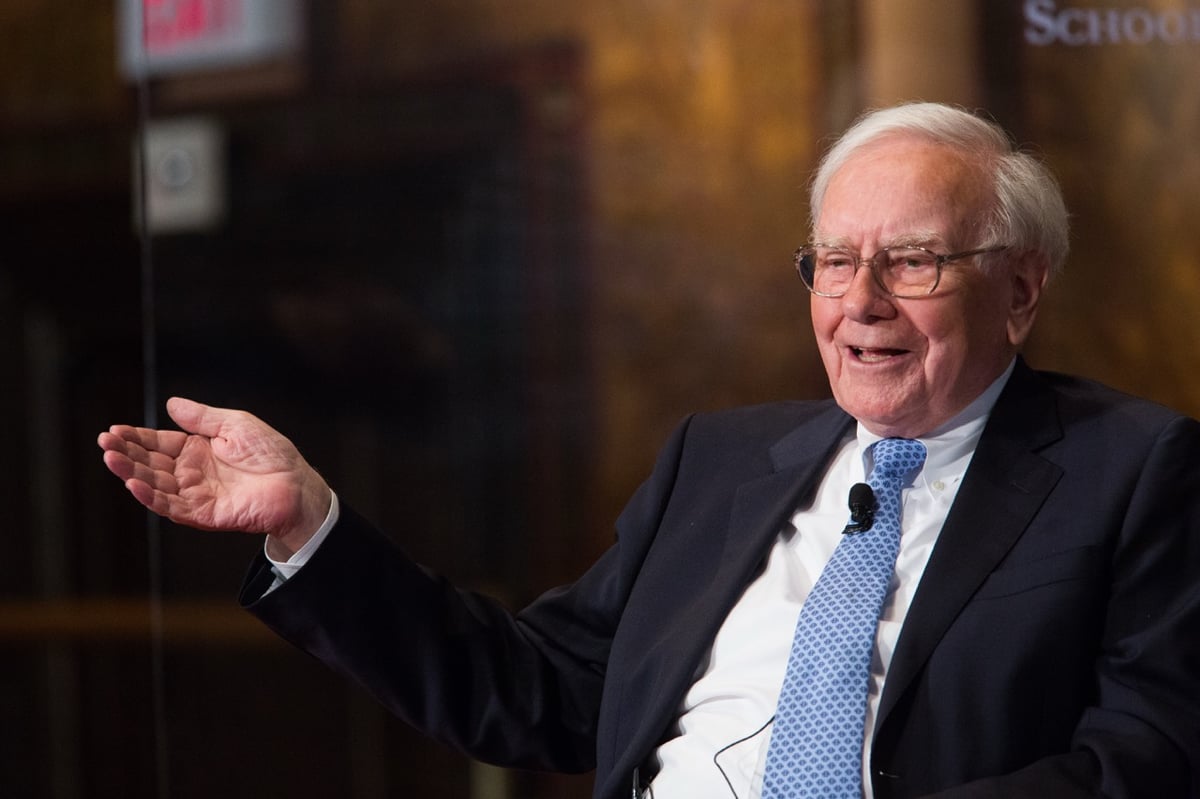
Warren Buffett. Image source: Getty Images.
Apple can dominate consumer electronics without AI
Buffett began building Berkshire’s position in Apple in 2016. The iPhone maker possesses many attributes that Buffett prioritizes: brand loyalty, pricing power, an ability to generate substantial cash flow, and a track record of rewarding shareholders through buybacks. Although Berkshire has reduced its exposure to Apple in recent years, Apple remains its largest holding.
Apple’s investment thesis does not depend entirely on the proliferation of AI. The company already offers a variety of hardware products encompassing the iPhone, Mac, iPad, and Apple Watch, alongside a growing portfolio of subscription services. These products complement one another, encouraging customers to remain within Apple’s ecosystem rather than switching to competing platforms.
During its fiscal third quarter, Apple generated $109.4 billion in revenue, representing 16% year-over-year growth. iPhone revenue increased 22%, while Mac sales climbed 30%.
Moreover, Apple’s Services business generated $30.7 billion in revenue, up 12%. This segment includes the App Store, iCloud, Apple Music, and Apple TV. This growth is important because subscriptions carry higher profit margins than hardware, making them particularly valuable during periods of economic uncertainty.
Of course, AI can strengthen Apple’s position. The company’s Apple Intelligence platform and redesigned Siri voice assistant aim to bring generative AI capabilities directly onto devices. In turn, these features could encourage customers to upgrade their iPhones and laptops — making Apple’s moat even harder to breach.
But even if AI adoption is slower than anticipated, Apple still benefits from its installed base of more than 2.5 billion active devices and more than 1.5 billion paid subscriptions. That’s an important distinction to recognize, as Apple doesn’t need to become a pure-play AI company to continue generating profits.
A market crash would likely put short-term pressure on Apple stock. Still, the company’s loyal customer base, recurring services revenue, and cash generation would also support a powerful recovery once market conditions improve.
AAPL Apple
$343.83-$3.27 (-0.94%)
NASDAQ · As of 4:00 PM ET 10/28/26
Alphabet is an advertising and cloud computing empire
Berkshire established its position in Google’s parent company during 2025 and throughout this year, too. Similar to Apple, Alphabet already has several highly profitable operations independent of AI.
The company’s most important asset is Google Search. This business has historically benefited from an attractive economic model where advertisers pay Google to reach potential customers, while the company’s global user base and sophisticated search algorithms create unique competitive advantages.
Nevertheless, AI is making Google’s existing businesses even more valuable. For example, AI Overviews allow Google to provide more in-depth analysis to user queries. These capabilities could improve engagement and create new opportunities for advertisers to reach customers, rather than spreading their budgets across search-heavy chatbots like ChatGPT or Claude.
In addition, the company’s Gemini AI models are being integrated throughout Google Workspace and Android, potentially strengthening customer stickiness and creating additional monetization opportunities.
Rounding out Alphabet’s ecosystem is Google Cloud. Within the cloud division, Alphabet develops its own specialized chips, known as Tensor Processing Units (TPUs). These processors can help the company better manage AI infrastructure costs while also offering customers an alternative to traditional GPUs from Nvidia.
GOOGL Alphabet
$324.89+$4.31 (+1.34%)
NASDAQ · As of 4:00 PM ET 10/28/26
Apple and Alphabet are built to last
Both Apple and Alphabet would likely experience fleeting stock price declines if the broader market crashes. No company is immune to valuation compression or economic weakness. However, their underlying businesses are far more diversified than those of many companies whose investment theses depend almost exclusively on AI adoption.
AI has proven to strengthen both companies, but neither needs the AI revolution to unfold perfectly to remain profitable. That’s exactly why Apple and Alphabet could still deliver market-beating returns in the long run, even if the stock market experiences a harsh correction along the way.