
Healthcare services provider BrightSpring Health Services (NASDAQ:BTSG) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 26.4% year on year to $4.21 billion. The company’s full-year revenue guidance of $16.01 billion at the midpoint came in 4.2% above analysts’ consensus estimates. Its non-GAAP profit of $0.54 per share was 14.7% above analysts’ consensus estimates.
For more on BrightSpring Health Services, read our full research report.
BrightSpring Health Services (BTSG) Q3 2026 highlights:
- Revenue $4.21 billion vs S&P analysts’ consensus estimates of $3.87 billion (26.4% year-on-year growth, 8.9% beat)
- Adjusted EPS $0.54 vs S&P analysts’ consensus estimates of $0.47 (14.7% beat)
- Adjusted EBITDA $227.8 million vs analysts’ consensus estimates of $214.8 million (5.4% margin, 6% beat)
- Revenue guidance The company lifted its revenue guidance for the full year to $16.01 billion at the midpoint from $15.26 billion, a 4.9% increase
- EBITDA guidance $855 million at the midpoint for the full year, above analysts’ consensus estimates of $837.1 million
- Operating margin 3.8%, up from 2.6% in the same quarter last year
- Free cash flow margin 4.3%, up from 2.8% in the same quarter last year
- Market capitalization $12.55 billion
“Our third quarter results again reflect the commitment of our team to patient care and operational execution across our Pharmacy and Provider businesses,” said Jon Rousseau, Chairman, President and Chief Executive Officer of BrightSpring. “We have a differentiated company, our value proposition for healthcare stakeholders is clear, and our confidence in the future remains high, supported by a broad set of process and growth drivers across a uniquely scaled and high-quality platform. As we progress through 2026, we believe that BrightSpring is well-positioned to make a greater and greater impact and deliver durable growth in 2027 and beyond.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. BrightSpring Health Services’s 20.3% annualized revenue growth over the last five years was impressive. Its growth beat the average healthcare company and shows its offerings resonate with customers.

Long-term growth matters most, but within healthcare, a half-decade historical view may miss recent innovations or disruptive industry trends. BrightSpring Health Services’s annualized revenue growth of 25.4% over the last two years is above its five-year trend, suggesting its demand was strong and recently accelerated. 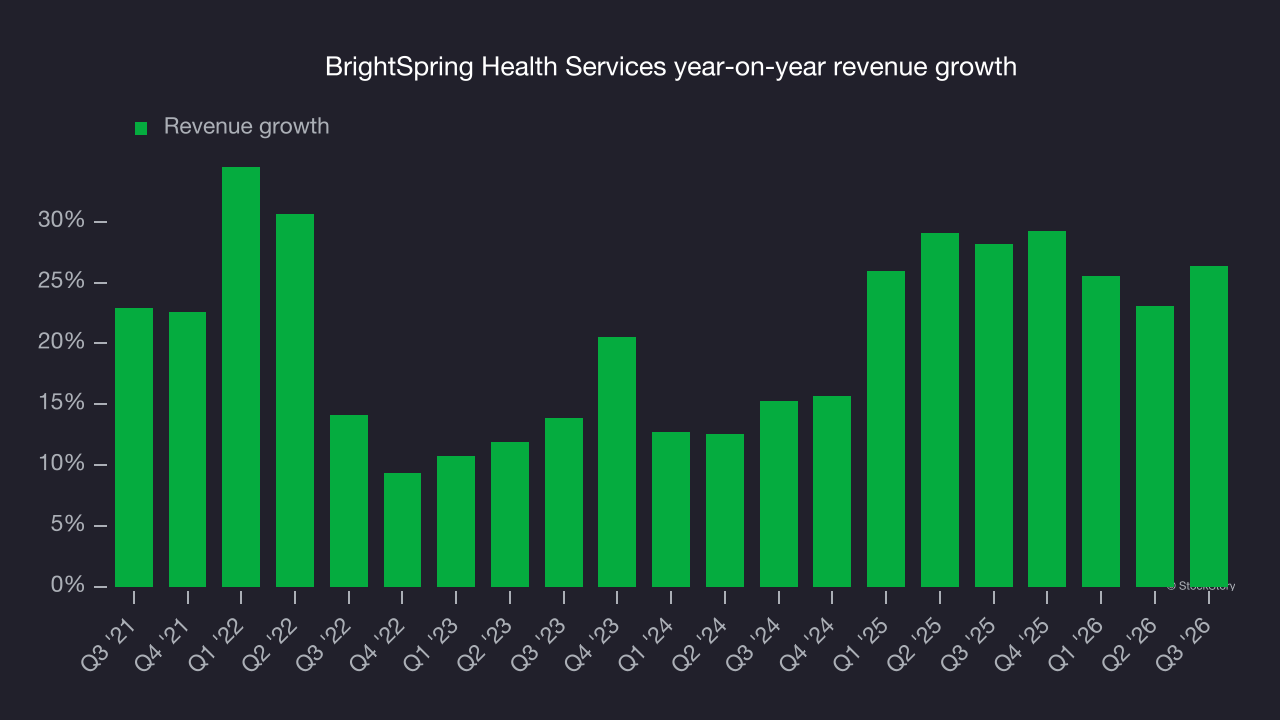
The company’s most important segment, Pharmacy, helps explain its revenue dynamics. Over the last two years, BrightSpring Health Services’s Pharmacy revenue averaged 28% year-on-year growth. 
This quarter, BrightSpring Health Services reported strong year-on-year revenue growth of 26.4%, and its $4.21 billion of revenue topped Wall Street’s consensus estimates by 8.9%.
Looking ahead, sell-side analysts expect revenue to grow 11.1% over the next 12 months, according to S&P, a deceleration versus the last two years. Its growth trajectory remains attractive given its scale and implies the market sees success for its products and services.
Adjusted operating margin
Adjusted operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses, from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies because it excludes non-recurring expenses, interest on debt and taxes.
BrightSpring Health Services’s adjusted operating margin has largely stayed the same over the last 12 months, averaging 3.8% over the last five years. This profitability was paltry for a healthcare business and caused by its suboptimal cost structure.
BrightSpring Health Services’s adjusted operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
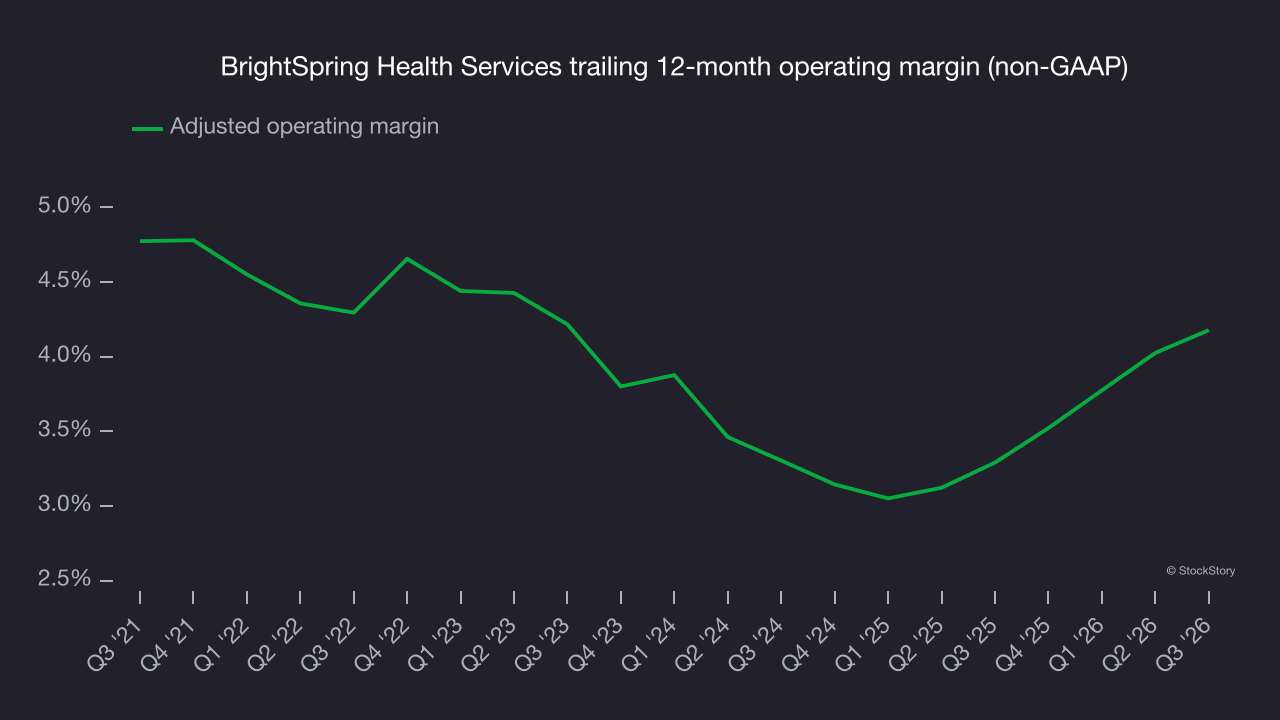
This quarter, BrightSpring Health Services generated an adjusted operating margin of 4.2%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Free cash flow
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but it’s revealing because it accounts for all operating and capital expenses, making it difficult to manipulate.
BrightSpring Health Services has shown mediocre cash profitability relative to peers over the last five years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 1.5%, below expectations for a healthcare business.
On the positive side, BrightSpring Health Services’s margin expanded by 1.6 percentage points during that time. The improvement shows it’s heading in the right direction and indicates it became a less capital-intensive business, as its free cash flow profitability rose while its operating profitability was flat.
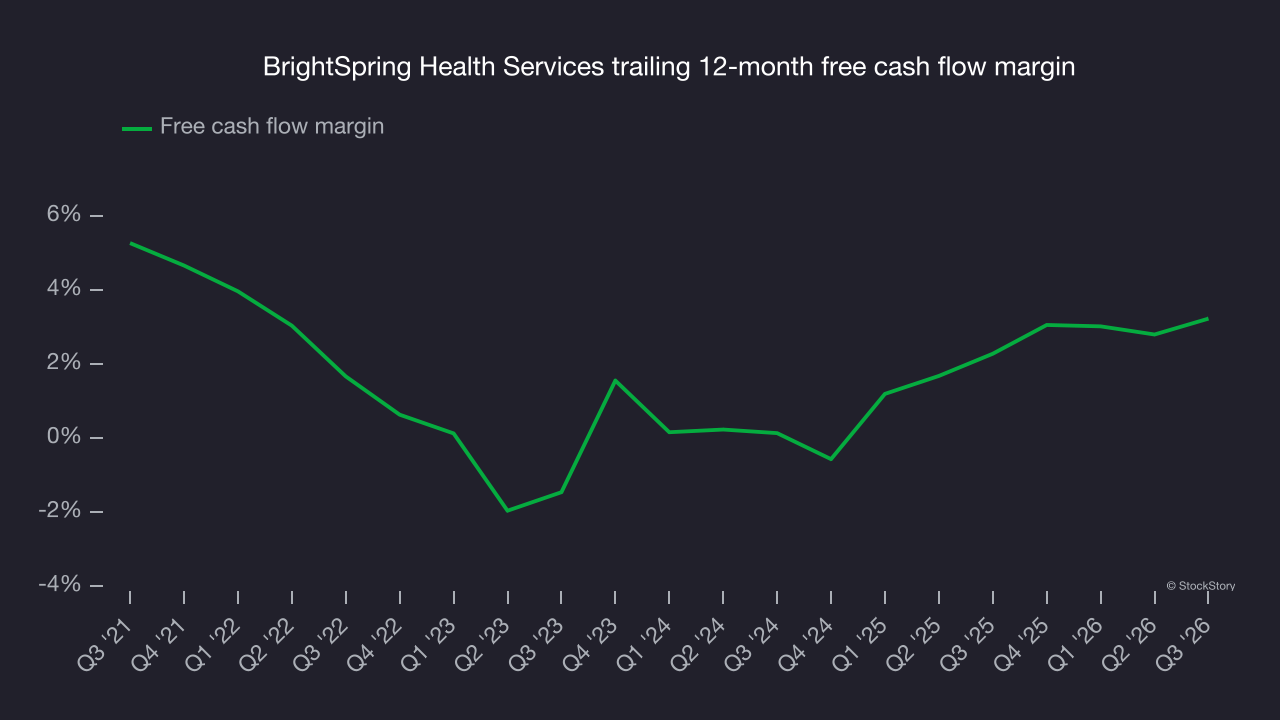
BrightSpring Health Services’s free cash flow was $182.2 million in Q3, equivalent to a 4.3% margin. This was a positive result, as its margin was 1.6 percentage points higher than in the same quarter last year, building on its favorable historical trend.
Key takeaways from BrightSpring Health Services’s Q3 results
BrightSpring Health Services delivered a strong quarter, with revenue well above analysts’ consensus estimates and full-year revenue guidance also topping Wall Street’s consensus. Shares surged 7.1% to $64.50 immediately after the results.
BrightSpring Health Services had a solid quarterly earnings result, but assessing whether the stock is a good investment requires a broader view. That decision should take into account valuation, business quality and the latest earnings. For more on that, read our full research report here (it’s free).











