Over the last six months, Mission Produce’s shares have sunk to $11.61, producing a disappointing 16.3% loss – a stark contrast to the S&P 500’s 7.5% gain. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Mission Produce, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why is Mission Produce not exciting?
Despite the more favorable entry price, we’re cautious about Mission Produce. Here are three reasons we avoid AVO, plus one stock we’d rather own.
1. Fewer distribution channels limit its ceiling
With $1.34 billion in revenue over the past 12 months, Mission Produce is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers. On the bright side, it can grow faster because it has a longer list of untapped store chains to sell into.
2. Low gross margin reveals weak structural profitability
All else equal, we prefer higher gross margins because they make it easier to generate more operating profits and indicate that a company commands pricing power by offering more differentiated products.
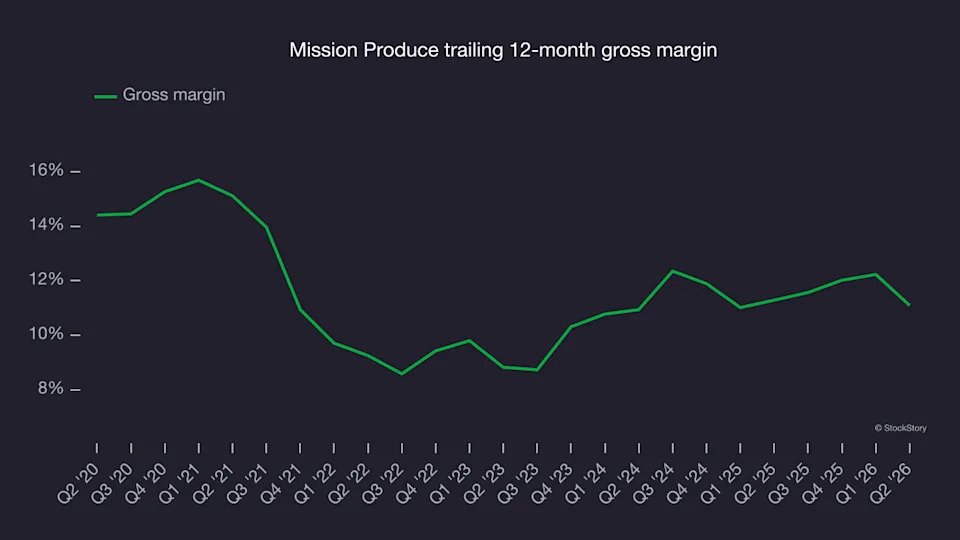
Mission Produce has bad unit economics for a consumer staples company, signaling it operates in a competitive market and lacks pricing power because its products can be substituted. As you can see below, it averaged an 11.2% gross margin over the last two years. That means Mission Produce paid its suppliers a lot of money ($88.81 for every $100 in revenue) to run its business.
3. Previous growth initiatives haven’t impressed
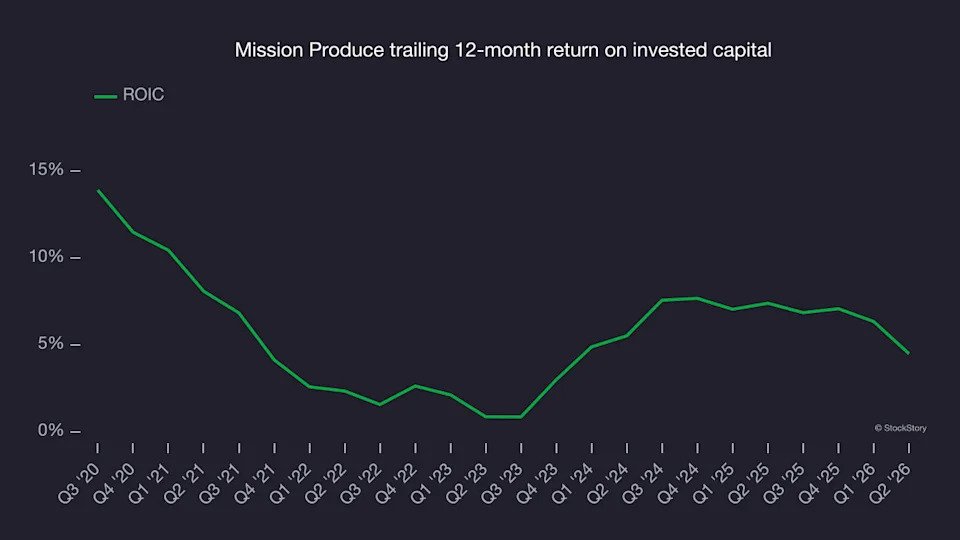
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Mission Produce historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 4.1%, lower than the typical cost of capital (how much it costs to raise money) for consumer staples companies.
Final judgment
Mission Produce isn’t a terrible business, but it isn’t one of our picks. Following the recent decline, the stock trades at 16.2× forward P/E (or $11.61 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re pretty confident there are more exciting stocks to buy at the moment. We’d recommend looking at a top digital advertising platform riding the creator economy.