Jabin Bastian
5 min read
Offshore drilling contractor Transocean (NYSE:RIG) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 8.9% year on year to $937 million. Its non-GAAP loss of $0 per share was $0.02 below analysts’ consensus estimates.
For more on Transocean, read our full research report.
Transocean (RIG) Q3 2026 highlights:
-
Revenue $937 million vs S&P analysts’ consensus estimates of $943.2 million (8.9% year-on-year decline, 0.7% miss)
-
Adjusted EPS $0 vs S&P analysts’ consensus estimates of $0.02 ($0.02 miss)
-
Adjusted EBITDA $313 million vs analysts’ consensus estimates of $295.4 million (33.4% margin, 6% beat)
-
Operating margin 15.3%, an increase from -163% in the same quarter last year
-
Free cash flow margin 14%, a decline from 22.9% in the same quarter last year
-
Market capitalization $7.75 billion
“Since our last report, we delivered solid operating results and significantly strengthened forward contract visibility,” said Keelan Adamson, Transocean’s CEO. “Strong cash flow enabled us to retire the remaining $200 million of debt associated with the Deepwater Aquila notes, ahead of schedule. New deepwater and harsh-environment awards increased our backlog to approximately $8.0 billion and improved 2027 contract coverage to approximately 95%.
Revenue growth
Cyclical sectors like energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. Over the last five years, Transocean grew its revenue at a tepid 7.1% compounded annual growth rate, falling short of the standard for the energy upstream and integrated energy sector.
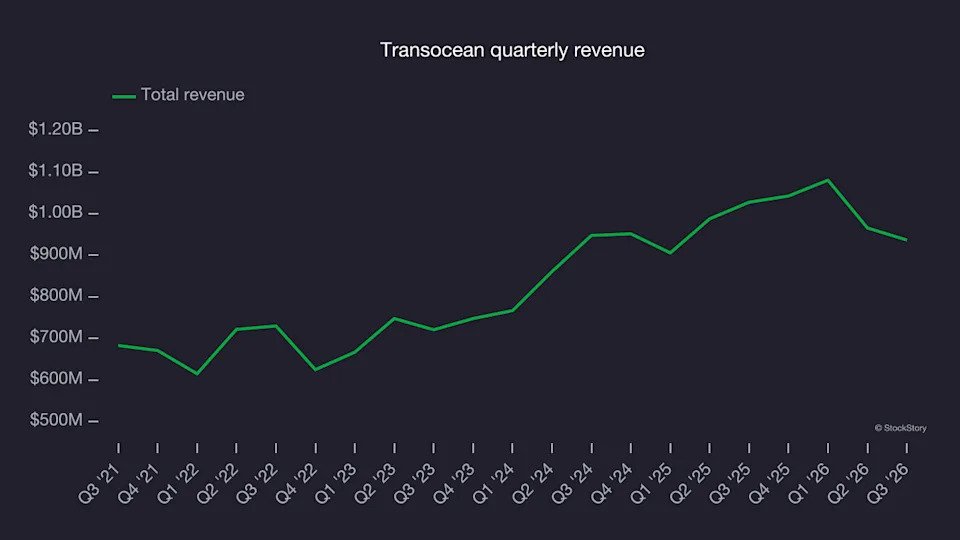
Even a long stretch in energy can be shaped by a single commodity cycle, so extending the view to ten years adds another perspective and reveals which companies can grow across pricing environments. Transocean grew over the past five years but lost ground over the last ten years, as its revenue fell by 2.2% annually.
This quarter, Transocean missed Wall Street’s consensus estimates and reported an uninspiring 8.9% year-on-year revenue decline, generating $937 million in revenue.
Adjusted EBITDA margin
Adjusted EBITDA margin strips out accounting distortions tied to depletion and historical drilling spend, providing a clearer view of the cash-generating power of the underlying asset base before financing and reinvestment decisions.
Transocean was profitable over the last five years but held back by its large cost base. Its average EBITDA margin of 32.1% was weak for an upstream and integrated energy business.