Central Garden & Pet has had an impressive run over the past six months as its shares have beaten the S&P 500 by 25.2%. The stock now trades at $46.37, marking a 30% gain. This performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Central Garden & Pet, or does it present a risk to your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why do we think Central Garden & Pet will underperform?
Despite the momentum, we’re sitting this one out for now. Here are three reasons you should be careful with CENT, plus one stock we’d rather own.
1. Revenue spiraling downwards
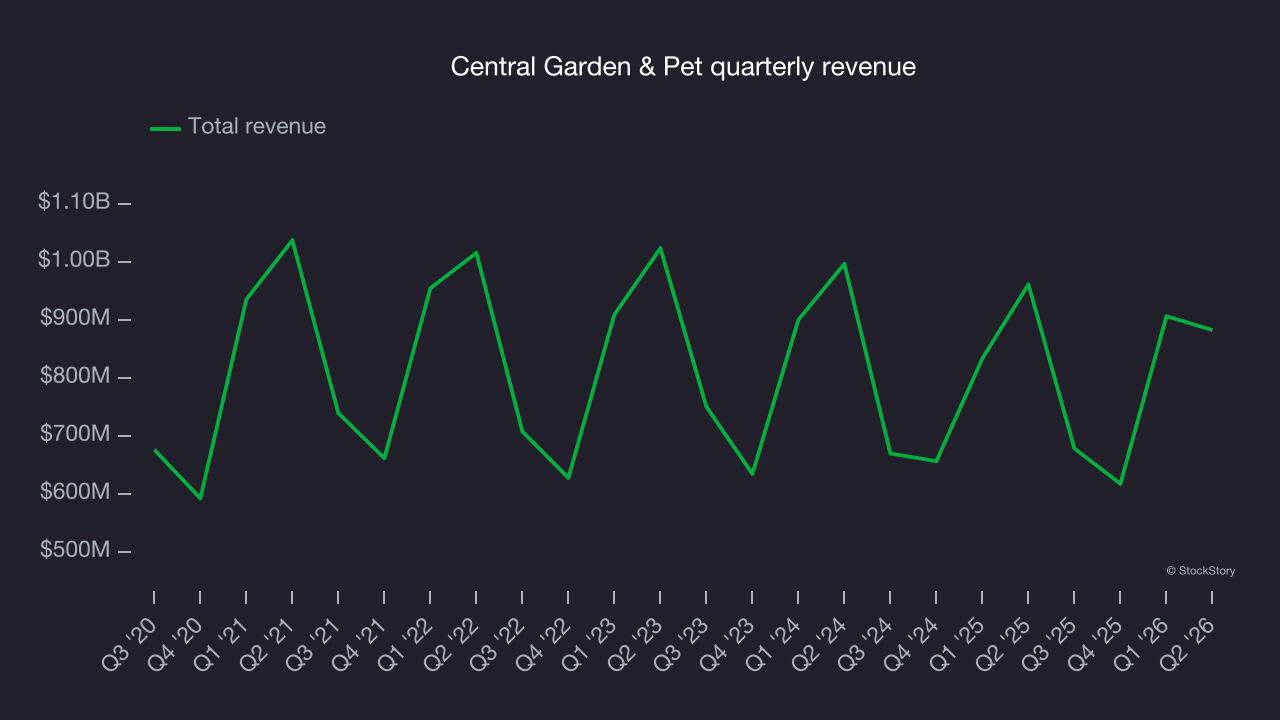
A company’s long-term sales performance is one signal of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Central Garden & Pet struggled to consistently generate demand over the last three years as its sales dropped at a 1.9% annual rate. This was below our standards and is a sign of poor business quality.
2. Revenue projections show stormy skies ahead
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Central Garden & Pet’s revenue to drop by 5.1%, according to S&P, a decrease from its 1.9% annualized declines for the past three years. This projection doesn’t excite us and indicates its products will see some demand headwinds.
3. Previous growth initiatives haven’t impressed
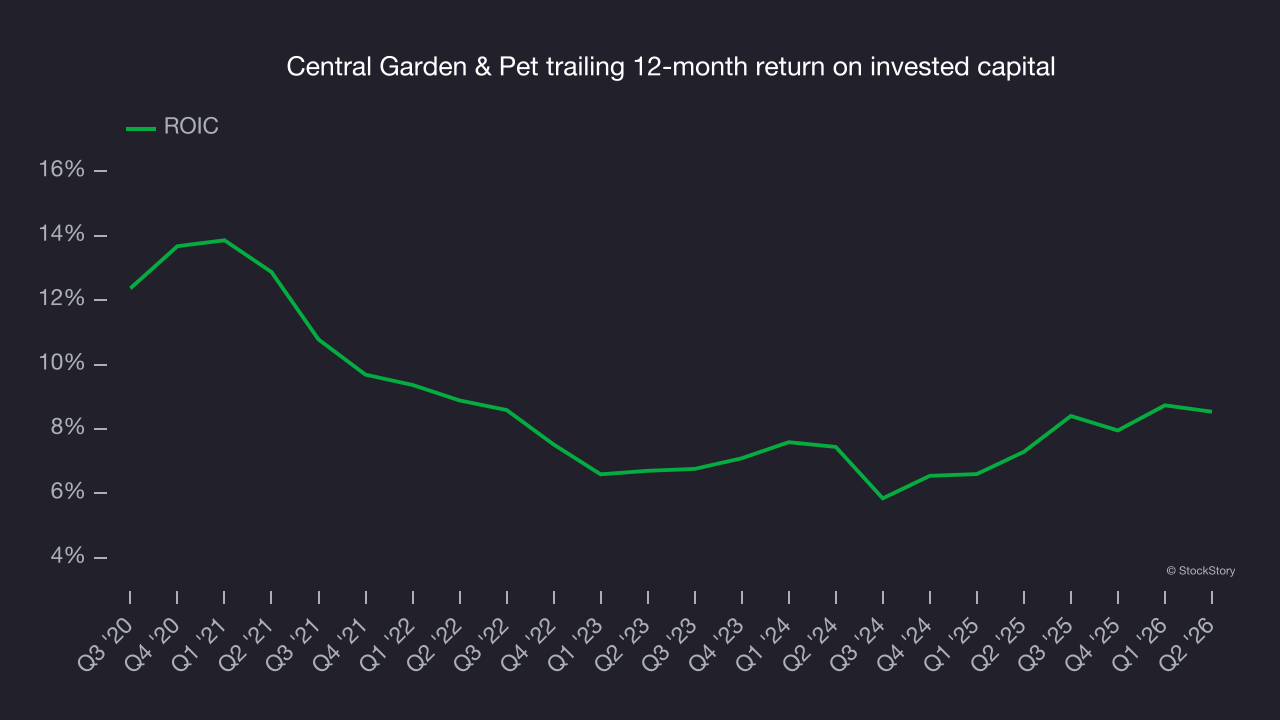
Growth gives us insight into a company’s long-term potential, but how capital-efficient was that growth? Enter ROIC, a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Central Garden & Pet historically did a mediocre job investing in profitable growth initiatives. Its five-year average ROIC was 7.8%, somewhat low compared to the best consumer staples companies that consistently pump out 30%+.
Final judgment
We cheer for all companies serving everyday consumers, but in the case of Central Garden & Pet, we’ll be cheering from the sidelines. With its shares topping the market in recent months, the stock trades at 16.4× forward P/E (or $46.37 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in – we think other companies feature superior fundamentals at the moment. We’d suggest looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
High-quality stocks for all market conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.