Since November 2021, the S&P 500 has delivered a total return of 61%. But one standout stock has more than doubled the market – over the past five years, Robinhood has surged 136% to $87.38 per share. Its momentum hasn’t stopped as it’s also gained 13.4% in the last six months, beating the S&P by 9.2%.
Following the strength, is HOOD a buy right now? Or is the market overestimating its value? Find out in our full research report, it’s free.
Why are we positive on Robinhood?
With a mission to democratize finance, Robinhood (NASDAQ:HOOD) is an online consumer finance platform known for its commission-free stock and crypto trading.
1. Eye-popping growth in customer spending
Average revenue per user (ARPU) is a critical metric to track because it measures how much the company earns in fees from each user. ARPU also gives us unique insights into the average transaction size on Robinhood’s platform and the company’s take rate, or “cut”, on each transaction.
Robinhood’s ARPU growth has been exceptional over the last two years, averaging 38.8%. Its ability to increase monetization while growing its funded customers demonstrates its platform’s value, as its users are spending significantly more than last year. 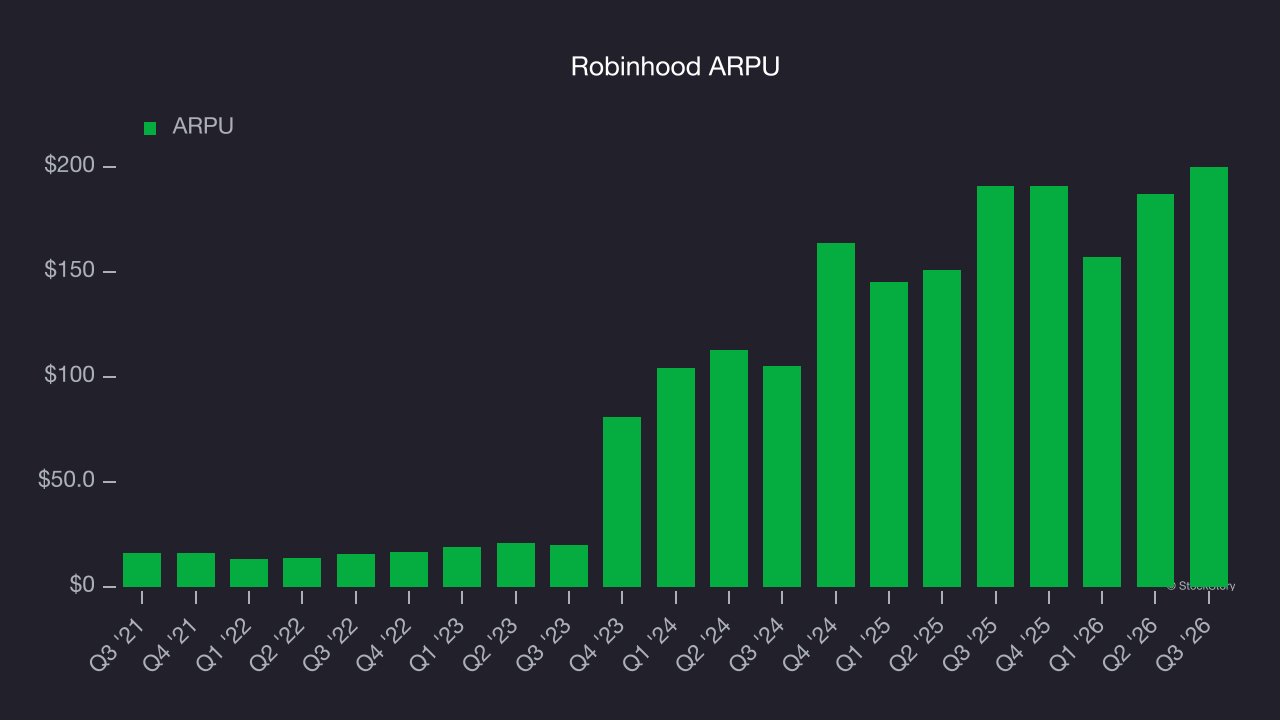
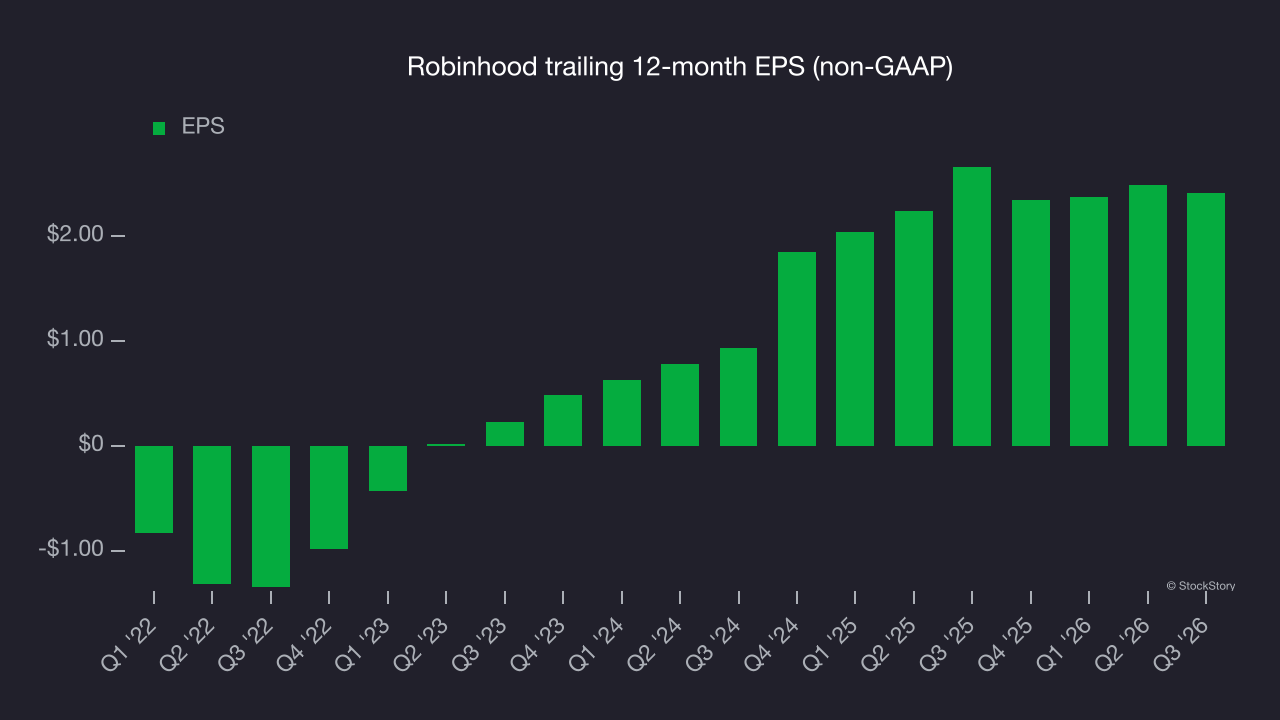
2. Outstanding long-term EPS growth
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Robinhood’s EPS grew at 118% compounded annual growth rate over the last three years, higher than its 42% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
3. Excellent free cash flow margin boosts reinvestment potential
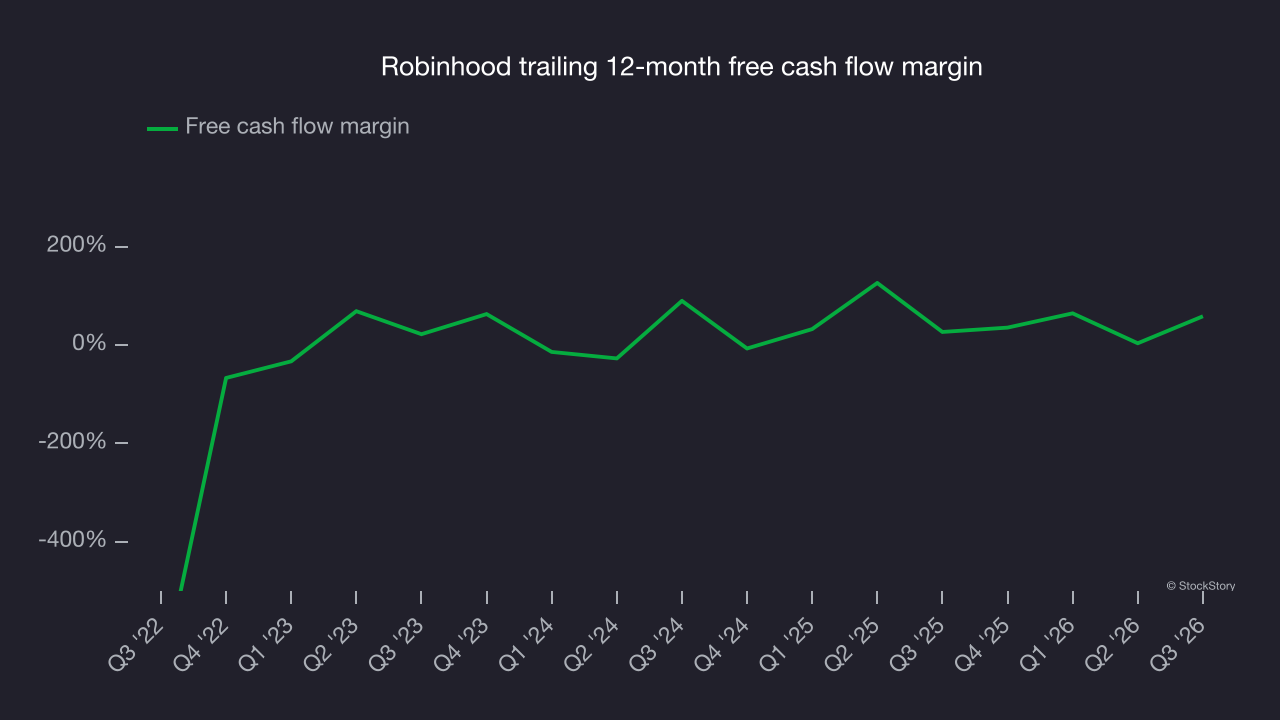
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Robinhood has shown terrific cash profitability, driven by its lucrative business model and cost-effective customer acquisition strategy that enable it to stay ahead of the competition through investments in new products rather than sales and marketing. The company’s free cash flow margin was among the best in the consumer internet sector, averaging an eye-popping 44% over the last two years.
Final judgment
These are just a few reasons why Robinhood ranks near the top of our list, and with its shares topping the market in recent months, the stock trades at 21.5× forward EV/EBITDA (or $87.38 per share). Is now a good time to initiate a position? See for yourself in our in-depth research report, it’s free.
Stocks we like even more than Robinhood
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.