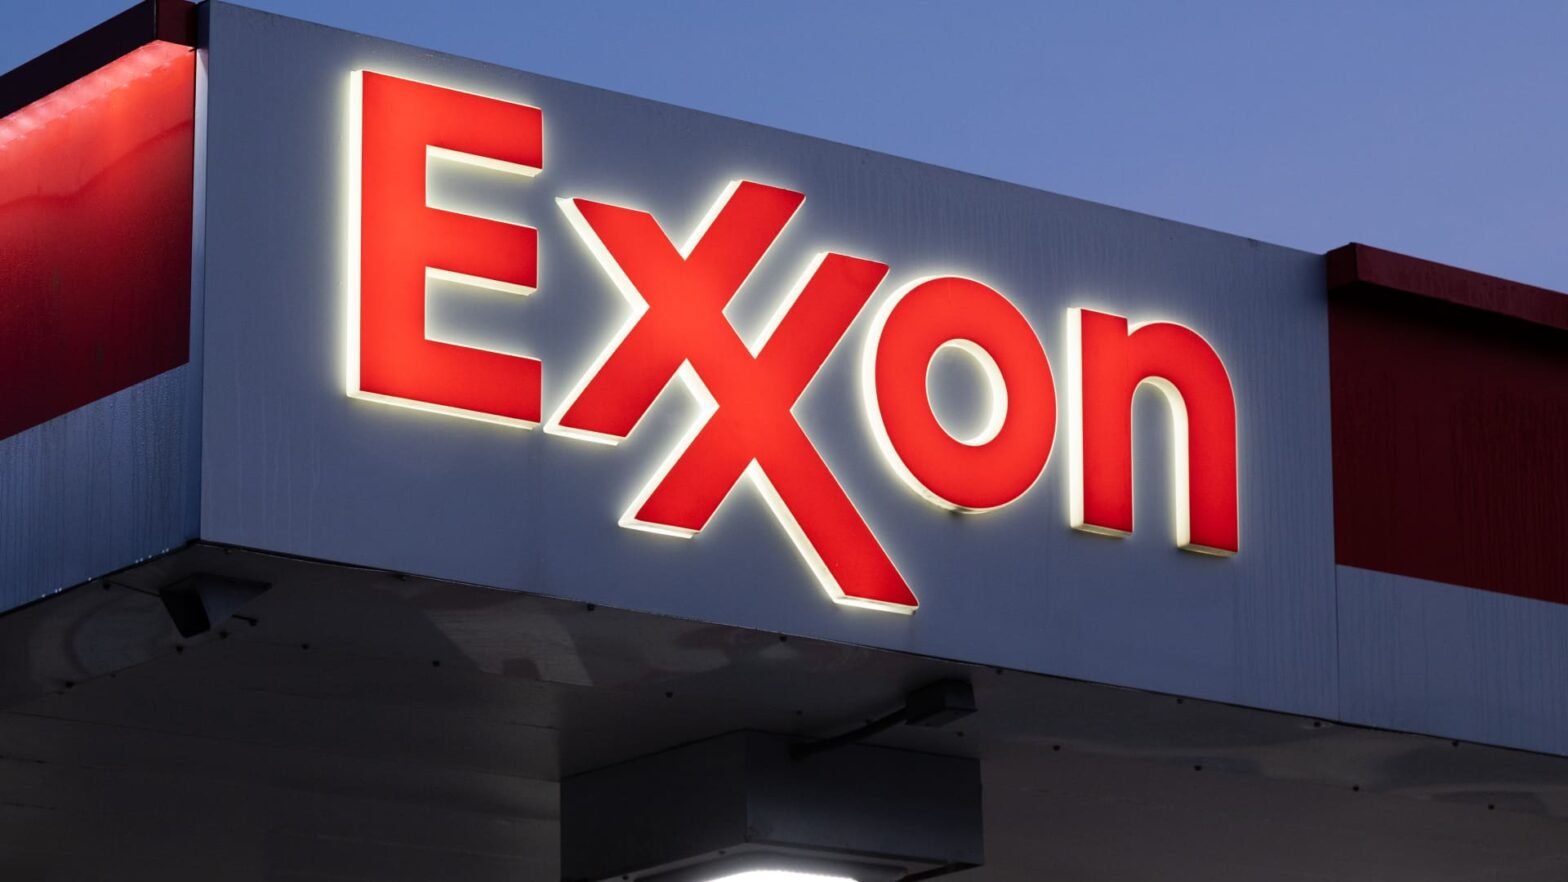
Signage at an Exxon Mobil gas station in Daly City, California, US, on Thursday, Jan. 29, 2026.
Benjamin Fanjoy | Bloomberg | Getty Images
Democrats’ midterm election win has put the artificial intelligence trade in question, as voters clearly expressed opposition to the rapid buildout of data centers. The stock market could remain volatile amid AI trade concerns, macro uncertainties, and geopolitical tensions.
In this scenario, investors can add dividend-paying stocks to their portfolios to earn steady income. However, the extensive universe of dividend stocks can make selection challenging. Top Wall Street analysts’ recommendations can help investors shortlist attractive dividend stocks, as these experts assign ratings after in-depth financial analysis.
Here are three dividend-paying stocks that are highlighted by Wall Street’s top pros, as tracked by TipRanks, a platform that ranks analysts based on their past performance.
Viper Energy
Viper Energy (VNOM) is a subsidiary of Diamondback and owns and acquires mineral and royalty interests, primarily in the Permian Basin. The company reported upbeat third-quarter earnings, supported by recent acquisitions and continued development activity from Diamondback and third-party operators. Viper announced a base cash dividend of 50 cents per share for Q3 2026, payable on Nov. 19. Based on the base and variable dividends announced over the past 12 months, VNOM’s dividend yield stands at 5.7%.
Following the Q3 results, TD Cowen analyst Aaron Bilkoski reiterated a buy rating on Viper Energy stock with a price target of $61. The analyst noted that the company delivered solid Q3 results, with production, including oil and natural gas liquids, exceeding both TD Cowen and consensus estimates.
The 5-star analyst highlighted that the key update was the announcement of two royalty acquisitions for $809 million in cash, including deferred consideration, and $82 million of newly issued shares.
Given the recently announced base dividend hike, Bilkoski expects Viper to direct incremental free cash flow toward buybacks. While the acquisitions increase leverage, the analyst believes that Viper has enough capacity for opportunistic buybacks.
Bilkoski noted that Viper has historically delivered one of the highest production per share growth profiles in his royalty coverage, but still trades at a notable discount to the royalty peer average and the company’s historical FCF yield range. “In our view, its above-average growth warrants a higher valuation,” said the analyst.
Bilkoski ranks No. 525 among more than 12,500 analysts tracked by TipRanks. His ratings have been profitable 57% of the time, delivering an average return of 12.80%. See Viper Energy Stock Buybacks on TipRanks.
Exxon Mobil
Exxon Mobil (XOM) reported robust Q3 2026 profits, as its U.S. refineries boosted production to capitalize on the high diesel fuel prices sparked by the conflict in the Middle East. The oil and gas giant announced a quarterly dividend of $1.07 per share, payable on Dec. 10, reflecting a 3.9% increase. This marks Exxon’s 44th consecutive year of dividend increases. At an annualized dividend of $4.28 per share, XOM offers a yield of 2.53%.
Impressed by the Q3 print, TD Cowen analyst Jason Gabelman reiterated a buy rating on Exxon stock and raised his price target to $193 from $180 to reflect higher downstream earnings, with the expectation of increased mid-cycle margins.
Gabelman noted that the strength in Exxon’s refining business continues to offset Middle East-related headwinds. He added that the company increased its ownership in LNG projects, which should reduce its Middle East concentration over time from 75% to 50% and lower the likelihood of diversification-focused mergers and acquisitions. Beyond LNG, Gabelman expects Exxon’s growth in the 2030s to come from Guyana, Kashagan, Permian, and possibly Venezuela.
Gabelman noted that Exxon announced a dividend hike of nearly 4% and plans to maintain buybacks at $20 billion for 2027. “The decision to maintain reduces the pro-cyclicality nature of the buyback,” said the analyst.
Gabelman ranks No. 347 among more than 12,500 analysts tracked by TipRanks. His ratings have been successful 66% of the time, delivering an average return of 16.90%. See Exxon Mobil Ownership Structure on TipRanks.
Williams
Williams (WMB), which owns and operates energy infrastructure to deliver natural gas, reported strong third-quarter results. The company announced a quarterly dividend of $0.525 per share, or $2.10 per share annualized, payable on Dec. 28. WMB offers a dividend yield of 3.09%.
In reaction to the Q3 2026 results, CIBC analyst Robert Catellier reaffirmed a buy rating on Williams stock with a price target of $82. The analyst noted that Q3 results were essentially in line with expectations and reflected continued strength in execution across WMB’s infrastructure portfolio.
Catellier said that Williams’ Q3 performance was driven by higher transmission, storage, and power generation revenues, as well as contributions from the Momentum Midstream acquisition.
He noted that Williams maintained its full-year EBITDA guidance of $8.3 billion to $8.5 billion. In fact, results are tracking toward the higher end of the guidance range, backed by contributions from recently completed projects and the Momentum Midstream deal. WMB continues to target long-term EBITDA compound annual growth rate of at least 11% through 2030.
Catellier expects WMB’s long-term targets to be supported by incremental transmission and storage opportunities, including Transco’s Southeast Supply Enhancement II project and an 84 MMcf/d expansion of the Garden Connector project.
Catellier ranks No. 667 among more than 12,500 analysts tracked by TipRanks. His ratings have been successful 66% of the time, delivering an average return of 9.60%. See Williams Technical Analysis on TipRanks.