Pinterest (PINS) is back in focus after third quarter 2026 results showed higher sales but a sharp drop in net income, paired with softer earnings estimates and fresh revenue guidance for the coming quarter.
Pinterest shares closed at US$18.96 after the earnings release, extending a 30 day share price decline of 11.4% and a 90 day fall of 22.2% as investors reacted to weaker profitability. The 1 year total shareholder return of 30% in decline points to momentum that has been fading rather than building.
Scan opportunities beyond Pinterest by reviewing a hand picked 38 high quality undervalued stocks featuring companies that combine solid fundamentals with pricing that may not yet reflect them.
Pinterest still runs a large visual discovery platform with billions in annual sales, yet the share price has slid hard this year. Is that operating strength now on sale or fairly captured in today’s valuation?
Most Popular Narrative: 27% Undervalued
Pinterest closed at $18.96 while the most followed narrative pegs fair value closer to $26.06, which implies meaningful upside baked into that framework and places the recent drawdown in a very different light.
Ongoing advancements in AI-driven visual search and personalized content curation, supported by proprietary multimodal and generative retrieval models, are deepening user engagement and increasing session times. These developments may contribute to higher average revenue per user and support revenue and margin outcomes over time.
See why 117 investors see Pinterest as 27% undervalued.
That storyline rests on a discount rate of 8.86% and assumes Pinterest can turn its large user base into stronger earnings power over time. This helps explain why the narrative fair value of roughly $26.06 sits well above the current $18.96 share price.
Result: Fair Value of $26.06 (UNDERVALUED)
Still, the Pinterest narrative can break if international users remain under-monetized and if newer AI powered ad products in other channels continue to divert advertiser budgets away.
Find out about the key risks to this Pinterest narrative.
Another View: Pinterest Looks Expensive On Earnings
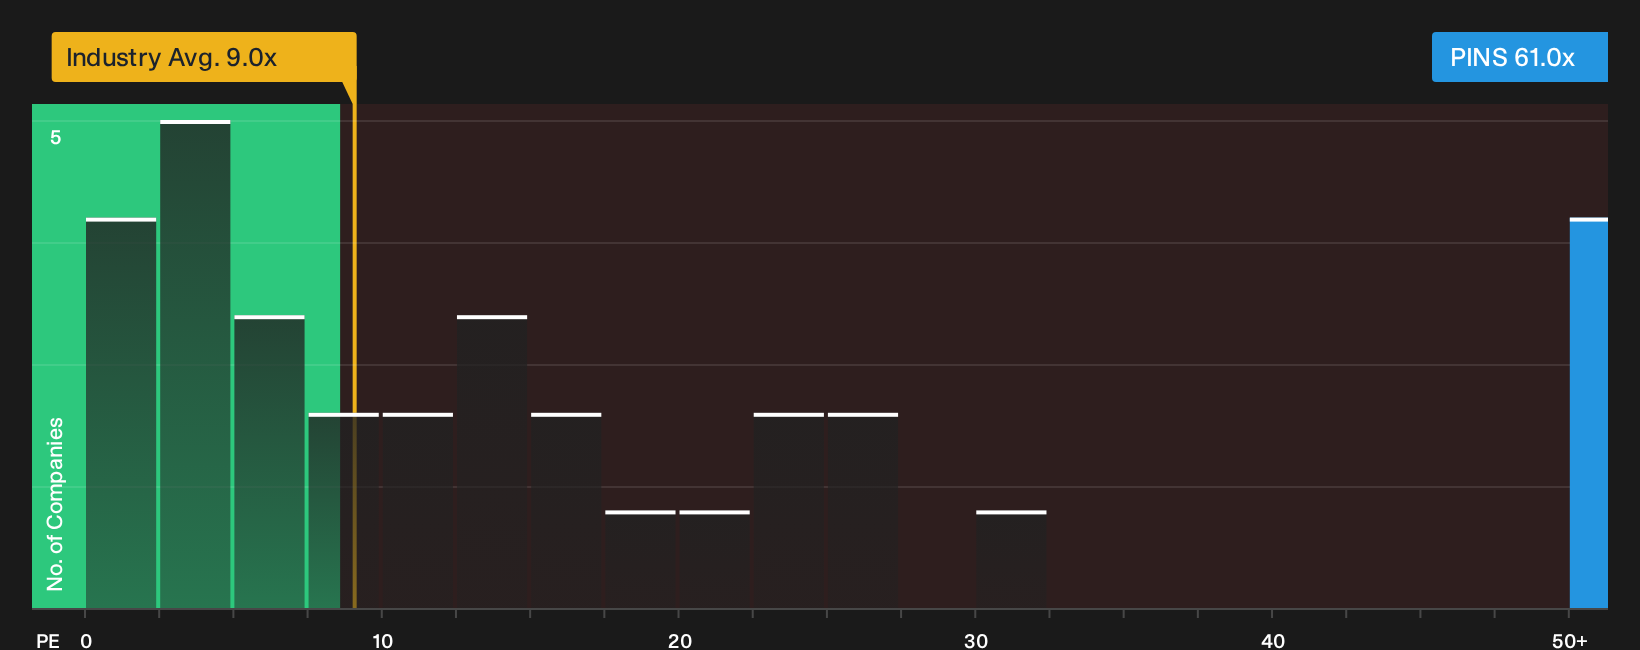
The Pinterest narrative leans on future cash flows and analyst fair value, yet the simple earnings lens paints a tougher picture. PINS trades on a P/E of 61x. Peers in the same industry average 9x, and the fair ratio points to 32.8x. That is a wide gap. Is this a mispricing or just high expectation risk?
Before leaning on any single approach, it helps to stress test the earnings based view against the fuller valuation breakdown, including how that P/E gap could close over time, using the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Pinterest is split right now, which is exactly when it pays to move quickly and test the numbers for yourself. To weigh both the concerns and the brighter spots that investors see today, review the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Pinterest?
Do not stop at Pinterest. The fastest moves often come from places you have not checked yet, and the Screener helps surface those before they are obvious.
- Target resilient payouts by reviewing income focused opportunities through the 7 dividend fortresses that concentrate on higher yields with backing from underlying cash flows.
- Hunt for mispriced quality using the 19 high quality undiscovered gems that filters for strong fundamentals where market attention still looks limited.
- Prioritize capital protection with the 31 resilient stocks with low risk scores that focuses on businesses carrying lower risk scores while still offering meaningful potential.
New: Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com