RBC Bearings has gotten torched over the last six months – since May 2026, its stock price has dropped 22.7% to $474.60 per share. This may have investors wondering how to approach the situation.
Following the pullback, is now an opportune time to buy RBC? Find out in our full research report, it’s free.
Why is RBC a good business?
With a Guinness World Record for engineering the largest spherical plain bearing, RBC Bearings (NYSE:RBC) is a manufacturer of bearings and related components for the aerospace & defense, industrial, and transportation industries.
1. Skyrocketing revenue shows strong momentum
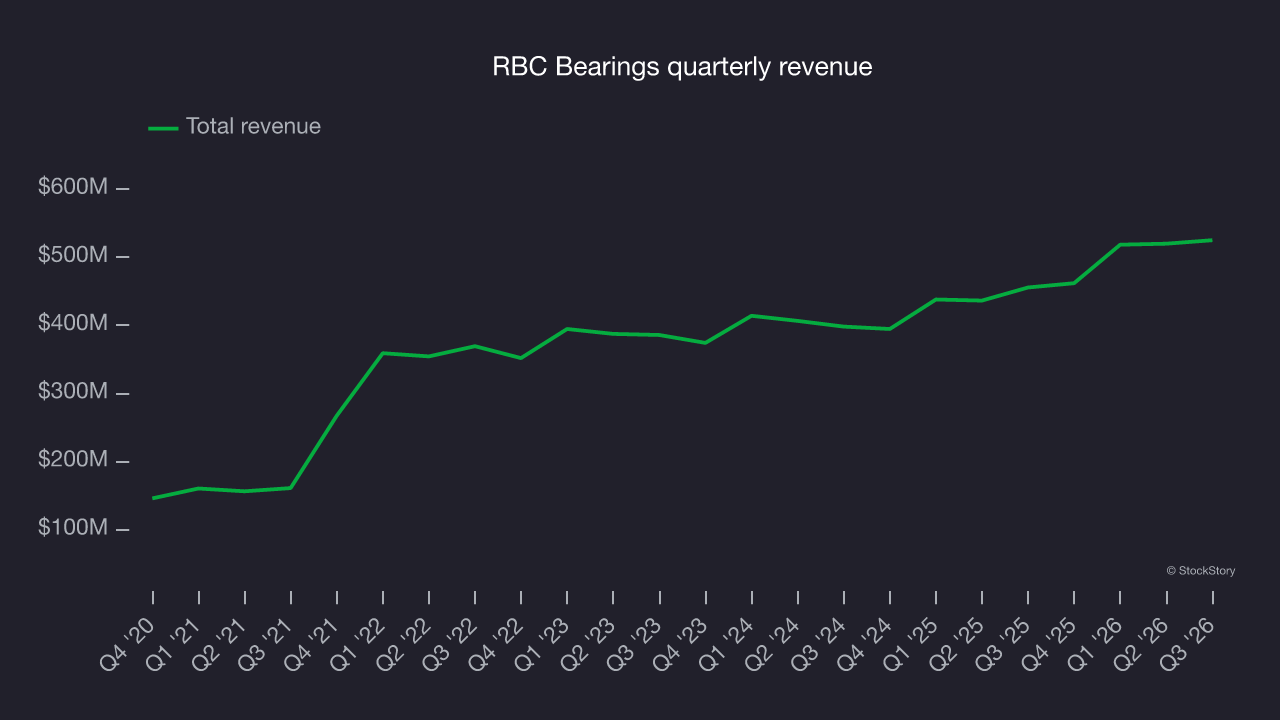
Examining a company’s long-term performance can provide clues about its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Over the last five years, RBC Bearings grew its sales at an exceptional 26.6% compounded annual growth rate. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
2. Outstanding long-term EPS growth
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
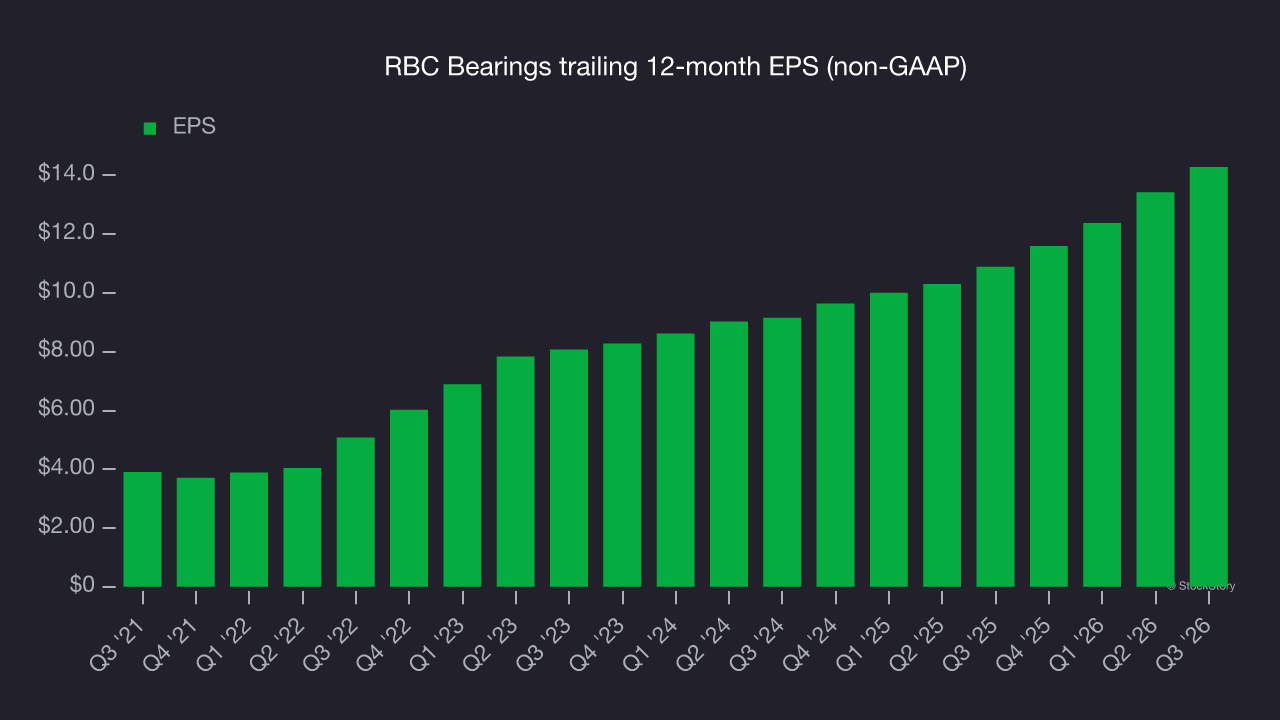
RBC Bearings’s EPS grew at 29.6% compounded annual growth rate over the last five years, higher than its 26.6% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
3. Excellent free cash flow margin boosts reinvestment potential
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
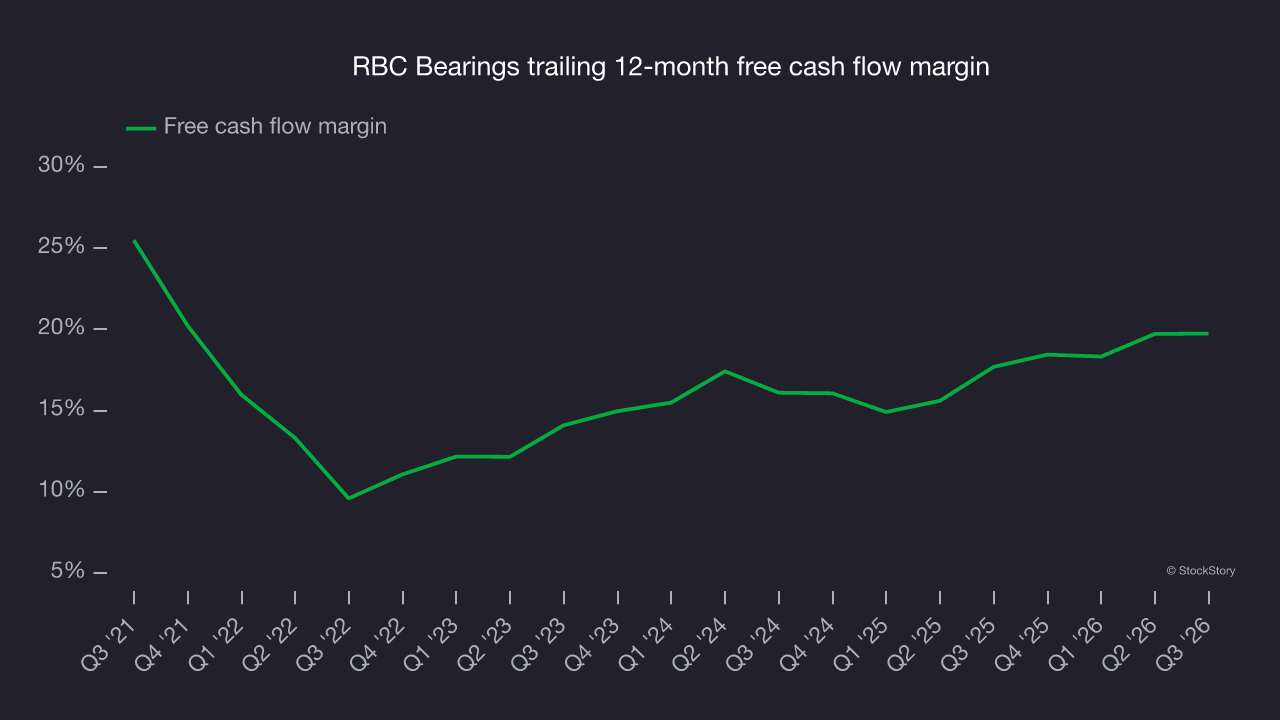
RBC Bearings has shown exceptional cash profitability, putting it in an advantageous position to invest in new products, return capital to investors, and consolidate the market during industry downturns. The company’s free cash flow margin was among the best in the industrials sector, averaging 15.9% over the last five years.
Final judgment
These are just a few reasons RBC Bearings ranks near the top. With the recent decline, the stock trades at 28.7× forward P/E (or $474.60 per share). Is now a good time to initiate a position? See for yourself in our in-depth research report, it’s free.
Stocks we like even more than RBC Bearings
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as less-followed businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.