Attiya Zainib
3 min read
Liontrust Investment Partners recently released its “Global Innovation Fund” Q3 2026 investor letter. A copy of the letter can be downloaded here. The Fund returned -1.6% in the third quarter of 2026, compared with gains of 0.4% for the IA Global sector average and 1.5% for the MSCI AC World Index. Despite the quarterly decline, the Fund returned 19.4% year to date, outperforming both benchmarks and ranking 41st among 576 funds in its sector. The managers attributed the quarter’s volatility to a sharp disconnect between share prices and underlying business performance, particularly across the semiconductor and AI infrastructure industries. Around $3 trillion was wiped from semiconductor market capitalizations in July, even as customers continued making advance payments to secure supply and US companies reported their strongest earnings season in five years. The managers remain constructive on the AI investment cycle, emphasizing the importance of companies supplying computing hardware, power, and infrastructure, while continuing to seek attractive entry points amid higher bond yields and changing market valuations. In addition, please check the Fund’s top five holdings to know its best picks in 2026.
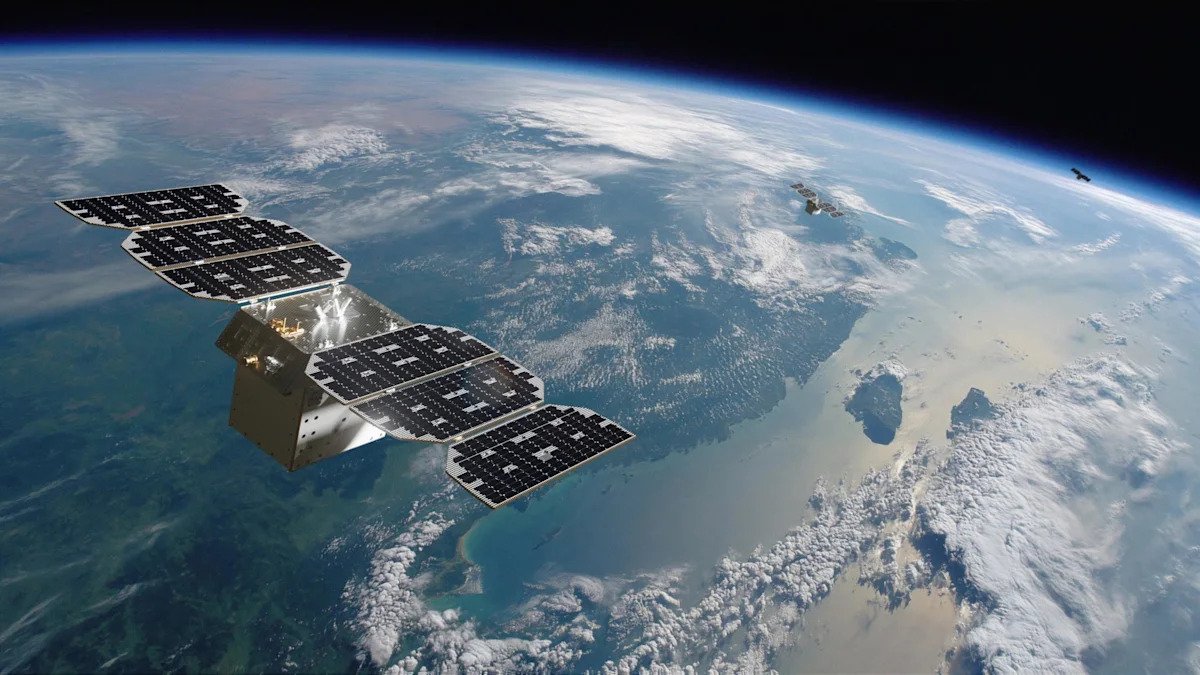
In its third-quarter 2026 investor letter, Liontrust Global Innovation Fund highlighted stocks like Planet Labs PBC (NYSE:PL). Planet Labs PBC (NYSE:PL) operates a constellation of Earth-imaging satellites and provides geospatial data and analytics to customers through an online platform. The one-month return of Planet Labs PBC (NYSE:PL) was -5.21% while its shares traded between $10.52 and $51.76 over the last 52 weeks. On November 9th, 2026, Planet Labs PBC (NYSE:PL) stock closed at approximately $14.37 per share, with a market capitalization of about $5.23 billion.
Liontrust Global Innovation Fund stated the following regarding Planet Labs PBC (NYSE:PL) in its Q3 2026 investor letter:
“Planet Labs PBC (NYSE:PL) (-51%), the satellite imagery company, was the largest detractor among our holdings, costing 0.8 points, and fell despite results that beat expectations. Revenue for its second fiscal quarter rose 58% year-on-year to $116 million, 8.4% ahead of expectations; its identified pipeline for satellite services passed $4 billion; and the US National Geospatial-Intelligence Agency awarded it a monitoring programme without a competing bid. The market focused instead on third quarter revenue guidance below expectations and on the $1.5 billion equity programme announced in June. We judge the moat intact: a decade of calibrated daily imagery of the whole planet cannot be recreated by a new fleet. The watch item is signed demand, with backlog down 10% in the quarter to $815 million as longer dated contracts ran down. We added on weakness; the company now needs to convert its pipeline into signed contracts.”