Eaton (ETN) just landed a fresh aerospace win, supplying hydraulic power and fuel systems for Dassault’s Falcon 10X business jet, shortly after posting third quarter results and outlining new earnings guidance.
Despite the Dassault win and a solid third quarter update, Eaton’s short term trading tone has cooled, with the 30 day share price return down 17.56% and the 90 day move down 22.99%. Even so, the year to date share price return is still up 8.22% and the 3 year total shareholder return sits at 61.05%, suggesting longer term holders have had a much smoother ride than recent buyers.
Capitalize on Eaton’s aerospace momentum and the recent pullback by scanning a curated 41 power grid technology and infrastructure stocks that could benefit from similar demand for electrification and high-reliability power systems.
Eaton shares have retreated sharply even as aerospace wins and new guidance keep hitting the tape. Is this pullback enough of a reset, or does it still make more sense to be patient on the entry price before running the numbers?
Most Popular Narrative: 31.5% Undervalued
On the narrative view, Eaton’s fair value of $517.06 sits well above the last close at $354.22. This puts a spotlight on how much of the “physical AI” story may already be embedded in the price, according to Composite_Research, a Simply Wall St Community investor who built a detailed valuation.
“Eaton Corporation (NYSE: ETN) is one of the rare institutions that has managed to turn the physical constraints of heavy industry and metallurgy to its advantage. Its monopolistic position, benefiting from high material constraints (GOES), years-long delivery times, and in-cabinet thermal densities of 120 kW, along the Voltage Cascades from a 400,000-volt grid to 1 volt on a chip, has provided the company with an unsurpassable economic moat.”
See why 30 investors see Eaton as 31% undervalued.
Result: Fair Value of $517.06 (UNDERVALUED)
Still, Eaton’s story can break if transformer bottlenecks ease faster than expected or if AI data center build plans slow, undercutting the Physical AI premium.
Find out about the key risks to this Eaton narrative.
Another View: What Eaton’s P/E Is Telling You
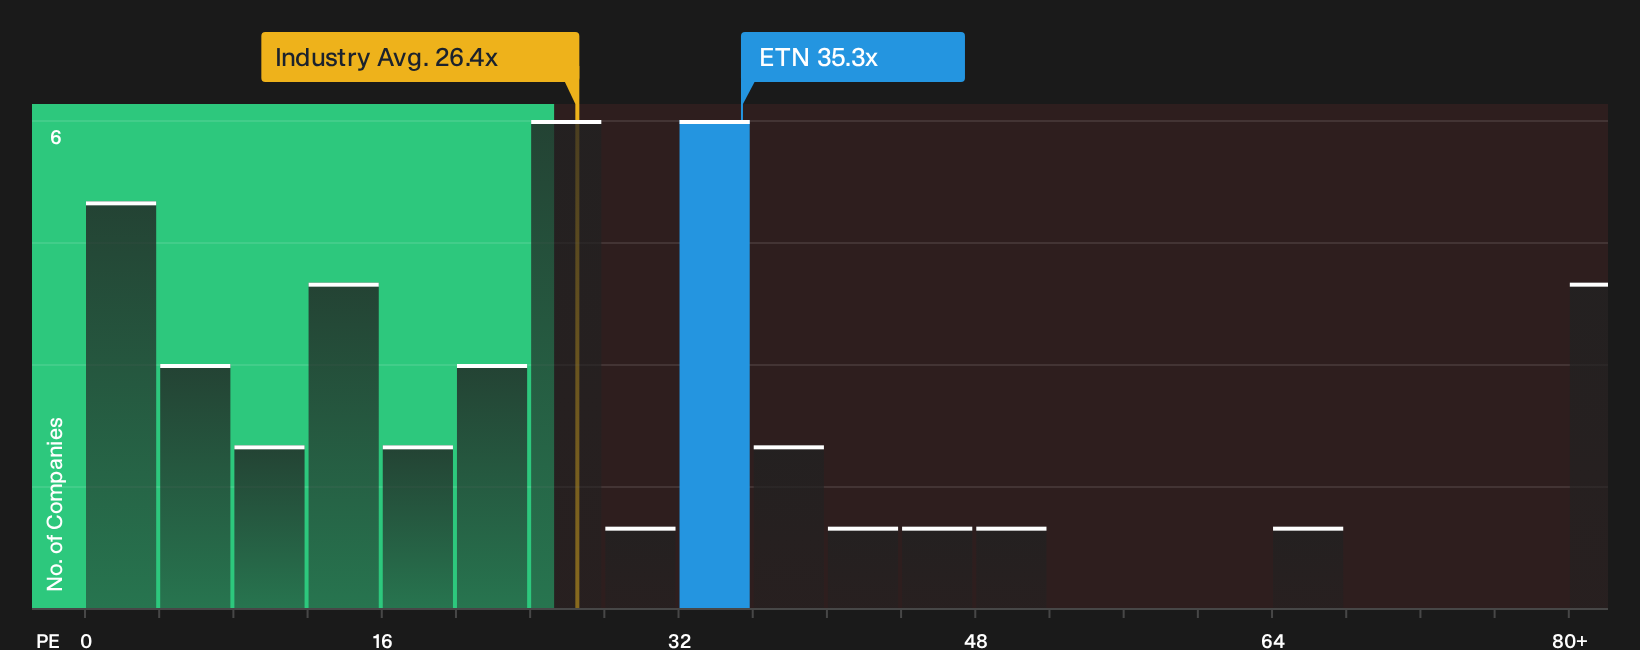
That 31.5% discount to Eaton’s narrative fair value contrasts with a cooler message from plain P/E math. The stock trades on 35.3x earnings, compared with 26.4x for the US Electrical group and 33.8x across peers, while the fair ratio points nearer 38.5x. That gap leaves investors weighing more potential upside against the risk that expectations are already punchy. Which view is closer to how you see Eaton’s pricing power and AI exposure developing?
For a closer look at how these earnings multiples compare with fundamentals and peers, check the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split views on Eaton have you torn, consider acting promptly and testing the narrative against the numbers yourself by weighing the 2 key rewards and 1 important warning sign.
Looking for more Eaton investment ideas?
Do not stop your work with Eaton alone. Broader context helps you spot better risk and reward trade offs, and skipping that step often means leaving opportunities untouched.
- Target mispriced quality by scanning a focused 35 high quality undervalued stocks that highlights businesses with robust fundamentals trading at what may be attractive valuations.
- Prioritize resilience by reviewing a curated 30 resilient stocks with low risk scores featuring companies that score well on financial strength and business risk metrics.
- Hunt for future leaders by checking a 20 high quality undiscovered gems filled with under-the-radar stocks backed by solid balance sheets and cash generation.
Valuation is complex, but we’re here to simplify it.
Discover if Eaton might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com