Fresh analyst coverage has put Viking Holdings (VIK) back in focus, as forecasts point to year-over-year increases in earnings and revenue, alongside firm cruise capacity and occupancy metrics.
Viking Holdings’ recent analyst optimism sits against a mixed tape, with the share price down 1.31% over the last day but higher by 3.16% over the past week and 8.18% over 30 days. The year to date share price return of 22.98% and 1-year total shareholder return of 49.33% point to momentum that has cooled in the last 3 months, as the stock declined 9.30% on a 90-day share price basis from a latest close of $88.88.
Scan beyond Viking Holdings and line up other travel and consumer names showing strong technical setups and earnings momentum using our hand picked 20 high quality undiscovered gems list.
After a sharp run over the past year and a pullback over the last quarter, Viking Holdings sits in a grey zone for investors weighing a fresh entry versus waiting for a deeper reset. The key question is whether the current valuation already captures the optimism around earnings and revenue forecasts, or if there is still a margin of safety on offer.
Most Popular Narrative: 19% Undervalued
The analyst consensus Narrative on Simply Wall St pegs Viking Holdings’ fair value at $109.23, which sits above the latest close of $88.88 and frames the fresh analyst coverage against a discounted entry point built on detailed capacity and earnings assumptions.
Broad-based capacity expansion into new geographies such as India and Egypt, together with further penetration of Viking Holdings in the U.S. source market, remains underway and is supported by committed ship spending of about $1.9b gross in 2026 and $1.0b gross in 2027. This can add to future revenue and earnings as new vessels enter service.
See why 10 investors see Viking Holdings as 19% undervalued.
That fair value hinges on analysts modelling revenue growth of 15.9% a year and profit margins rising from 19.3% to 23.1%, discounted back at 9.07% to reflect the risk profile of Viking Holdings’ cruise focused cash flows.
The same Narrative builds in earnings reaching $2.5b and earnings per share of $5.94 by around November 2029, alongside a future P/E of 25.8x that sits above the current 20.8x P/E for the wider US Hospitality group. This implies investors would still be paying a premium for the brand and booking visibility if those numbers play out.
On price targets alone, the story is similar, with analysts in good agreement that the stock could rise about 21.9% from here and a consensus target of $109.23 that matches the fair value estimate, although individual views still range from $82.00 to $131.00.
Result: Fair Value of $109.23 (UNDERVALUED)
Still, the Viking Holdings story can be knocked off course if affluent, older travelers pull back on big ticket trips, or if weather and geopolitical shocks keep disrupting key river and Egypt routes.
Find out about the key risks to this Viking Holdings narrative.
Another View: Viking Holdings Through The P/E Lens
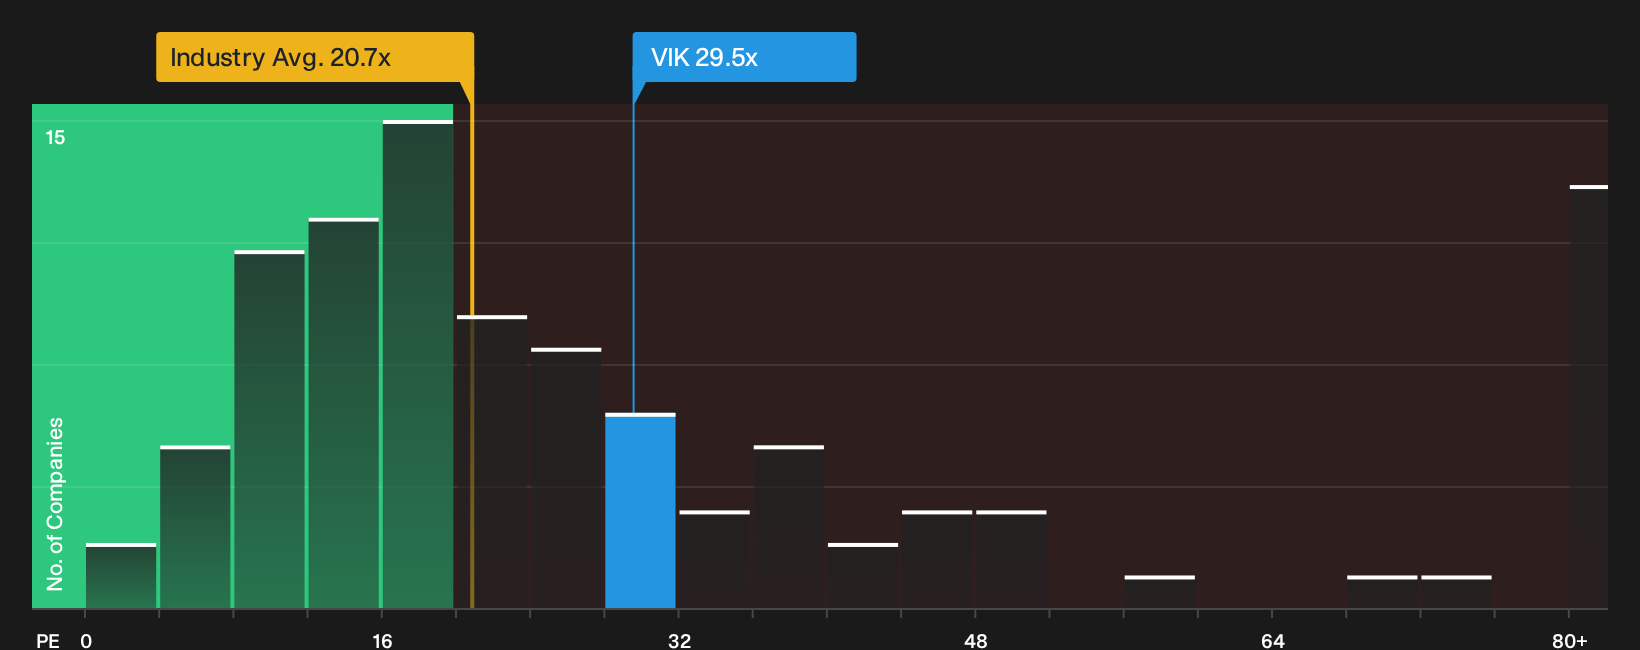
Look past the cash flow models and Viking Holdings screens as expensive on headline valuation. The stock trades on a 29.5x P/E, well above the US Hospitality group at 20.7x and far ahead of peer averages around 13.4x. Yet it still sits below a fair ratio of 31.8x, which suggests the market could move closer to that level if earnings forecasts prove reliable. Is that a cushion worth leaning on, or a thin margin for error if sentiment cools?
For a closer look at how this earnings multiple stacks up against the industry and where valuation pressure could emerge, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the data or a clear tilt in one direction; either way, this is the moment to move beyond headlines and test Viking Holdings against your own checklist. To weigh up both sides of the story, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Viking Holdings?
If Viking Holdings has sharpened your thinking, do not stop here. Broader opportunities across quality, income, and resilience could round out your watchlist and keep you ahead.
- Target potential mispricings by scanning for quality companies trading below their implied worth through the 32 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses with resilient payouts and higher yields using the 6 dividend fortresses.
- Prioritise capital preservation by focusing on sturdier balance sheets and healthier fundamentals via the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com