Ingredion (INGR) has been back in focus after Avantis U.S. Small Cap Value ETF bought about US$10.7 million of shares, shortly after the company released its third quarter earnings and updated its full year outlook.
The recent buying interest comes against a mixed price backdrop. Ingredion shares trade at US$94.14 after a 7 day share price return of 2.64%. However, the 90 day share price return is down 10.51% and the 1 year total shareholder return is down 9.70%, which suggests momentum has been fading even as some investors reassess the outlook following the latest earnings and guidance update.
Scan for other Ingredion style value plays with fresh institutional interest by checking our curated list of 32 high quality undervalued stocks featuring solid balance sheets and cash flows.
Ingredion looks like a solid, long-established ingredients business, yet the stock has slipped this year even as a value ETF is buying in. Does that combination actually add up to a compelling valuation today?
Most Popular Narrative: 6.7% Overvalued
Ingredion is trading at $94.14 while the most followed narrative on Simply Wall St assigns a fair value of $88.23, which points to a modest premium based on that framework and sets up a debate around how much investors should pay for its transformation story.
The attraction of INGR is not explosive growth. It is:
Durable demand
Strong customer relationships
High ROIC
Consistent free cash flow
Dividend growth
Share repurchases
If INGR compounds earnings around 6 to 8% and returns another 2 to 3% through dividends, a long-term shareholder could reasonably expect 8 to 12% annual returns, which would roughly double capital every 6 to 9 years.
See why 9 investors see Ingredion as 7% overvalued.
Result: Fair Value of $88.23 (OVERVALUED)
Still, Ingredion’s story can break if the Tate & Lyle integration disappoints, or if the higher margin specialty mix fails to offset weakness in legacy starch and sweeteners.
Find out about the key risks to this Ingredion narrative.
Another View: Ingredion Looks Cheap On Earnings
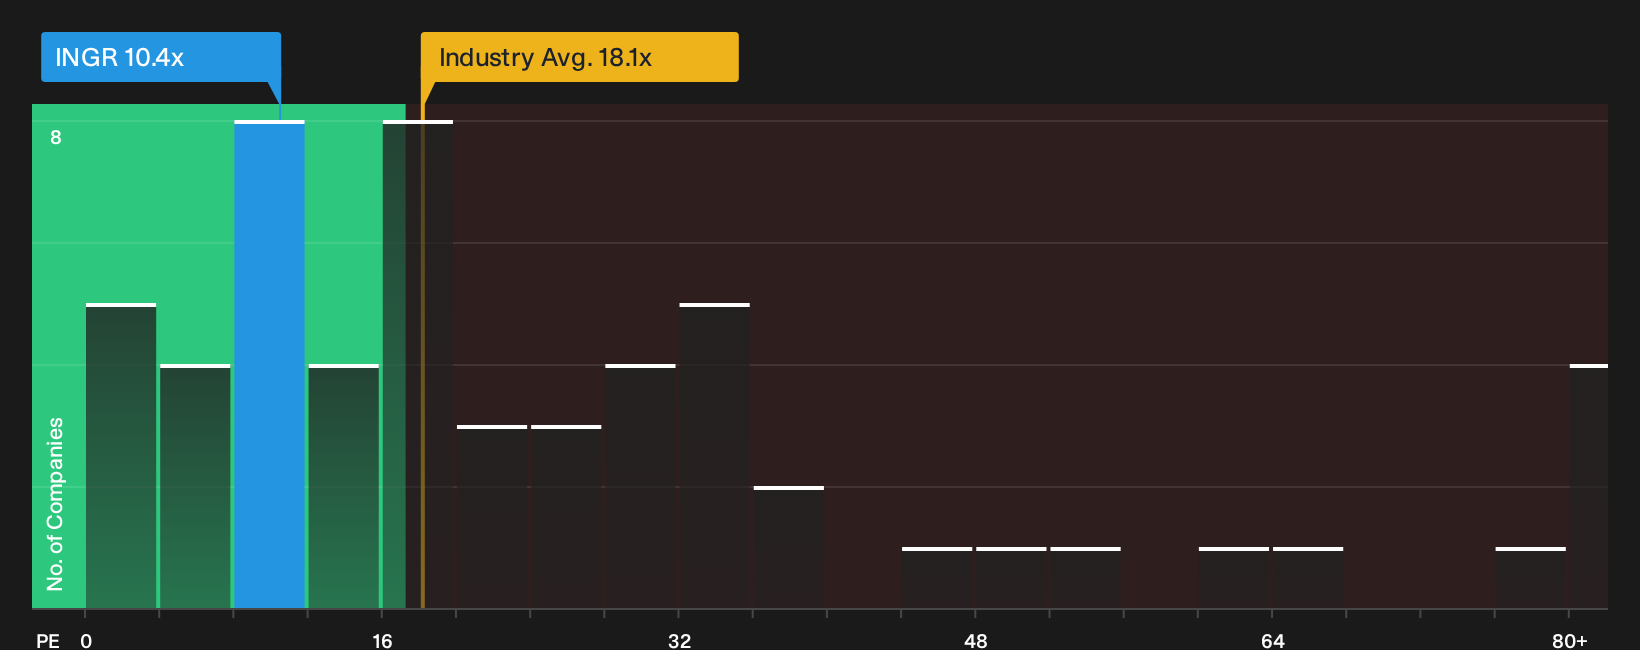
That 6.7% premium to the narrative fair value clashes with what the earnings multiple is saying. At a P/E of 10.4x versus 18.1x for the US Food industry and 14.2x for peers, Ingredion trades at a clear discount even to its own 17.9x fair ratio.
This gap frames the real question for you as an investor. Is the market rightly cautious about Ingredion’s slower forecast growth and recent margin pressure, or has sentiment pushed a solid ingredients business further below what a more typical valuation ratio could move toward over time?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Ingredion is clearly split. This creates a short window for you to weigh the evidence, test the numbers, and decide where you stand. To see what investors are optimistic about, review the 5 key rewards.
Looking for more investment ideas beyond Ingredion?
Use the edge you have now and line up your next moves with a few focused stock ideas that match your risk and income preferences.
- Target cash-flow strength and potential mispricing by scanning a curated pool of value opportunities using the 32 high quality undervalued stocks.
- Lock in more reliable income streams by zeroing in on companies that feature the 6 dividend fortresses.
- Dial back volatility in your portfolio by focusing on resilient businesses identified in our 31 resilient stocks with low risk scores.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com