Warren Buffett put it simply: “Whether we’re talking about socks or stocks, I like buying quality merchandise when it is marked down.”
But markdowns in stocks usually don’t feel as good as buying socks. The question is whether the business has permanently weakened or is just experiencing a short-term hiccup in growth.
Missed AI’s “Act 1”? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
On Holding (NYSE:ONON), the Swiss maker of premium running shoes and apparel, and Dutch Bros (NYSE:BROS), the drive-thru coffee chain, are both down more than 20%. Here’s what the market may be missing.
Image source: Getty Images.
On Holding: Customers keep paying full price
On shares fell 7.5% on Nov. 10 after third-quarter results and are now down 24% year to date. Constant-currency sales grew 17.8% over the year-ago quarter, which looks solid but is pacing below the company’s full-year low 20% outlook.
Importantly, the Swiss footwear brand is getting stronger. Sales hit a record, and gross margin reached 66.9% excluding tariff refunds, the highest in company history.
Management credits its Premium Playbook — innovative products that customers buy at full price, with no discounts. “In a promotional market, we stayed true to who we are and held full price,” Co-CEO Caspar Coppetti said. On’s average footwear price has climbed from $145 to $170 in five years, with demand growing.
Premium sportswear is worth 125 billion Swiss francs ($152 billion) and growing twice as fast as the overall industry, management says. On’s brand awareness is over 30% — the global share of consumers that know the brand — with management targeting 50%. It should appeal to more customers as it expands into football and golf gear next year.
The stock trades at a forward price-to-earnings (P/E) multiple of about 17 on fiscal 2027 estimates. That looks attractive with analysts expecting 25% annualized earnings growth in the next several years. At this valuation, the stock should deliver excellent returns over the next decade.
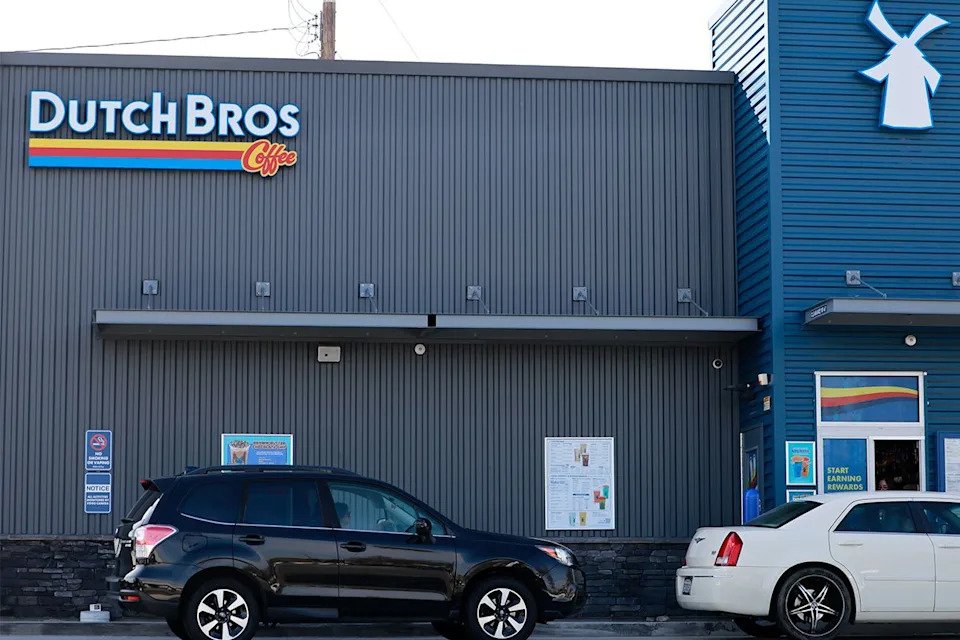
Image source: Getty Images.
Dutch Bros: The window is the moat
Dutch Bros shares are down 43% this year through Nov. 10, hitting a 52-week low on Nov. 6 as the drive-thru beverage chain continues to navigate a volatile consumer spending environment. Yet Q3 revenue still looked strong overall, growing 30% year over year to $550 million.