TipRanks
4 min read
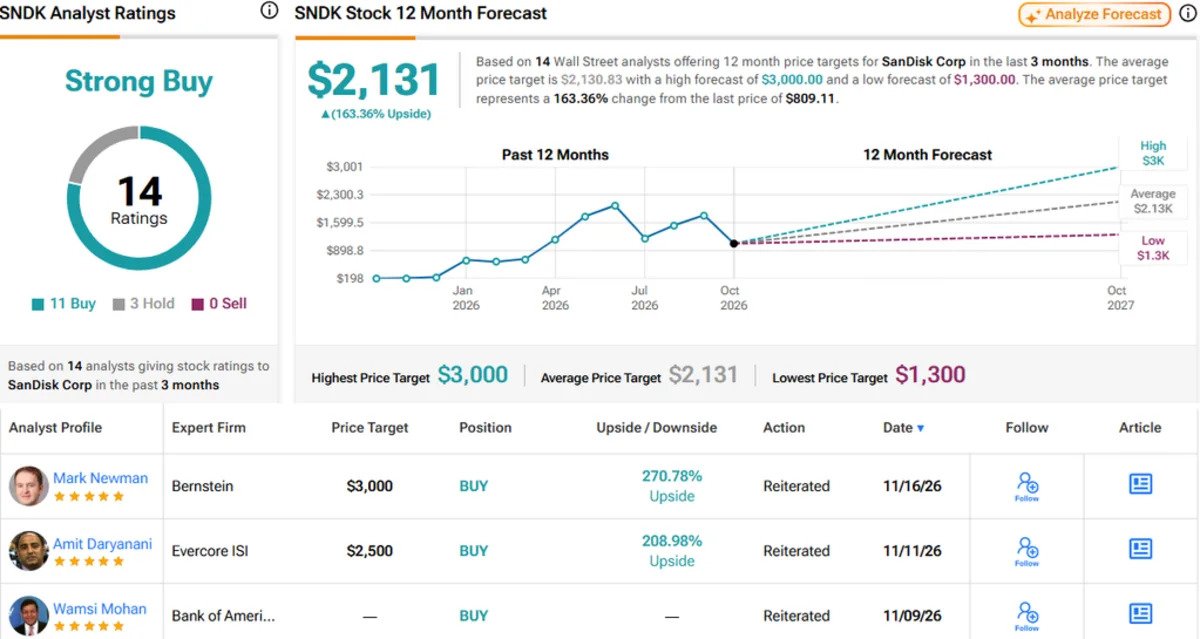
Sandisk (NASDAQ:SNDK) is selling flash memory to AI data centers about as fast as it can make it, but that has done little for investors’ morale recently. The stock keeps falling anyway, with shares drifting lower since their late-June peak.
The past couple of weeks have made things worse. AI stocks dropped after the Democrats’ midterm sweep raised fears that tighter rules could slow data center construction, and then fell again when Jensen Huang resigned as Nvidia’s CEO on Nov. 12. Monday was the third losing day in a row, and traders are now waiting for Nvidia’s quarterly report after the bell today.
The stock currently sits about 65% below its June record. That’s just days before Sandisk’s 8-for-1 stock split takes effect on Nov. 20.
Promotion
BLACK FRIDAY SALE
-
Get 75% Off TipRanks Premium and unlock powerful investing tools to make smarter, more confident investment decisions
-
Subscribe to TipRanks Smart Investor Newsletter, and discover new investing opportunities with data-backed stock picks
Learn more about TipRanks Premium
The problem, says investor Infinity Curve (IC), has less to do with the company and more to do with the market still treating Sandisk like the old boom-and-bust memory maker and missing how much the business has changed. In fiscal Q1 2027, revenue jumped 378% year over year to $11 billion, and non-GAAP gross margin came in at 85.1%. Management expects $12.2 billion to $12.6 billion in revenue this quarter.
IC accepts that margins like that won’t last forever. Still, management said about 60% of the sequential sales jump came from higher volume rather than higher prices. The investor sees that as a sign of real demand. Data centers drive most of it. That segment’s revenue rose 61% from the prior quarter to $4.8 billion, and exabytes shipped grew about 330% YoY.
IC argues that AI inference needs more storage than DRAM or HBM can supply at a sensible cost. Larger context windows and more complex agentic tools are two reasons. IC gives little weight to Sandisk’s high-bandwidth flash plans and bases the thesis on products already on the market.
The investor’s biggest reason for optimism is the contract book. Sandisk has $88.9 billion in remaining performance obligations (RPOs), mostly from multiyear supply deals that cover about half of fiscal 2027 bits and two-thirds of fiscal 2028 bits. About 95% of those customers are investment grade, and many have put up collateral. IC is careful here. The deals don’t fix margins and only partly protect Sandisk, so the cycle hasn’t gone away. Even so, keeping a bit more profit in a downturn could justify a much higher valuation.