The overall market has done well over the last few years. Using the popular S&P 500 index as a proxy, large-cap stocks gained 61.5% over the last five years through Nov. 13.
Missed AI’s “Act 1”? Act 2 Could Be 16x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
That’s been positive for many, but certainly not all, stocks. Naturally, there have been laggards.
Nike (NYSE: NKE) has been one. The shares are about 78% off the high price during this period. Here’s a look at the sell-off and the dividend yield to see whether or not you should buy the stock.
The stock’s sell-off
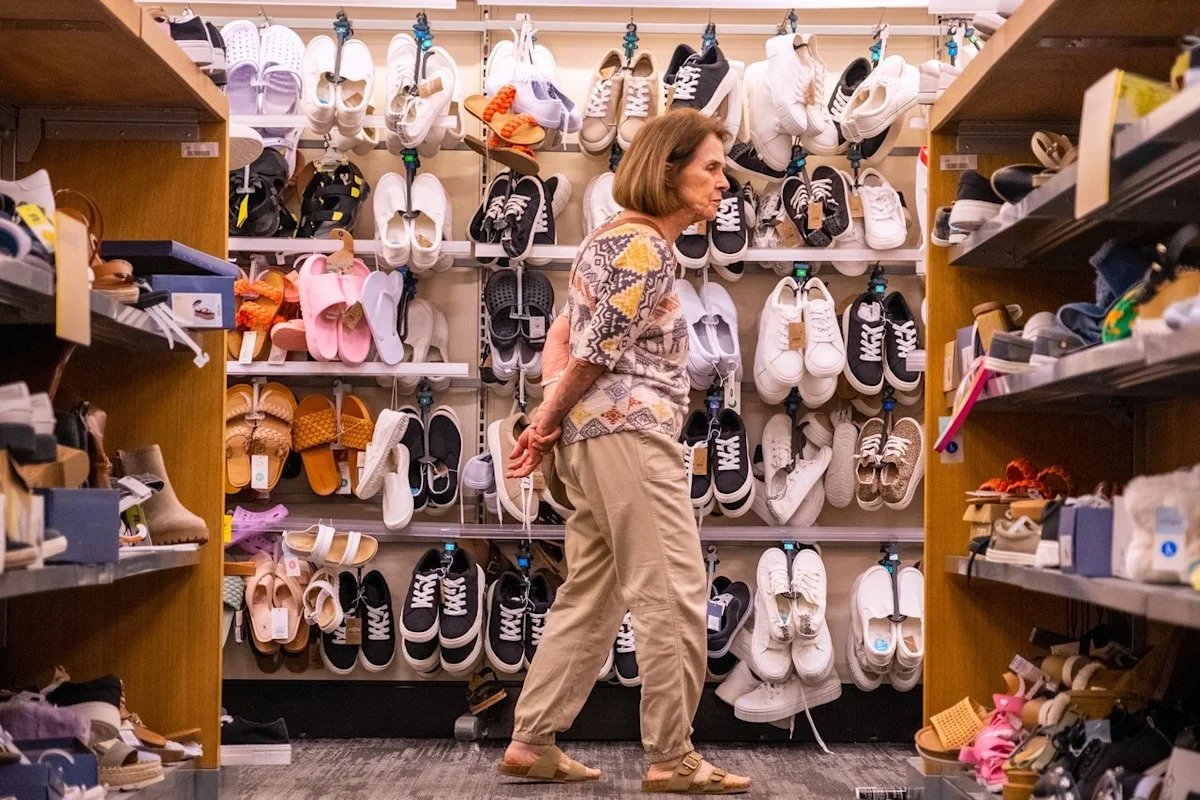
This long-heralded company had big marketing budgets, famous commercials, multiple sports stars’ endorsements, and growing sales. Investors did well by owning Nike’s stock. However, over the last few years, a lack of product innovation, competition, and management missteps have led to sagging sales.
They don’t look set to improve anytime soon, either. Nike’s fiscal first-quarter revenue, adjusted to remove foreign-currency translations, dropped 5% year over year. The period ended on Aug. 31. Management forecasts revenue will fall by a high-single-digit percentage for the year.
With revenue persistently declining, it’s no wonder the share price has dropped precipitously. Given the company’s outlook, that doesn’t look like it’s going to reverse, at least not anytime soon.
Should the yield entice you?
Despite the company’s struggles, Nike’s board of directors has consistently raised dividends. In fact, the company has increased dividends annually for about a quarter of a century.
The lower stock price translates into a higher dividend yield. That’s because you calculate a stock’s yield by dividing the annual dividend by the share price. Hence, if a dividend stays constant or increases, the stock’s yield rises.
Presently, Nike’s shares yield 4.3%. That seems attractive, given that the S&P 500 yields 1.1%.
However, with weaker results, the company’s operating cash flow has dropped over the past several years. Nike’s fiscal 2026 operating cash flow fell from $3.7 billion to $2.9 billion. After subtracting $686 million for capital expenditures, it produced free cash flow (FCF) of $2.2 billion. This didn’t cover the $2.4 billion of common and preferred stock dividends.
You can also look at dividends compared to earnings, called the payout ratio. Presently, Nike has a payout ratio of 79%.