Over the past six months, Procore Technologies has been a great trade, beating the S&P 500 by 7.5%. Its stock price has climbed to $62.26, representing a healthy 16.6% increase. This was partly due to its solid quarterly results, and the performance may have investors wondering how to approach the situation.
Is there a buying opportunity in Procore Technologies, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why is Procore Technologies not exciting?
Despite the momentum, we’re passing on Procore Technologies for now. Here are two reasons you should be careful with PCOR, plus one stock we’d rather own.
1. Projected revenue growth is slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Procore Technologies’s revenue to rise by 13.4%, a slight deceleration versus its 26% annualized growth for the past five years. This projection is underwhelming and suggests its products and services will see some demand headwinds.
2. Operating losses sound the alarm
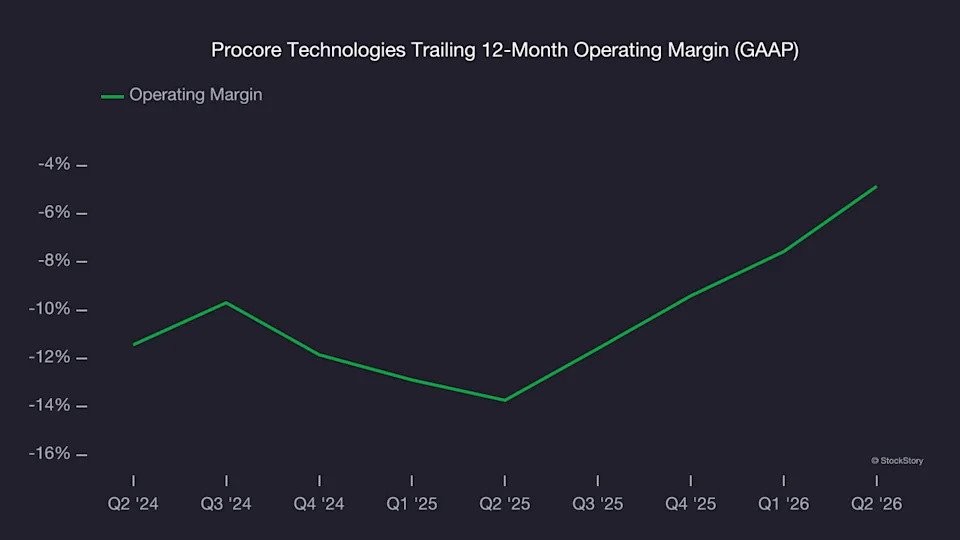
While many software businesses point investors to their adjusted profits, which exclude stock-based compensation (SBC), we prefer GAAP operating margin because SBC is a legitimate expense used to attract and retain talent. This metric shows how much revenue remains after accounting for all core expenses — everything from the cost of goods sold to sales and R&D.
Although Procore Technologies was profitable this quarter from an operational perspective, it’s generally struggled over a longer time period. Its expensive cost structure has contributed to an average operating margin of negative 4.9% over the last year. Unprofitable, high-growth software companies require extra attention because they spend heaps of money to capture market share. As seen in its fast historical revenue growth, this strategy seems to have worked so far, but it’s unclear what would happen if Procore Technologies reeled back its investments. Wall Street seems to think it will face some obstacles, and we tend to agree.
Final judgment
Procore Technologies isn’t a terrible business, but it doesn’t pass our bar. With its shares outperforming the market lately, the stock trades at 5.8× forward price-to-sales (or $62.26 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re fairly confident there are better investments elsewhere. Let us point you toward one of our all-time favorite software stocks.