Lennar has been treading water for the past six months, recording a small loss of 3.1% while holding steady at $82.27. The stock also fell short of the S&P 500’s 21.4% gain during that period.
Is now the time to buy Lennar, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Do We Think Lennar Will Underperform?
We’re passing on Lennar for now. Here are three reasons why LEN doesn’t excite us, plus one stock we’d rather own.
1. Backlog Declines as Orders Drop
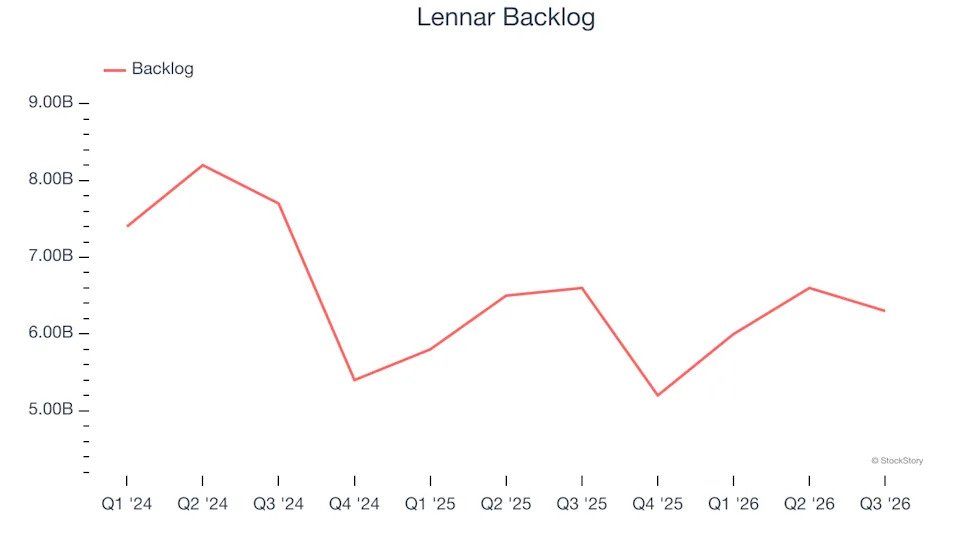
We can better understand Home Builders companies by analyzing their backlog. This metric shows the value of outstanding orders that have not yet been executed or delivered, giving visibility into Lennar’s future revenue streams.
Lennar’s backlog came in at $6.3 billion in the latest quarter, and it averaged 8.6% year-on-year declines over the last two years. This performance was underwhelming and shows the company is not winning new orders. It also suggests there may be increasing competition or market saturation.
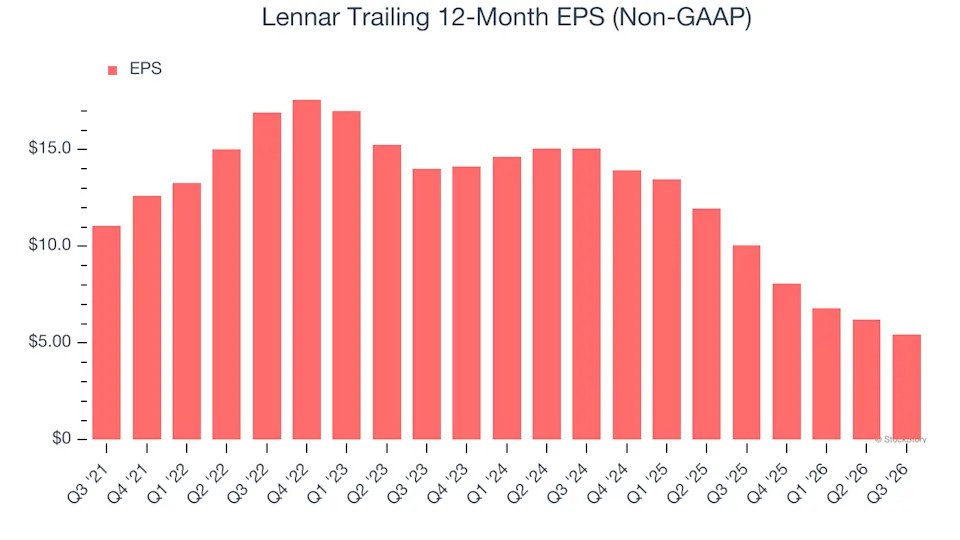
2. EPS Trending Down
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Sadly for Lennar, its EPS declined by 13.2% annually over the last five years while its revenue grew by 4.6%. This tells us the company became less profitable on a per-share basis as it expanded.
3. New Investments Fail to Bear Fruit as ROIC Declines
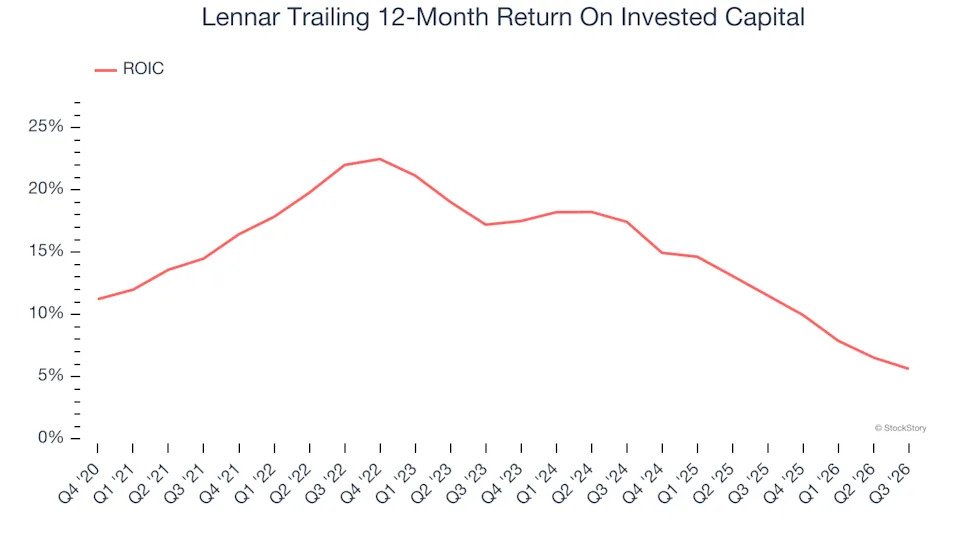
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Unfortunately, Lennar’s ROIC has decreased significantly over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Lennar doesn’t pass our quality test. With its shares trailing the market in recent months, the stock trades at 17.2× forward P/E (or $82.27 per share). At this valuation, there’s a lot of good news priced in – we think there are better stocks to buy right now. We’d suggest looking at the Amazon and PayPal of Latin America.
Stocks We Would Buy Instead of Lennar
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.