Over the past six months, Target Hospitality’s stock price fell to $13.61. Shareholders have lost 10.2% of their capital, which is disappointing considering the S&P 500 has climbed by 5.3%. This might have investors contemplating their next move.
Is there a buying opportunity in Target Hospitality, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why do we think Target Hospitality will underperform?
Even though the stock has become cheaper, we’re cautious about Target Hospitality. Here are three reasons we avoid TH, plus one stock we’d rather own.
1. Decline in utilized beds points to weak demand
Revenue growth can be broken down into changes in price and volume (for companies like Target Hospitality, our preferred volume metric is utilized beds). While both are important, the latter is the most critical to analyze because prices have a ceiling.
Target Hospitality’s utilized beds came in at 11,760 in the latest quarter, and over the last two years, averaged 15.3% year-on-year declines. This performance was underwhelming and implies there may be increasing competition or market saturation. It also suggests Target Hospitality might have to lower prices or invest in product improvements to grow, factors that can hinder near-term profitability. 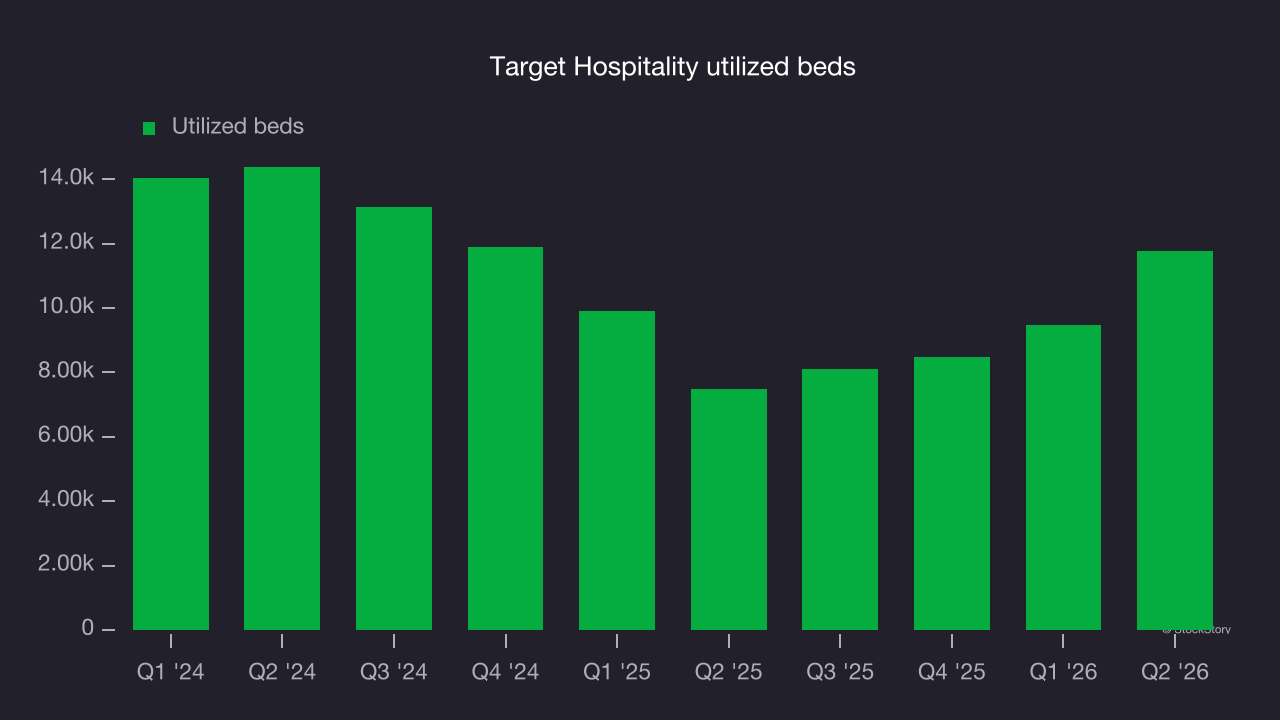
2. Mediocre free cash flow margin limits reinvestment potential
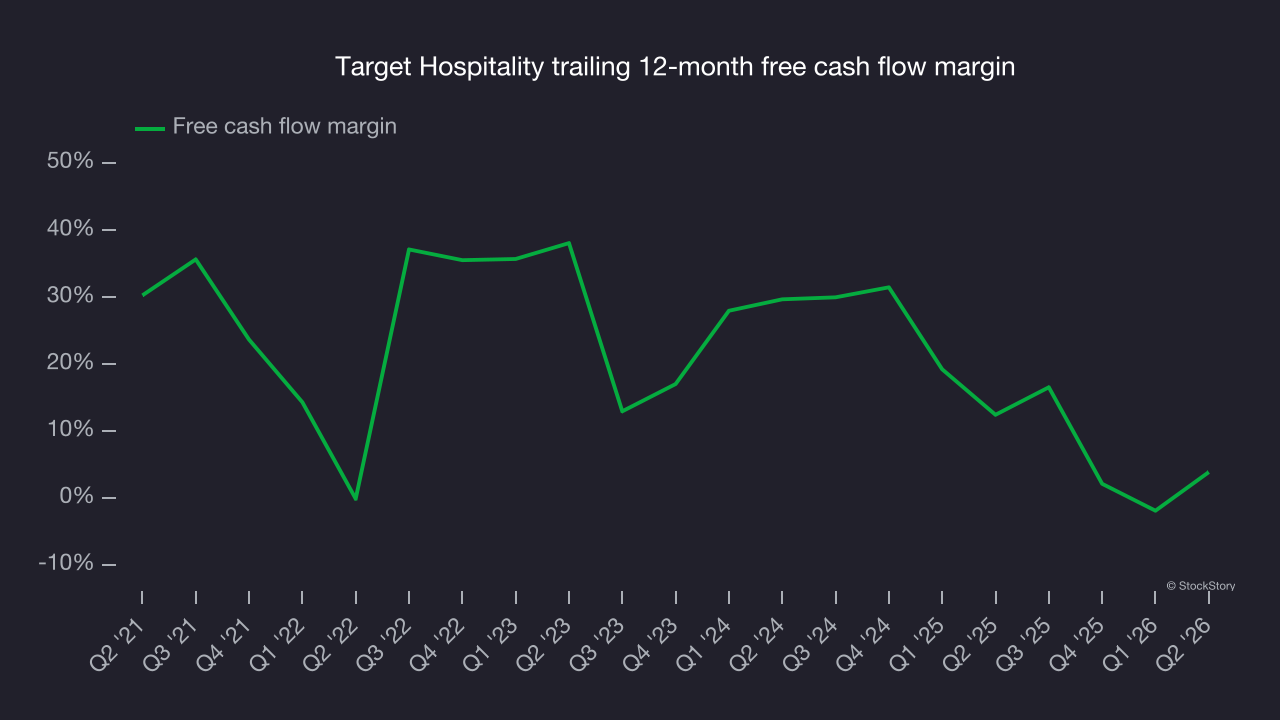
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
Target Hospitality has shown poor cash profitability relative to peers over the last two years, giving the company fewer opportunities to return capital to shareholders. Its free cash flow margin averaged 7.9%, below what we’d expect for a consumer discretionary business.
3. New investments fail to bear fruit as ROIC declines
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Over the last few years, Target Hospitality’s ROIC has unfortunately decreased significantly. Paired with its already low returns, these declines suggest its profitable growth opportunities are few and far between.
Final judgment
We cheer for all companies serving everyday consumers, but in the case of Target Hospitality, we’ll be cheering from the sidelines. After the recent drawdown, the stock trades at 26.9× forward P/E (or $13.61 per share). This valuation is reasonable, but the company’s shaky fundamentals present too much downside risk. There are superior stocks to buy right now. Let us point you toward the Amazon and PayPal of Latin America.
Stocks we would buy instead of Target Hospitality
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.