Over the past six months, Meritage Homes’s stock price fell to $58.81. Shareholders have lost 11.4% of their capital, which is disappointing considering the S&P 500 has climbed by 12.8%. This might have investors contemplating their next move.
Is now the time to buy Meritage Homes, or should you be careful about including it in your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Do We Think Meritage Homes Will Underperform?
Even with the cheaper entry price, we don’t have much confidence in Meritage Homes. Here are three reasons why MTH doesn’t excite us, plus one stock we’d rather own.
1. Backlog Declines as Orders Drop
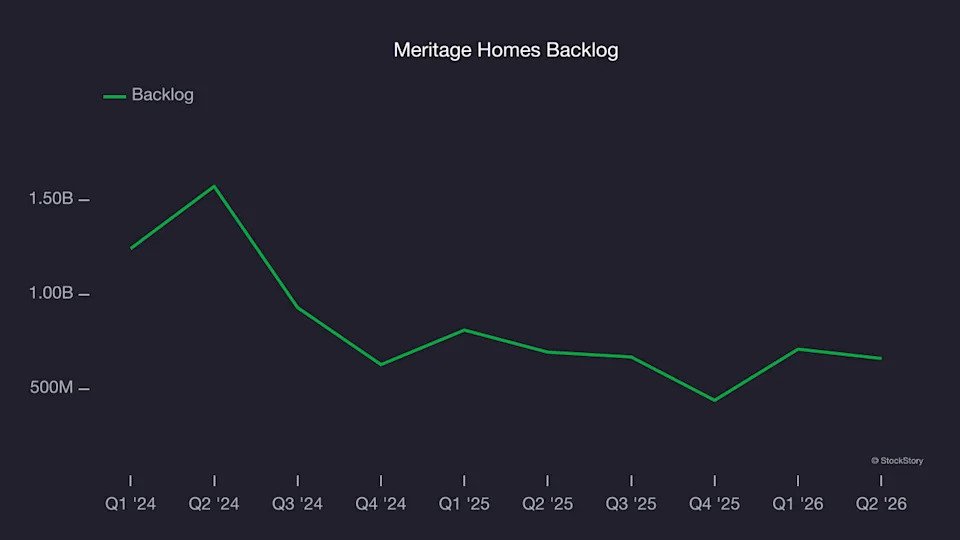
In addition to reported revenue, backlog is a useful data point for analyzing Home Builders companies. This metric shows the value of outstanding orders that have not yet been executed or delivered, giving visibility into Meritage Homes’s future revenue streams.
Meritage Homes’s backlog came in at $661.9 million in the latest quarter, and it averaged 27.6% year-on-year declines over the last two years. This performance was underwhelming and shows the company is not winning new orders. It also suggests there may be increasing competition or market saturation.
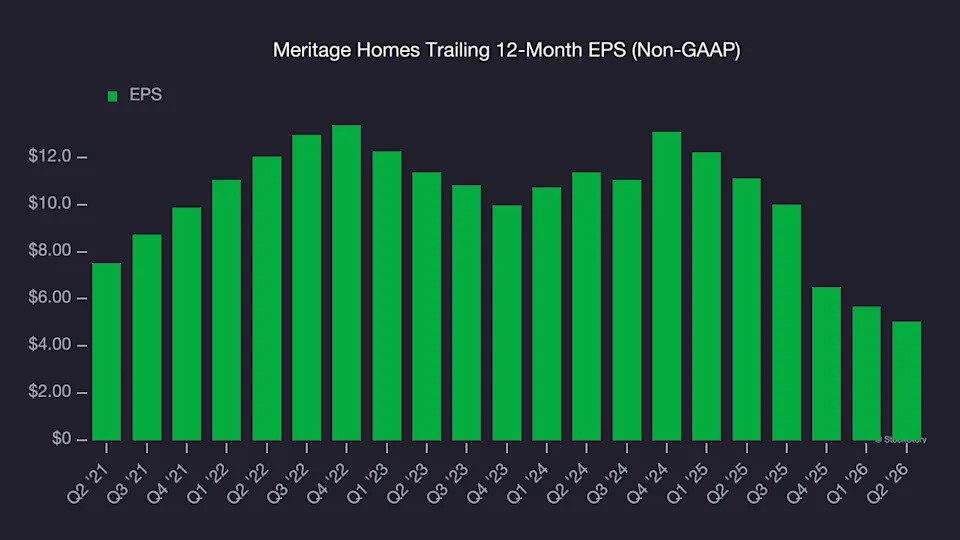
2. EPS Trending Down
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for Meritage Homes, its EPS declined by 7.7% annually over the last five years while its revenue grew by 1.8%. This tells us the company became less profitable on a per-share basis as it expanded.
3. New Investments Fail to Bear Fruit as ROIC Declines
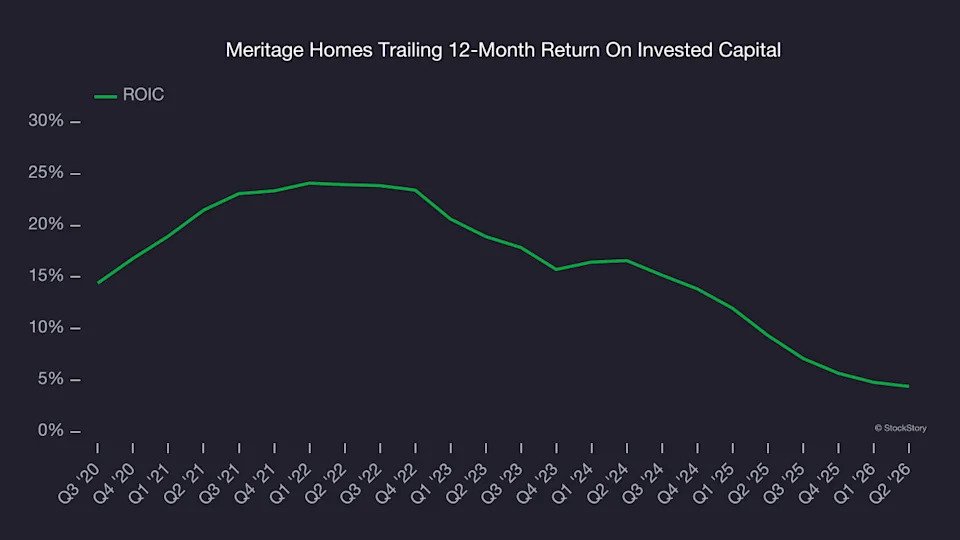
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Unfortunately, Meritage Homes’s ROIC has decreased significantly over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Meritage Homes doesn’t pass our quality test. After the recent drawdown, the stock trades at 11.8× forward P/E (or $58.81 per share). While this valuation is reasonable, we don’t see a big opportunity at the moment. There are better investments elsewhere. We’d suggest looking at one of our top software and edge computing picks.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.