Estée Lauder has been on fire lately. In the past six months alone, the company’s stock price has rocketed 40%, reaching $108.25 per share. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is there a buying opportunity in Estée Lauder, or does it present a risk to your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why is Estée Lauder not exciting?
Despite the momentum, we’re passing on Estée Lauder for now. Here are three reasons you should be careful with EL, plus one stock we’d rather own.
1. Core business falling behind as organic sales decline
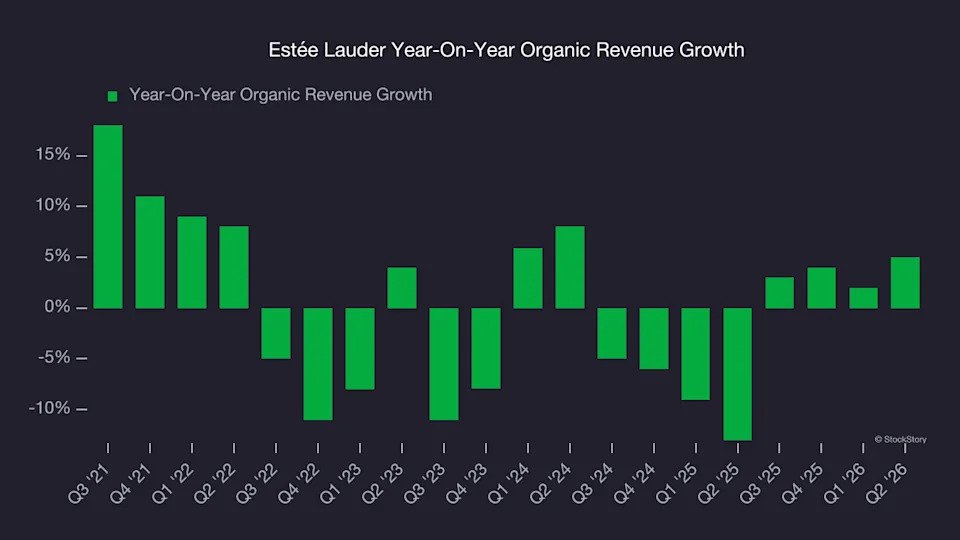
When analyzing revenue growth, we care most about organic revenue growth. This metric captures a business’s performance excluding one-time events such as mergers, acquisitions, and divestitures as well as foreign currency fluctuations.
Estée Lauder’s demand has been falling over the last eight quarters, and on average, its organic sales have declined by 2.4% year on year.
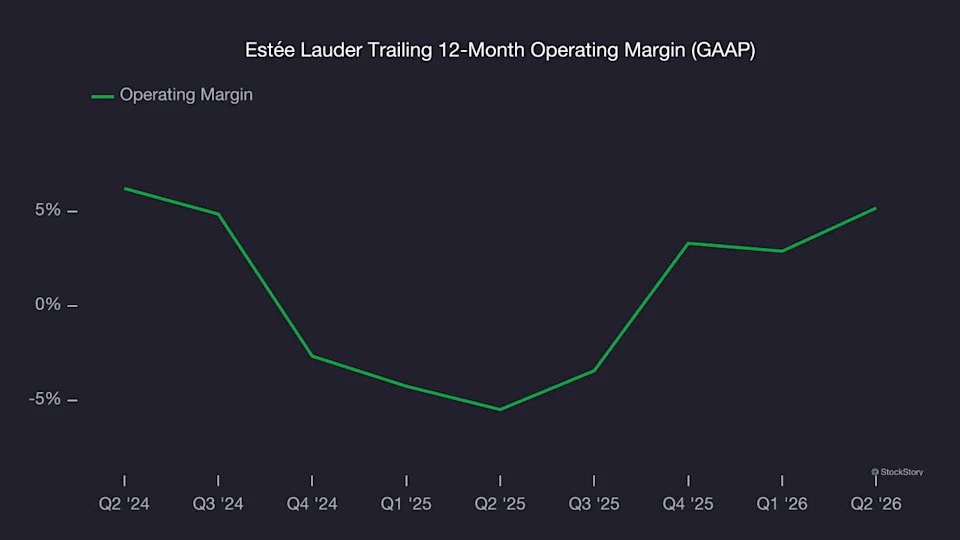
2. Breakeven operating margin raises questions
Operating margin is a key measure of profitability. Think of it as net income – the bottom line – excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Estée Lauder was roughly breakeven when averaging the last two years of quarterly operating profits, lousy for a consumer staples business. This result is surprising given its high gross margin as a starting point.
3. EPS trending down
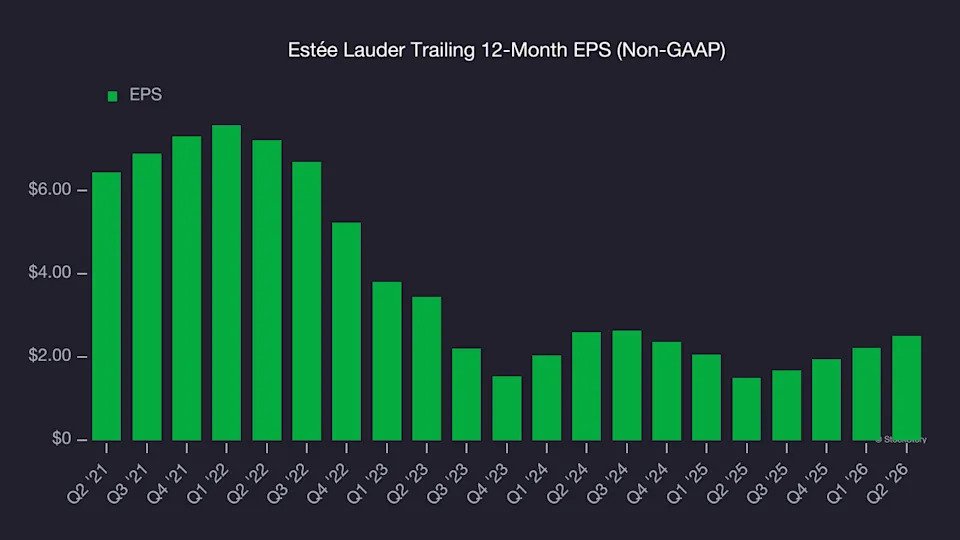
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for Estée Lauder, its EPS declined by 10.1% annually over the last three years, more than its revenue. This tells us the company struggled because its fixed cost base made it difficult to adjust to shrinking demand.
Final judgment
Estée Lauder isn’t a terrible business, but it isn’t one of our picks. Following the recent surge, the stock trades at 32.4× forward P/E (or $108.25 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in – we think there are better stocks to buy right now. We’d recommend looking at the most entrenched endpoint security platform on the market.
Stocks we would buy instead of Estée Lauder
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.