Walmart currently trades at $127.09 per share and has shown little upside over the past six months, posting a small loss of 2.3%. The stock also fell short of the S&P 500’s 4.5% gain during that period.
Is there a buying opportunity in Walmart, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why is Walmart not exciting?
We don’t have much confidence in Walmart. Here are three reasons why there are better opportunities than WMT, plus one stock we’d rather own.
1. Long-term revenue growth disappoints
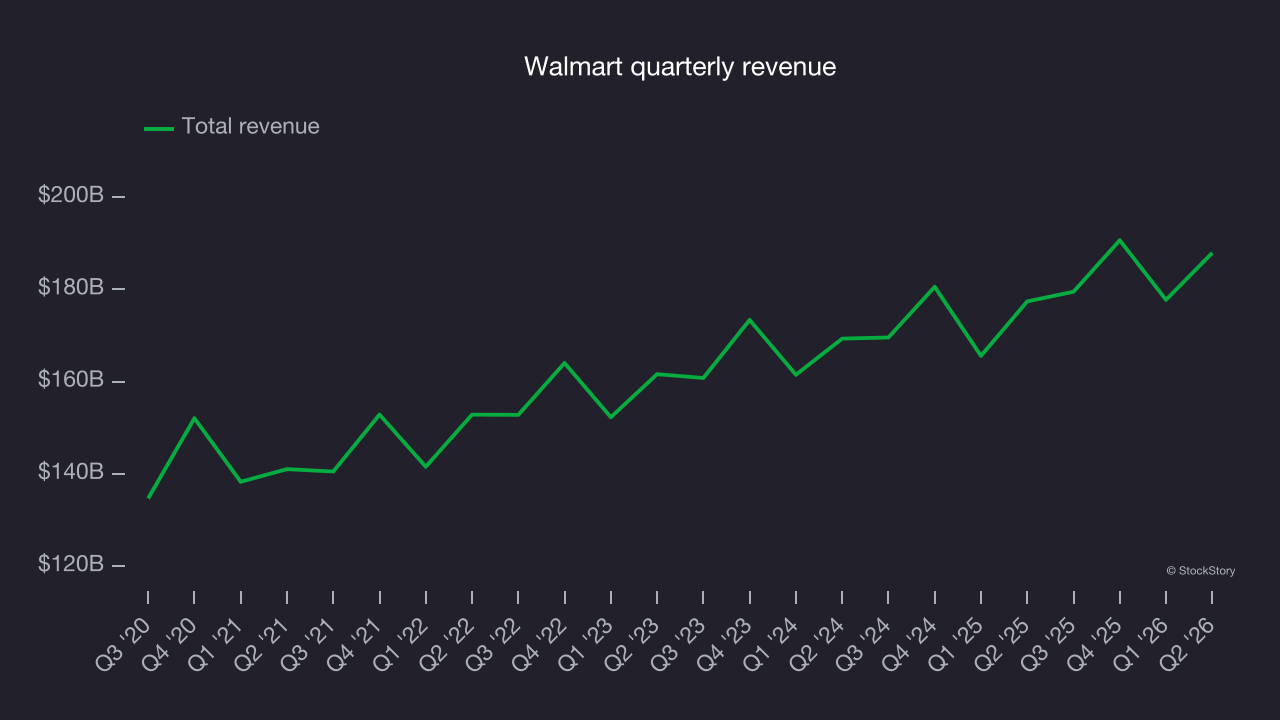
Examining a company’s long-term performance can provide clues about its quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Over the last three years, Walmart grew its sales at a tepid 5.3% compounded annual growth rate. This fell short of our benchmark for the consumer retail sector.
2. Low gross margin reveals weak structural profitability
Gross profit margins are an important measure of a retailer’s pricing power, product differentiation, and negotiating leverage.
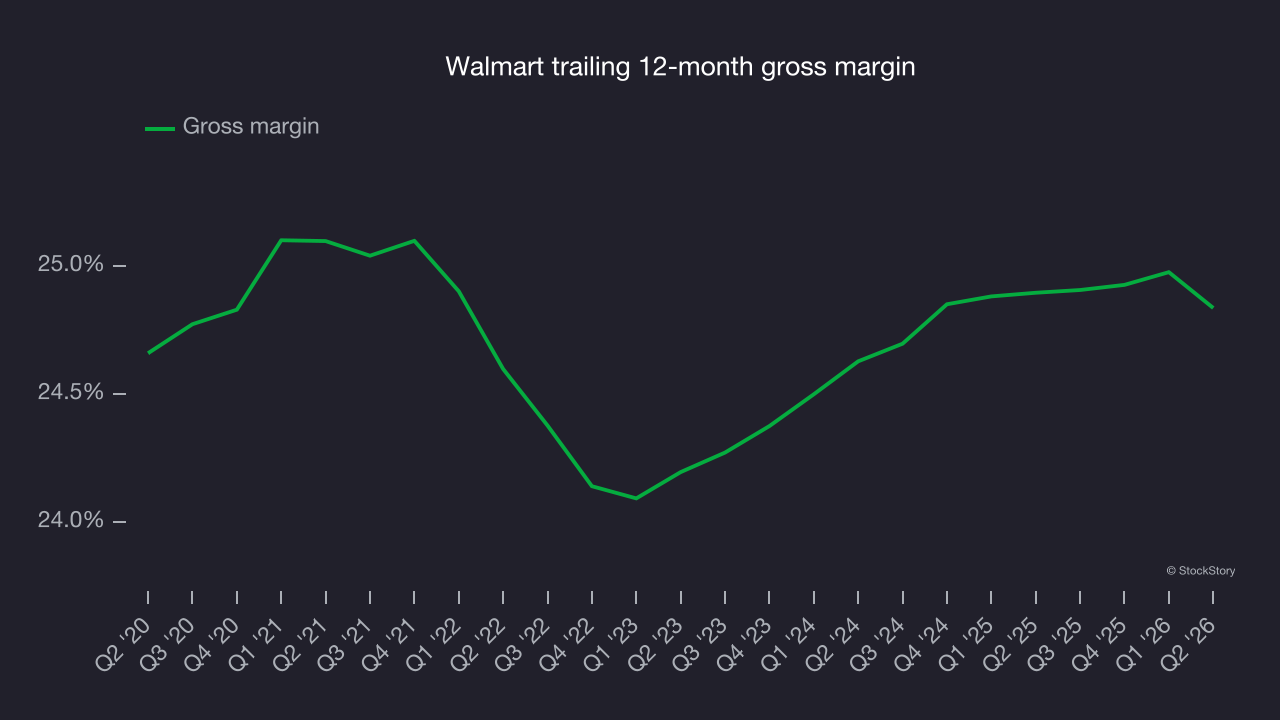
Walmart has bad unit economics for a retailer, signaling it operates in a competitive market and lacks pricing power because its inventory is sold in many places. As you can see below, it averaged a 24.9% gross margin over the last two years. That means Walmart paid its suppliers a lot of money ($75.13 for every $100 in revenue) to run its business.
3. Weak operating margin could cause trouble
Operating margin is a key measure of profitability. Think of it as net income – the bottom line – excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
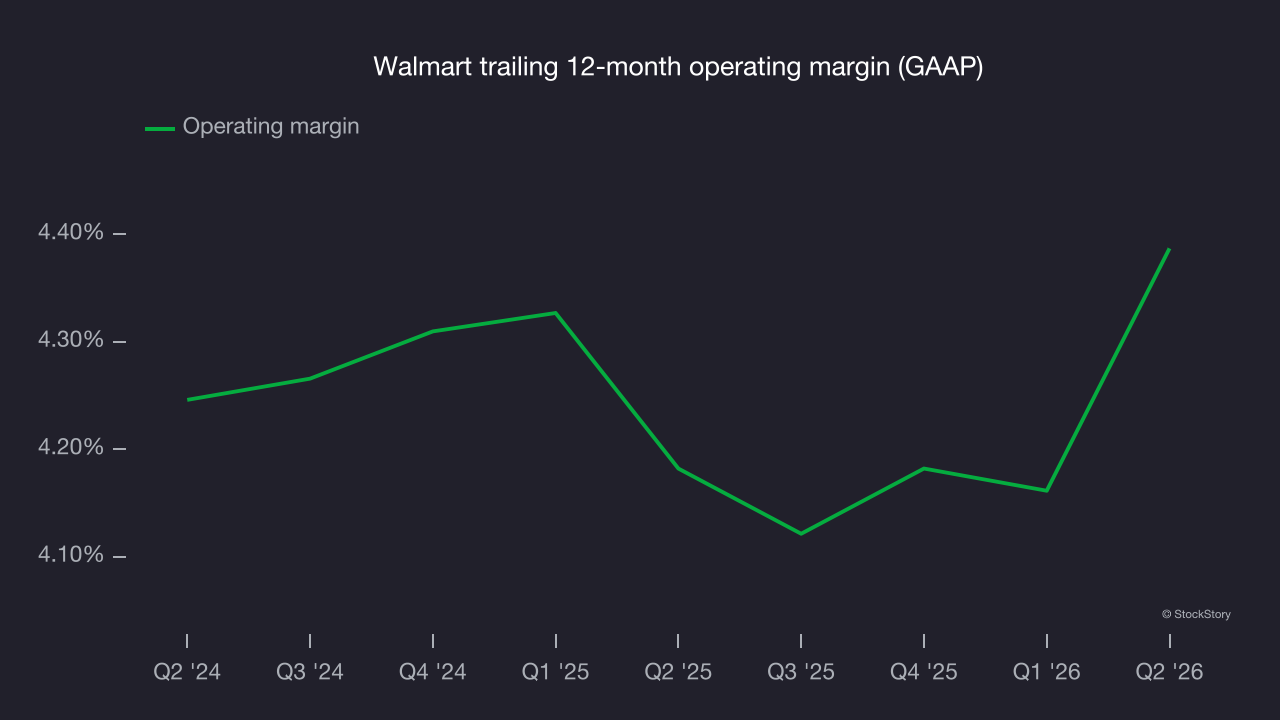
Walmart’s operating margin has more or less stayed the same over the last 12 months , averaging 4.3% over the last two years. This profitability was lousy for a consumer retail business and caused by its suboptimal cost structureand low gross margin.
Final judgment
Walmart isn’t a terrible business, but it doesn’t pass our quality test. With its shares underperforming the market lately, the stock trades at 43× forward P/E (or $127.09 per share). This valuation tells us it’s a bit of a market darling with a lot of good news priced in – we think other companies feature superior fundamentals at the moment. We’d suggest looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
Stocks we like more than Walmart
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.