Rising bond yields after a strong US jobs report have pushed borrowing costs higher and put pressure on many interest rate sensitive stocks. That kind of broad selloff can leave solid cash generators priced as if their future is far more fragile than their balance sheets suggest. This article highlights three companies where current share prices look out of sync with their underlying cash flow potential.
The three stocks below are just a sample set. The full screen on Simply Wall St surfaced 108 more companies with cash flows and valuations that tell similarly compelling stories not covered here. To identify and analyze the ideas that best fit your own style, head straight into the Undervalued Stocks Based On Cash Flows screener.
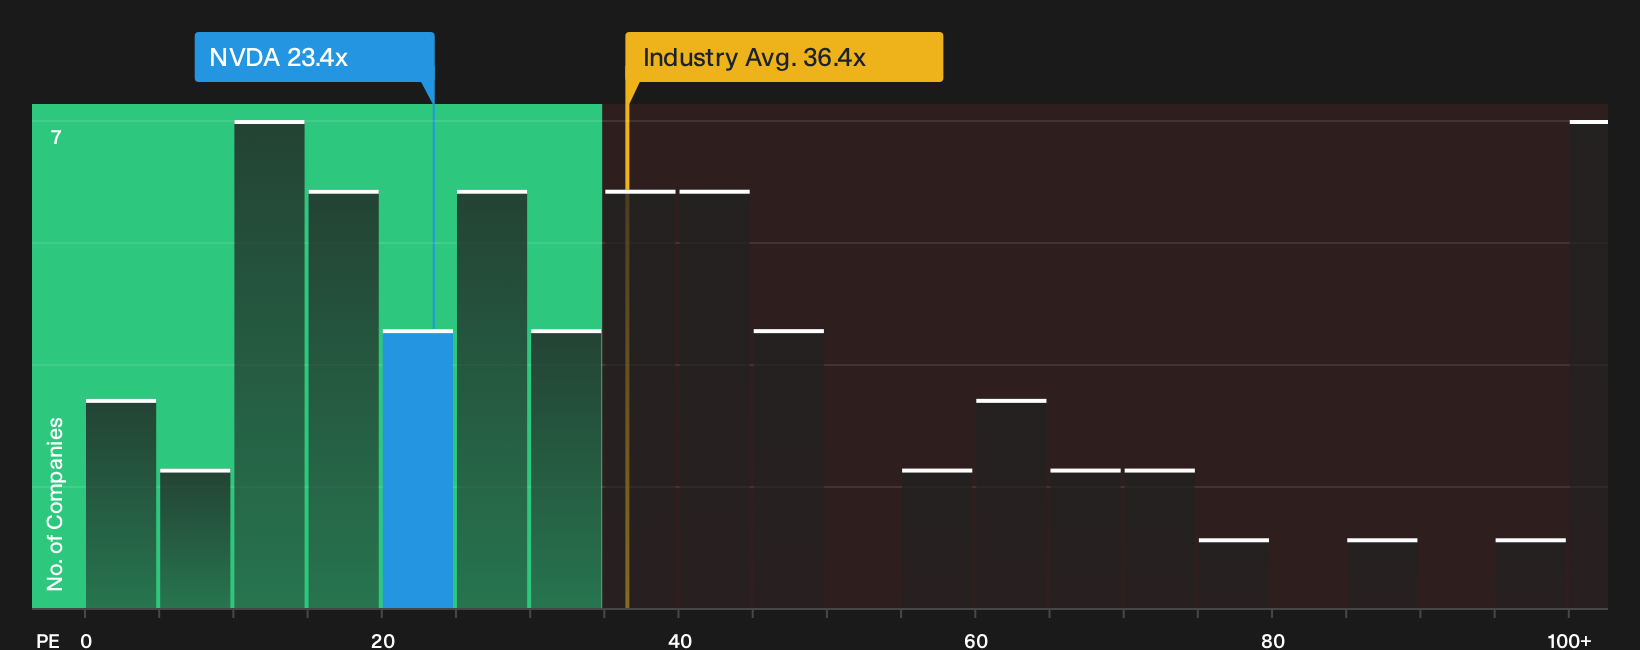
NVIDIA (NVDA)
Overview: NVIDIA runs a global AI and graphics hardware and software platform, powering data centers, gaming, professional visualization, and automotive systems.
Operations: NVIDIA generates about $275.4b from Compute & Networking and $27.6b from Graphics, largely across the United States, Taiwan, China, and other countries.
Market Cap: $4,385.1b
NVIDIA matters for this cash flow focused list because its data center GPUs and AI software directly convert AI infrastructure demand into sizeable recurring income streams.
“Uptake of an open-source, cheaper, or better platform than Nvidia’s CUDA would heavily undermine Nvidia’s moat and enable any sizeable firm to directly engage semiconductor manufacturers, such as TSMC, to produce their own chips, stealing away Nvidia’s high margin products (similar to what Apple did with its M-Series chips)”
For investors watching NVIDIA, what happens if a single key assumption about competitive pressure quietly shifts could reshape the margin story entirely.
If that competitive thesis is on your mind, read the full narrative for NVIDIA to see how NVIDIA’s AI cash engine could still accelerate even as the moat gets tested.
Dollar General (DG)
Overview: Dollar General runs discount stores across the United States, selling low priced everyday consumables and household basics that encourage frequent repeat visits and steady cash generation.
Operations: Dollar General generates about US$43.6b in revenue from its retail store operations, primarily through its discount store network in the United States.
Market Cap: US$30.4b
Dollar General earns its place in an undervalued cash flow screen because those everyday trips for paper goods, pantry staples, and over the counter essentials create a recurring revenue stream that is well suited to discounted cash flow analysis.
“Expansion of the Dollar General store footprint, including ongoing openings in underserved areas and early testing of new markets such as Mexico, is expected to keep adding selling square footage and support future revenue growth.”
What happens if a single assumption about how much profit Dollar General can squeeze from each of those extra visits quietly shifts?
If that shift in profit per trip is the real hinge, read the full narrative for Dollar General to see how Dollar General’s cash engine could accelerate or stall.

Cognizant Technology Solutions (CTSH)
Overview: Cognizant Technology Solutions provides AI-led automation, consulting, and outsourcing services that support recurring, fee-based revenue across major global industries.
Operations: The business generates about $6.7b from Financial Services, $6.4b from Health Sciences, $5.3b from Products and Resources, and $3.5b from Communications, Media and Technology.
Market Cap: $29.7b
Cognizant Technology Solutions fits this cash flow focused list because AI-led automation and Cognizant Moment help turn large, long-running client relationships into high-margin, repeat revenue contracts, even though these AI-centric lines sit within a broader IT services mix.
“Cognizant Technology Solutions is leaning into a shift from traditional systems integration toward AI-led enterprise operations, with management pointing to a potential addressable market of 5 to 6 trillion dollars that could support revenue growth as more operational labor becomes exposed to digital labor.”
Consider what happens if a single assumption about how much of that digital labor opportunity actually converts into higher margin, recurring work quietly shifts.
If that conversion rate is the real swing factor, read the full narrative for Cognizant Technology Solutions to see how Cognizant Technology Solutions could turn exposed labor into accelerating cash flows.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. By the time momentum headlines arrive, early entries are already flying. Scan these curated lists while it still matters and look for opportunities at an earlier stage.
- Target reliable cash payouts before yields start dropping by reviewing the 8 dividend fortresses curated for durability and income focus.
- Explore potential automation momentum by checking the 89 robotics and automation stocks packed with businesses wiring factories, warehouses, and devices for smarter workflows.
- Review the AI build out landscape by tapping into the 52 AI infrastructure stocks featuring companies supplying the pipes, power, and hardware behind the trend.
Valuation is complex, but we’re here to simplify it.
Discover if NVIDIA might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com