No reports scheduled
Tuesday, September 22
Earnings Before the Open
AutoZone (AZO), est. $54.30 per share
MillerKnoll (MLKN), est. $0.35 per share
Thor Industries (THO), est. $0.89 per share
Economic Releases
12:15 GMT, ADP Weekly Employment Change, prior 16.3K
14:00 GMT, Richmond Manufacturing Index, forecast 5 (prior 4)
Earnings After the Close
KB Home (KBH), est. $0.89 per share
Worthington Enterprises (WOR), est. $0.75 per share
Wednesday, September 23
Earnings Before the Open
Cintas (CTAS), est. $1.35 per share
Cracker Barrel (CBRL), est. $0.16 per share
General Mills (GIS), est. $0.72 per share
Paychex (PAYX), est. $1.32 per share
Economic Releases
13:45 GMT, Flash Manufacturing PMI, forecast 53.4 (prior 53.9)
13:45 GMT, Flash Services PMI, forecast 56.0 (prior 56.5)
14:30 GMT, Crude Oil Inventories, prior -0.6M
Earnings After the Close
H.B. Fuller (FUL), est. $1.47 per share
Stitch Fix (SFIX), est. -0.06 per share
Thursday, September 24
Earnings Before the Open
Darden Restaurants (DRI), est. $2.05 per share
TD Synnex (SNX), est. $4.68 per share
Darden, the Olive Garden parent, is expected to report fiscal 2027 first-quarter earnings of $2.05 per share, up 4.1% from a year earlier, on revenue of $3.2 billion, up 6.7%. UBS analyst Dennis Geiger expects solid same-store-sales trends and an intact earnings outlook despite select macro pressures. Investor sentiment is skewed negative on weak Olive Garden same-store sales, while LongHorn remains positive.
Economic Releases
12:30 GMT, Unemployment Claims, forecast 201K (prior 196K)
12:30 GMT, Current Account, forecast -259B (prior -227B)
14:00 GMT, New Home Sales, forecast 619K (prior 607K)
14:30 GMT, Natural Gas Storage, prior 44B
Earnings After the Close
Costco Wholesale (COST), est. $6.53 per share
BlackBerry (BB), est. $0.04 per share
FedEx Freight (FDXF), est. $1.39 per share
Costco is expected to report fiscal fourth-quarter earnings of $6.53 per share, up 11.2% from a year earlier, on revenue of $94.9 billion, up 10.1%. Oppenheimer analyst Rupesh Parikh said core earnings could again fall short of Street forecasts excluding tariff-refund benefits. He maintained an Outperform rating and said weakness in the shares represents a buying opportunity.
Friday, September 25
Earnings Before the Open
No reports scheduled
Economic Releases
12:30 GMT, Core Durable Goods Orders m/m, forecast 0.5% (prior 0.4%)
12:30 GMT, Durable Goods Orders m/m, forecast -0.3% (prior 1.1%)
14:00 GMT, Revised UoM Consumer Sentiment, forecast 47.5 (prior 47.8)
14:00 GMT, Revised UoM Inflation Expectations, prior 4.6%
Earnings After the Close
No reports scheduled
Central Bank Activity
Monday, September 21
- Austan Goolsbee (FOMC Member), 10:30 GMT
Tuesday, September 22
- John Williams (FOMC Member), 14:05 GMT
- Philip Jefferson (FOMC Member), 14:20 GMT
- Thomas Barkin (FOMC Member), 17:00 GMT
Wednesday, September 23
- Michael Barr (FOMC Member), 14:05 GMT
Thursday, September 24
- John Williams (FOMC Member), 08:10 GMT
- Beth Hammack (FOMC Member), 12:50 GMT
- Anna Paulson (FOMC Member), 14:10 GMT
Friday, September 25
- John Williams (FOMC Member), 09:15 GMT
- Beth Hammack (FOMC Member), 18:00 GMT
Wall Street will watch the 10 appearances for hints about the path for interest rates after the September rate hike. The Fed’s projections included another expected increase before year-end, while officials remained divided over the need for further tightening in 2027.
Technical Outlook
Weekly Dow Jones Industrial Average Index
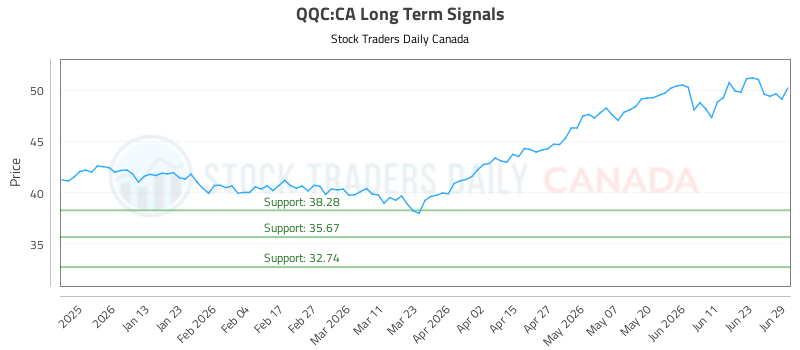
S&P 500: 7,650.50 (-0.08%), support at 7,565.31, 7,527.28, 7,507.77, 7,313.92, 7,237.85, the 52-week SMA at 7,092.96, 7,066.81, 6,889.83 and 6,316.91, resistance at 7,662.24 and 7,816.70.
All major indices remain above rising 52-week SMAs, confirming an intact long-term uptrend.
Outlook
Friday’s revised consumer-sentiment and inflation-expectations data are the week’s main economic event. Flash PMIs, durable-goods orders, jobless claims, housing data, Darden and Costco will provide the other scheduled catalysts.
Traders will monitor the Fed speakers for the policy path after the September hike and Friday’s consumer-sentiment data for inflation concerns. Holding the listed weekly support levels would maintain the long-term uptrend, while a break below them would put the indices under pressure.
More Information in our Economic Calendar.