Quick Read
-
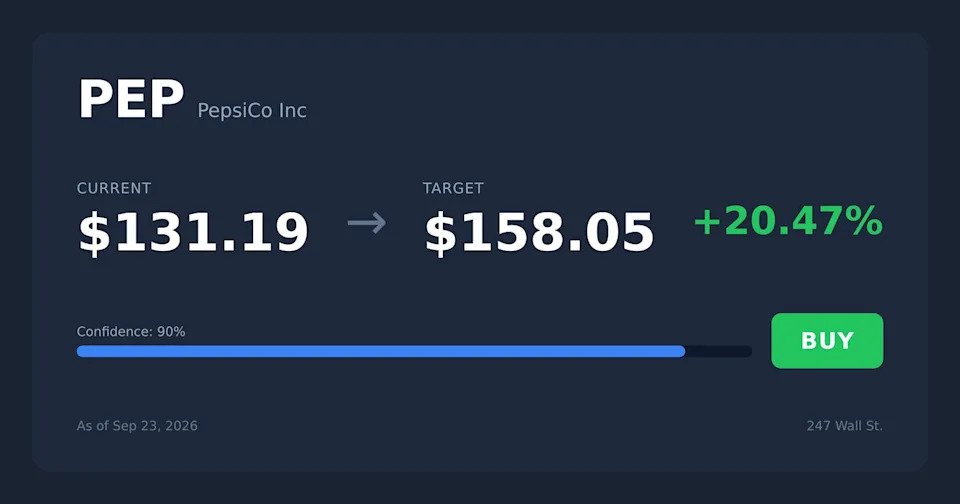
PepsiCo (PEP) trades near its 52-week low with a 4.31% dividend yield and 17% upside to the $152.80 price target.
-
PEP trades at a forward P/E of ~16, a steep discount to Coca-Cola (KO) at 25x and Mondelez (MDLZ) at 18x, while offering the highest yield.
-
Even the bear scenario lands at $142, above today’s price, backed by $10 billion in buybacks and 54 consecutive years of dividend growth.
-
Just released. Our analysts combed the entire stock market and named the ten best stocks to buy right now, and PepsiCo didn’t make the cut. Enter your email to see the names that beat PEP. The report is free. Enter your email and see if any of your stocks made the cut.
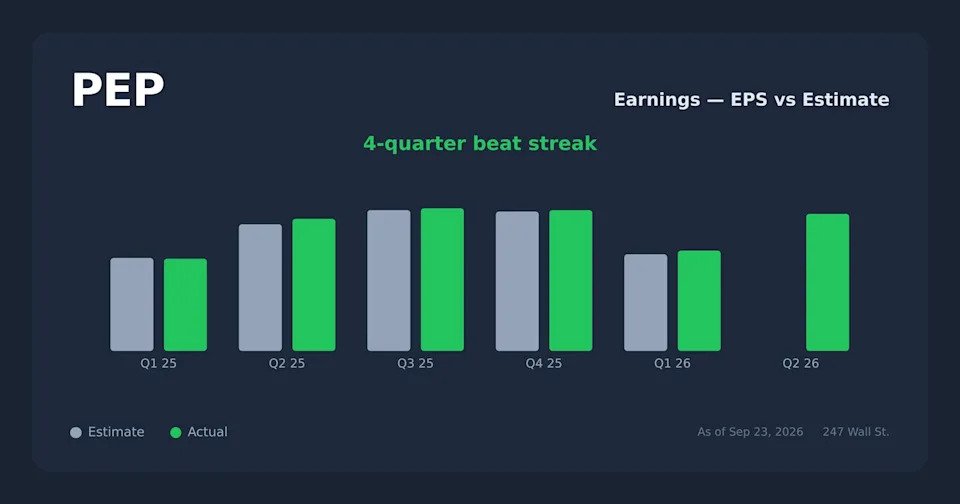
PepsiCo (NASDAQ:PEP) has become a genuinely out-of-favor name in a market obsessed with AI and momentum. The stock trades near its 52-week low of $129.55, sports a 4.31% dividend yield, and is coming off four consecutive quarters of beating consensus EPS estimates. Our 24/7 Wall St. price target for PepsiCo is $152.80, implying meaningful upside from current levels.
24/7 Wall St. Price Target Summary
Why Pepsi Is Trading Where It Is
PepsiCo shares are down 6.7% year to date and 7.88% over the past month.
Q2 pressure came from PepsiCo Foods North America revenue declining 2% and core operating margin contracting 40 basis points. International results offset: LatAm Foods +15%, Asia Pacific Foods +12%, EMEA +10%, and IB Franchise +11%.
Q2 core EPS came in at $2.20 on revenue of $24.18 billion, up 6.4% year over year. CEO Ramon Laguarta noted “fastest growth in volumes since 2022”.
Free Report, Just Released
Why Didn’t PEP Make The Top 10 List?
24/7 Wall St has helped investors make money for over two decades, and our top analysts just finished ranking the definitive Top 10 Stocks To Buy Now. Not the ten biggest companies. Not the ten everyone is arguing about. The ten best stocks to buy right now.
And PEP didn’t make the cut!
The report is free, and you can see why we think each stock is a top investment today.
Enter Your Email and See the Ten →
Why Bulls See a Breakout Ahead
The bull case rests on international momentum, portfolio innovation, and shareholder returns. Management expects international business to cross $40 billion this year, with operating margin up a full point in Q2. Poppi, Siete, functional hydration, protein snacks, and zero-sugar beverages offer reinvention optionality.
The $10 billion buyback authorization through 2030 plus 54 consecutive years of dividend growth mean shareholders get paid to wait. Bull scenario points to $161.88, and Street consensus sits at $155, with 29 bullish analysts against 4 bearish.