Central Securities (CET) drew fresh attention after its recent share performance, with the stock closing at US$55.85 and posting gains over the past month and the past 3 months.
Central Securities has seen its recent share price move in a relatively tight range. However, the 3 month share price return of 8.03% and year to date share price return of 10.09% point to building momentum, while the 1 year total shareholder return of 15.74% and 3 year total shareholder return of 83.18% show a much stronger longer run payoff profile than the near term trading suggests.
Scan Central Securities alongside a curated 30 high quality undervalued stocks featuring companies with solid cash flows and balance sheets for investors focused on quality at a sensible price.
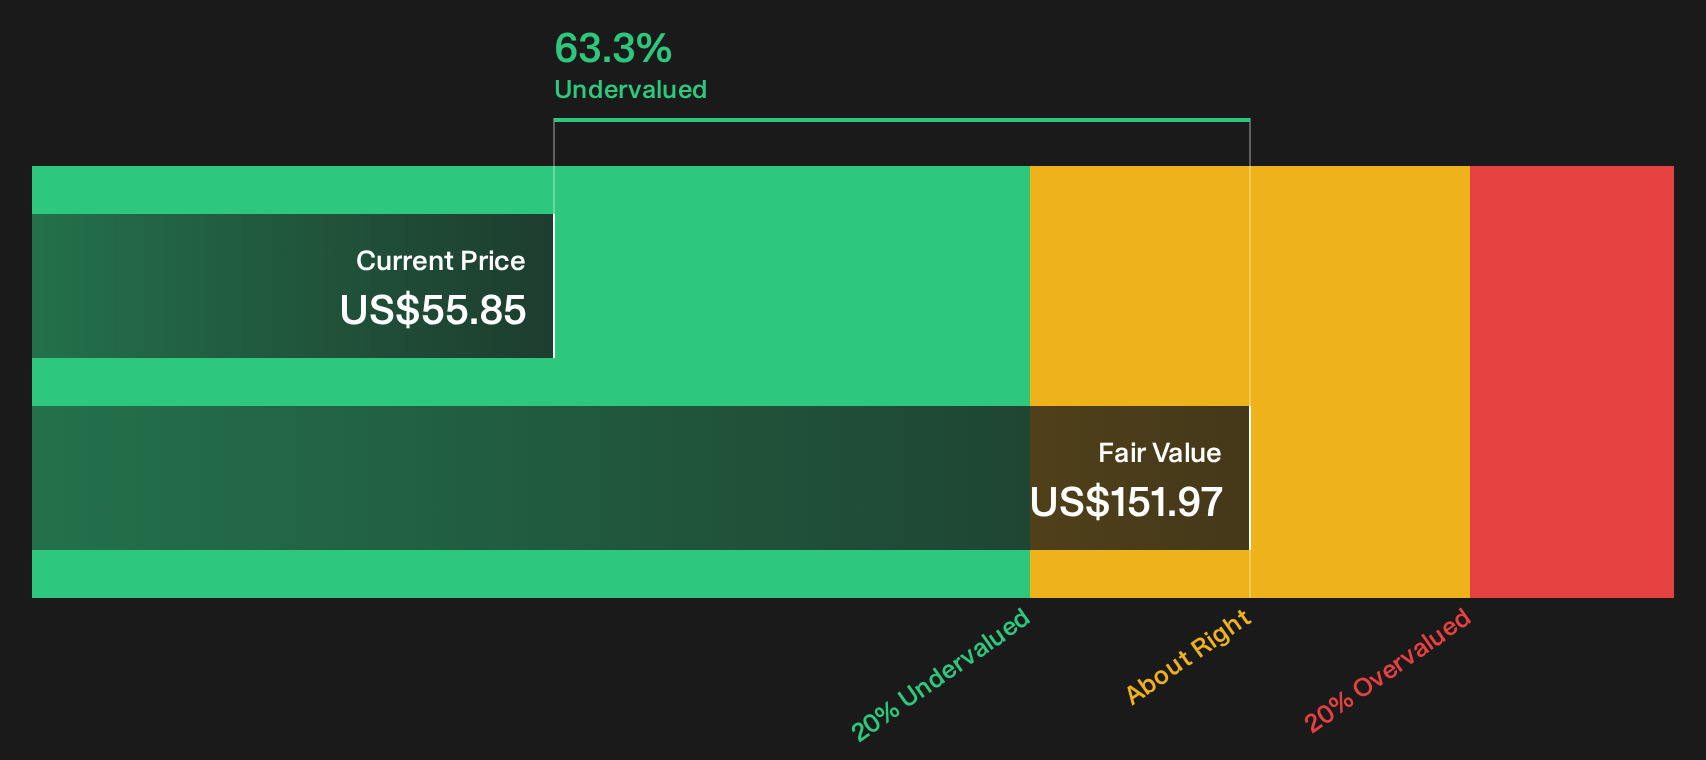
Central Securities now trades at what looks like a steep intrinsic discount of about 63%, even after the recent share price climb. Is that a genuine pricing gap or a reflection of risks the market still sees?
Preferred P/E ratio of 7.6x for Central Securities: Is it justified?
On the numbers, Central Securities looks cheap compared to both its own earnings profile and peers. The stock closed at $55.85 while trading at a P/E of 7.6x, and that sits against an estimated intrinsic discount of about 63% based on the SWS DCF model.
The P/E ratio compares what investors pay for each dollar of earnings. For an investment company like Central Securities that owns a portfolio of securities, this yardstick gives a quick sense of how the market is pricing current profit against what similar capital markets businesses trade for.
CET is described as good value on this metric versus a peer average P/E of 12.5x and an even higher 39.6x for the broader US Capital Markets group. That is a wide gap. Earnings have grown by 8.6% per year over the past 5 years, although profit growth slowed to 1.5% in the last year and recent results include a large one off gain of $181.6m, which can distort simple comparisons.
The SWS DCF model adds another reference point. It estimates a future cash flow value of $151.97 per share, which is well above the current $55.85 level. The DCF approach projects future cash flows and discounts them back to today, so it reacts to both earnings quality and the long record of Central Securities as an investment manager rather than just one year of results.
For readers who want to see how that intrinsic value is built from the ground up, including the cash flow forecasts and discounting assumptions, Look into how the SWS DCF model arrives at its fair value.
Result: Price-to-earnings of 7.6x (UNDERVALUED).
Still, Central Securities relies on public markets and investment returns, so weaker portfolio performance or changes in interest rates could quickly challenge that apparent discount.
Find out about the key risks to this Central Securities narrative.
Another View on Central Securities’ value
Price based ratios make Central Securities look inexpensive, yet the SWS DCF model points to something more extreme. On that framework, the future cash flow value is estimated at $151.97 per share, which implies a deep undervaluation versus the current $55.85 price. Could that gap really be sustainable?
For readers who want to see how the full cash flow model stacks up against the simple P/E view, including the assumptions behind both, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Central Securities for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match – so you never miss a potential opportunity.
Next Steps
Mixed signals around Central Securities can be confusing, so treat this as a prompt to look under the hood yourself and move quickly while sentiment is still forming. To understand both sides of the story, weigh the 2 key rewards and 3 important warning signs
Looking for more investment ideas beyond Central Securities?
Central Securities may belong on your watchlist, but the real edge often comes from lining up a broader bench of quality opportunities.
Use the Simply Wall Street Screener to uncover ideas that match your style before others move first.
- Target resilience by scanning a 30 resilient stocks with low risk scores that can help you focus on companies with steadier profiles when markets turn choppy.
- Hunt for quality at a fair price by reviewing a curated 30 high quality undervalued stocks designed for investors who care about both fundamentals and valuation discipline.
- Seek out staying power by checking a list of solid balance sheet and fundamentals (24 results) that highlights firms with stronger financial footing when conditions change quickly.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
New: AI Stock Screener & Alerts
Our new AI Stock Screener scans the market every day to uncover opportunities.
• Dividend Powerhouses (3%+ Yield)
• Undervalued Small Caps with Insider Buying
• High growth Tech and AI Companies
Or build your own from over 50 metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com