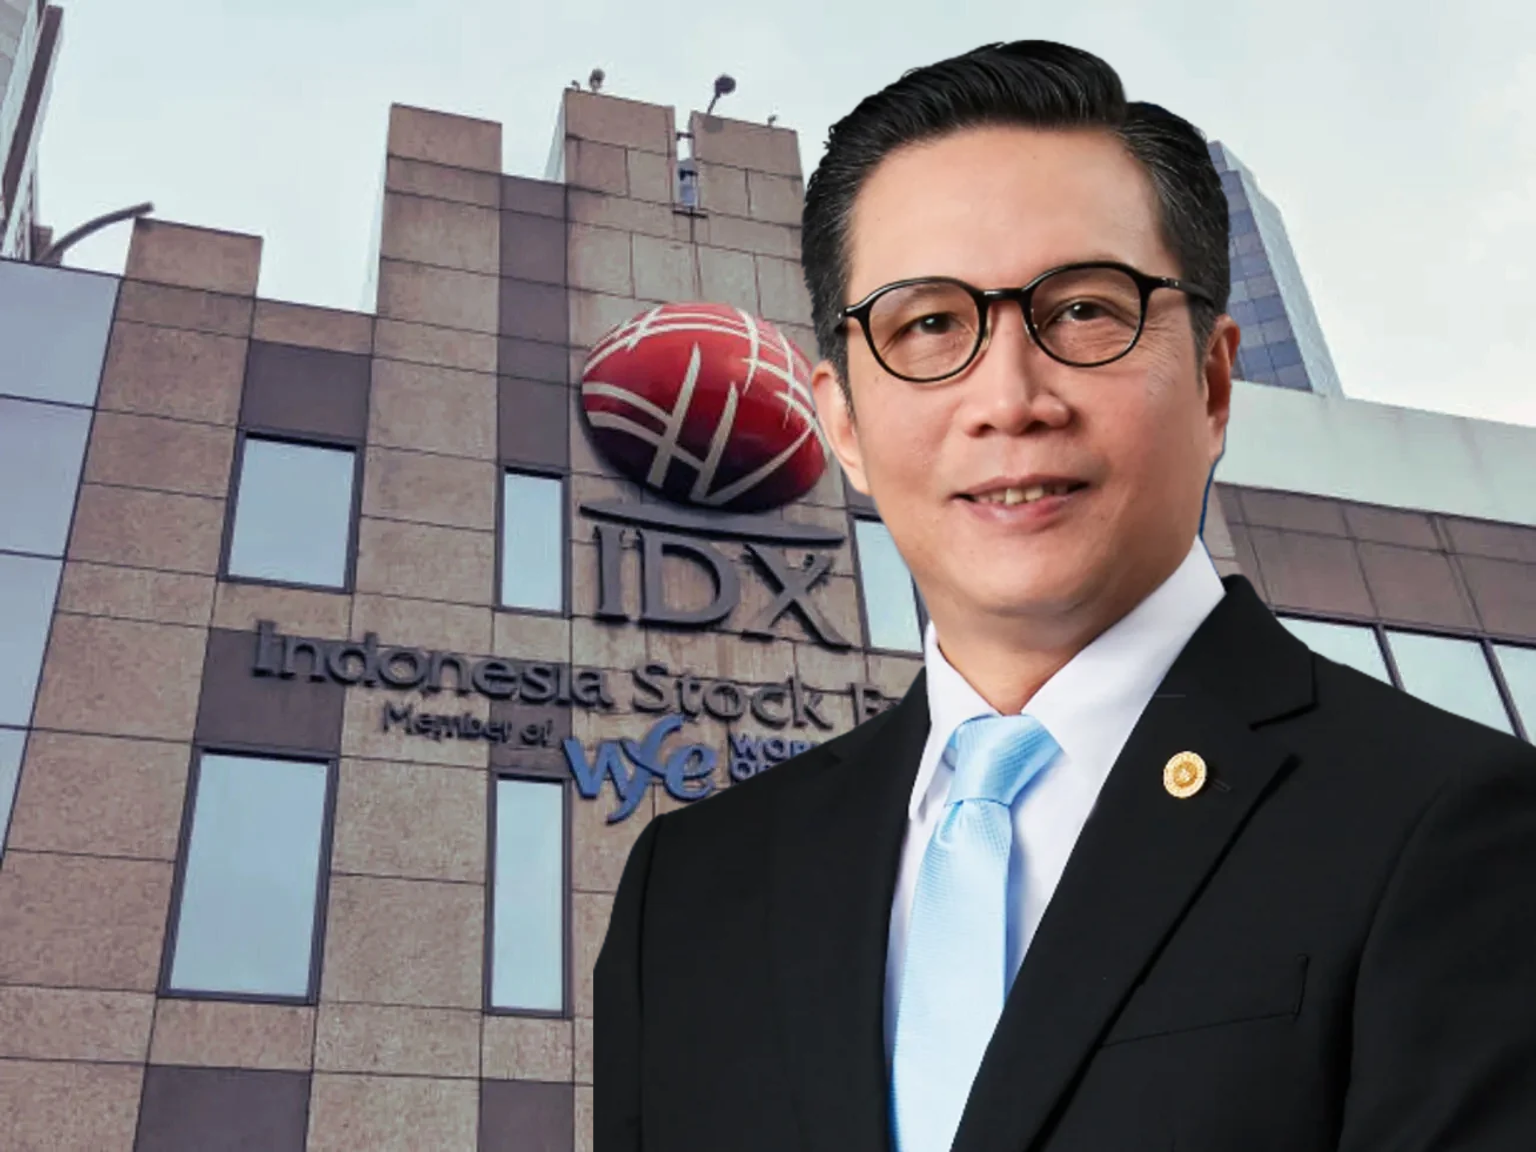
Photo: Jeffrey Hendrik, President Director, Indonesia Stock Exchange
Indonesia’s stock market, suffered its steepest one-day fall in nearly three decades on 16 October, after global index provider MSCI proposed downgrading the country from emerging-market to standalone-market status. The Jakarta Composite Index (IDX) plunged 11.6%, triggering a trading halt. The sell-off deepened an already severe decline, leaving Indonesia the world’s worst-performing stock market this year, with losses exceeding 40%. Foreign investors have withdrawn nearly $5 billion from Indonesian equities in 2026, adding to pressure on the country’s financial markets.
What triggered the sell-off. MSCI’s proposed reclassification reflects concerns about market transparency, concentrated share ownership and suspected coordinated trading. The index provider said reforms announced by Indonesian authorities had not yet produced sufficient evidence of lasting improvements in market governance and trading conditions.
The concerns are significant because MSCI’s indexes guide investment decisions worldwide. Funds that track emerging-market indexes may have to sell Indonesian shares if the country loses its current classification. Other fund managers, including those whose performance is measured against these indexes, may also reduce their exposure. The proposed downgrade therefore threatens to turn concerns about market integrity into a direct source of selling pressure.
MSCI launched a consultation on 15 October and expects to announce its final decision by the end of June 2027. Until then, restrictions on certain changes to Indonesian securities in its indexes will remain in place.
What Indonesia needs to address. The issue extends beyond the immediate fall in share prices. Investors need reliable information about who owns listed companies, how much of their shares are genuinely available for trading, and whether prices reflect normal market activity.
Indonesian authorities have announced several reforms, including stronger disclosure of shareholders with stakes above 1 per cent, more detailed investor classification and plans to raise the minimum free float requirement for listed companies to 15 per cent. MSCI has nevertheless stressed that announcing reforms is not enough. Investors want evidence that the measures are being applied consistently and that enforcement is improving.
The response has started to take shape. On 26 October, the Indonesia Stock Exchange announced further measures to investigate suspected coordinated trading, including plans to freeze suspicious investor accounts from November. It also plans to exclude shares with highly concentrated ownership from its main Jakarta index from 2 November. These measures could help address some of MSCI’s concerns, but their effectiveness will depend on implementation and the results they produce.
A wider test for emerging markets
Indonesia’s experience highlights a broader issue for developing financial markets. Economic growth and market size do not automatically translate into investor confidence. International investors also need clear ownership records, fair trading conditions and confidence that regulators can act when market practices threaten the integrity of prices.
The potential cost of losing emerging-market status is substantial. Reuters reported that estimates from banks put possible outflows from passive emerging-market funds at $3 billion to $6 billion if Indonesia is downgraded. UBS has also warned that active investors could withdraw a further $15 billion. These are estimates rather than confirmed future outflows, but they show how an index classification decision can affect a country’s access to international capital.
For Indonesia, the risk is not limited to forced selling. A prolonged loss of confidence could make it harder for companies to attract foreign investment and raise capital on favourable terms. It could also put further pressure on the rupiah and weaken sentiment towards Indonesian assets more broadly.
Why it matters beyond Indonesia
For banks, asset managers and other financial institutions operating across emerging markets, the episode demonstrates how market structure and regulatory credibility can become financial risks in their own right.
Banks involved in securities services, investment management and capital markets may face greater volatility, changing client positions and more demand for risk management. Foreign investors may also reassess their exposure to markets where ownership information is difficult to verify or where enforcement appears inconsistent.
The episode also shows how quickly a technical decision by an index provider can become a wider market event. Index classifications are not regulatory ratings, but they influence how large pools of investment are allocated. When a market loses access to a major benchmark, the consequences can extend well beyond the companies directly affected.
The Digital Banker’s commentary
Indonesia’s market turmoil should not be viewed simply as a reaction to a possible downgrade. MSCI’s decision has brought long-standing concerns about ownership transparency, trading practices and enforcement into sharper focus. The scale of the sell-off suggests that investors were already uneasy about the market, although the decline alone does not establish how much of the damage reflects structural concerns rather than short-term panic.
The distinction matters. Indonesia has introduced reforms, but the test is whether they produce verifiable improvements in how the market operates. Greater disclosure is useful only if investors can rely on the information, while new rules have limited value if suspected misconduct is not investigated and addressed.
There is also a wider lesson for emerging markets seeking foreign capital. A large economy, a sizeable stock exchange and strong growth prospects may attract attention, but they cannot fully compensate for doubts about market fairness and access. Confidence depends on institutions demonstrating that investors can assess risks and trade on a reasonably transparent basis.
Indonesia still has time to influence MSCI’s final decision, with the consultation running until April 2027 and the decision due by the end of June. The key question is whether the authorities can show measurable progress before then. Their response will help determine not only the country’s index status, but also how international investors judge the credibility of its capital market.