Al Bentley
5 min read
Forgent Power Solutions (FPS) has become a talking point after reporting first quarter fiscal 2027 earnings, with sales of US$478.57 million and net income of US$48.24 million, including US$0.18 in basic earnings per share.
The share price reaction has been choppy. Forgent Power Solutions jumped earlier this week around the earnings headlines, yet the 1 day share price return is down 9.85%, the 7 day move is up 21.64%, while the 30 day and 90 day share price returns are down 38.76% and 44.15% respectively. This points to short term momentum fading within a broader pullback that reflects shifting views on both its growth potential and risk profile.
Capitalize on the volatility around Forgent Power Solutions by lining it up against 43 power grid technology and infrastructure stocks, which are also exposed to data centers and grid infrastructure.
The market has pulled Forgent Power Solutions down to about US$22 even as analyst targets cluster near US$51 and some intrinsic value models lean lower again. Where does a reasonable fair value line actually fall in that spread?
Preferred P/E of 83.4x: Is it justified?
Forgent Power Solutions closed at $22.15 while trading on a P/E of 83.4x, and the surrounding data points to a valuation that leans rich rather than cheap when lined up against both its own fair ratio and the wider electrical equipment peer group.
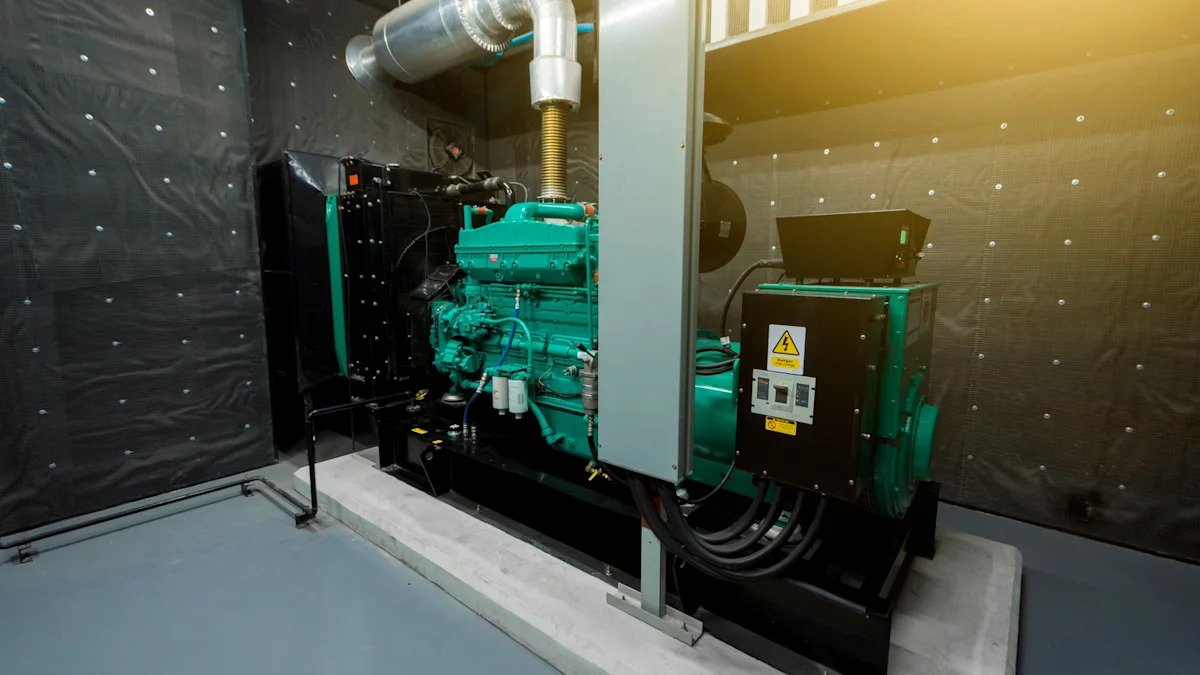
The P/E multiple compares the current share price to earnings per share and effectively captures how much investors are willing to pay for each dollar of profit. For a business like Forgent Power Solutions, which designs and manufactures electrical distribution equipment for data centers, grid projects and heavy industry, that ratio becomes a shorthand for how much future earnings growth and profitability investors are building into the price.
On the positive side, earnings and revenue forecasts are described as strong, with statements pointing to earnings expected to grow significantly and revenue forecast to expand 21.7% per year. The SWS DCF model also suggests a future cash flow value of $95.35, which is very far above the current share price and indicates the cash flow based model views the stock as trading at a 76.8% discount to its own estimate of fair value.
The multiples tell a very different story. FPS is described as expensive based on its P/E of 83.4x compared to a fair P/E of 44.5x that the fair ratio model indicates the market could shift toward over time. That gap implies investors are currently paying a much higher price than the level suggested by the relationship between fundamentals and valuation. Compared to the US Electrical industry average P/E of 27.9x and a peer group average of 62x, the 83.4x tag looks stretched and signals that buyers are already paying a premium for the forecast growth and for the quality of earnings the business is currently reporting.