Nobody likes to see the price of a stock they own go down.
But some of the most encouraging stock market stats involve what happens when things go wrong.
After Berkshire Hathaway announced Warren Buffett’s retirement, Meb Faber shared this mind-blowing stat.
“If Berkshire declined 99% today on the news of Buffett’s retirement, Berkshire would still have outperformed the S&P 500 since 1965,” Faber wrote. (Buffett took over Berkshire in 1965.)
Morningstar’s Danny Noonan illustrated this in a log-scaled chart.
Being able to lose 99% and remain up speaks to the asymmetry of long-term stock market returns. We’ll get back to this in a minute.
But first, I know that a stat like this will elicit mixed feelings. So before you get all riled up, let me flag a few issues:
-
Cherry-picked winner: Most stocks don’t outperform the S&P 500, so this stat reflects what happens if you’re lucky enough to pick a rare winner. Indeed, Buffett would be the first to tell you that luck plays a huge role in picking market-beating stocks. He’s made clear that the Berkshire equity portfolio’s ”satisfactory results have been the product of about a dozen truly good decisions — that would be about one every five years.“
-
One purchase: This stat is about a single hypothetical purchase made in 1965. Most people make purchases over many periods throughout their lifetime. This means a typical investor’s average cost would likely be much higher than the 1965 price, so a 99% decline would be far more costly.
-
Long holding period: It’s been 61 years since 1965. Most investors have a shorter time horizon before they have to sell. This includes even young people saving for retirement.
That said, I think we can all appreciate what this example teaches us about compound interest and the stock market’s potential upside.
Importantly, I hope this gets investors thinking about what it actually means to have to sell during a big market drawdown.
In the stock market, the most you can lose is 100% of what you put in. Admittedly, 100% is a lot.
On the other hand, some stocks go up by more than 100%. Some go up by 200%. Some go up by 2,000%. A few might even go up 591,000%.
Of course, it’s extremely difficult to pick those stocks that go on to generate eye-popping returns. But you don’t have to do this to be a successful investor.
A broadly diversified portfolio of stocks can also deliver far more upside than downside. S&P 500 index funds, which give you exposure to many high-performing stocks, have seen their value multiply over reasonable time horizons.
Importantly, the S&P has a long history of rising much more than it falls.
Check out the chart below from Creative Planning’s Charlie Bilello. It reviews the performance of history’s bull and bear markets. Since 1949, the average total return during bear markets was -31%. Meanwhile, the average total return during bull markets was +254%.
In other words, the value of an S&P index fund and its dividends more than triples in an average bull market. And these bull-market gains have always eclipsed and more than offset bear-market losses. This is probably obvious to anyone who’s seen a long-term chart of the stock market: essentially a line going up and to the right, with modest bumps along the way.
Investors’ primary fear is losing money. What if there’s a bear market, and the value of my allocation to stocks falls 20%?
Well, there’s a difference between being down 20% and being down 20%.
If you bought stocks today and prices fell 20%, then you’d be down 20%. That’s unfortunate. It happens to the best of us.
But what if you bought stocks about two years ago, experienced a 25% gain, and then the market fell 20%? You’d actually be at breakeven. Yes, you’d be down 20% from some higher value. But you wouldn’t have actually lost money based on the cost of your investment.
In a stock market that often falls but usually goes up, the odds that your portfolio is in the money — even in the midst of a bear market — improve as you extend your time horizon.
Consider me. I started buying stocks for my retirement account in 2005 when the S&P 500 was around 1,200. Ever since, I’ve bought more periodically. Fast forward to today, when the S&P 500 is trading at 7,722. If the market fell 20%, that would send the S&P to 6,178, a level initially reached in mid-2025. The chart below marks this level with the dotted line.
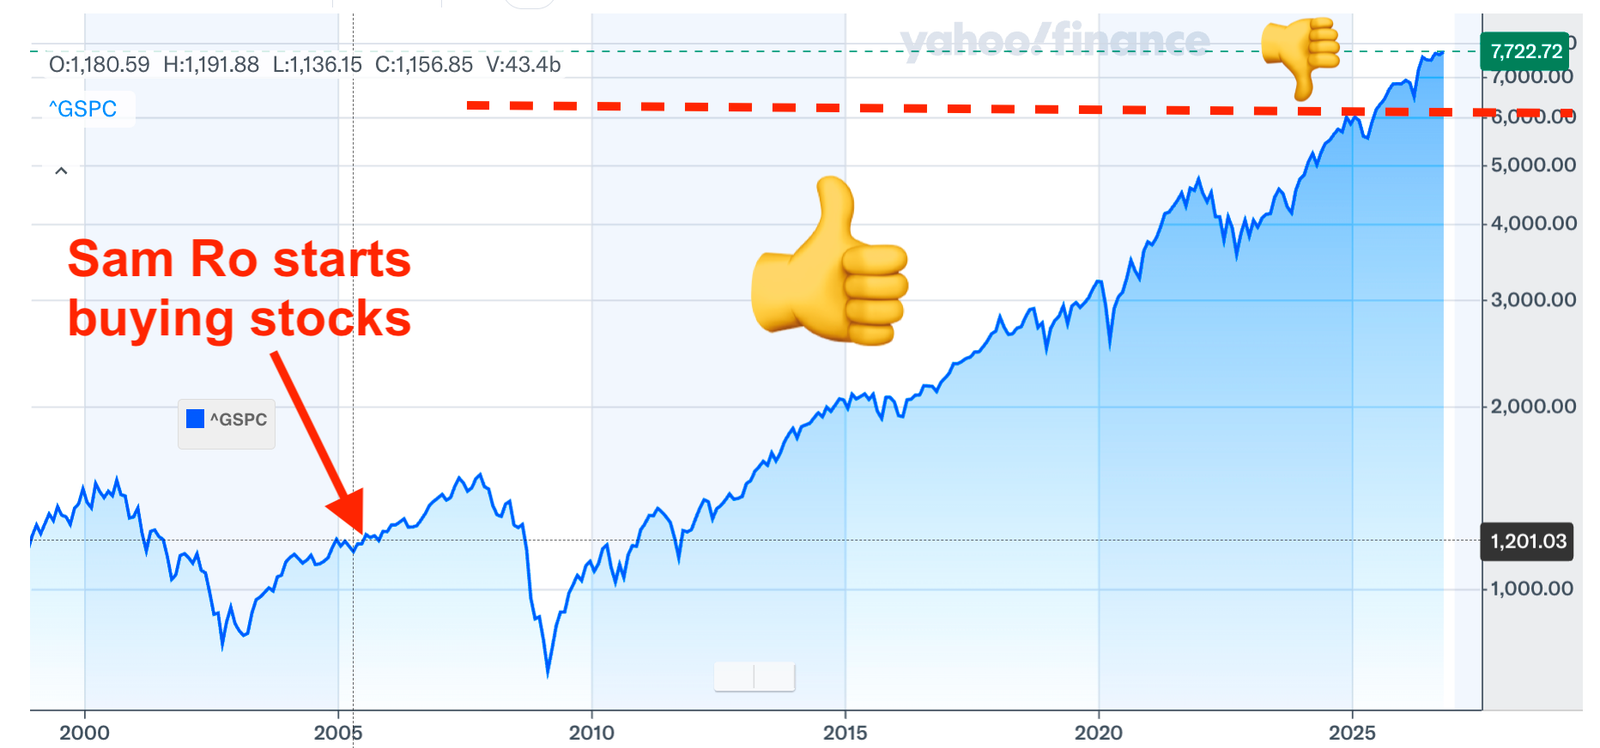
If the market fell 20% from current levels, then all of my purchases after mid-2025 (above the dotted line) would be in the red.
But the bulk of my purchases were made over the 19 years before then (below the dotted line), when the market was much lower. That explains why, despite being down 20%, the value of my portfolio is considerably higher than the total of what I put in.
It’s possible that when it’s time for you to sell, the market might be down more than 20%. But you’d have to be pretty unlucky, as the market has spent very little time in >20% drawdowns. Odds are market conditions will be much more favorable than that.
Nevertheless, I think it’s helpful to understand what it really means for you and your portfolio when the market is off its high.
Because if you’ve been investing for years, are you really down? Or are you up by a lot, but just not as much as you were?
–
Related from TKer:
-
Does it always make sense to think of a 20% decline in your portfolio as a loss? 🤨
-
The intimidating mathematical hurdle a beaten down stock market always clears 🙌
-
Warren Buffett: ‘It takes just a few winners to work wonders’ 🏆
-
Warren Buffett on luck and not beating yourself up over mistakes 🍀🤦🏻♂️
📉The stock market declined last week, with the S&P 500 shedding 0.3% to end at 7,722.72. The index is now down 1.0% from its August 13 closing high of 7,798.99 and up 12.8% year-to-date. For market insights, check out the Stock Market tab at TKer. »
There were several notable data points and macroeconomic developments since our last review:
🎈 Fed’s preferred inflation measure cooled. The personal consumption expenditures (PCE) price index in August was up 3.4% from a year ago. The core PCE price index — the Federal Reserve’s preferred measure of inflation — was up 3.0% during the month, down from July’s 3.3% rate.
On a month-over-month basis, the core PCE price index was up 0.2%. If you annualize the three-month trend in the monthly figures — a reflection of the short-term trend in prices — core PCE climbed 2.0%.
One month’s inflation print does not reflect a trend. But it’s encouraging to see at least one measure of inflation in line with the Federal Reserve’s 2% target. How price trends evolve in the near term continues to bear watching.
For more on the Fed’s impact on markets, read: ‘When will the Fed cut rates?’ is not the right question for investors right now ✂️
⛽️ Gas prices tick lower, but remain high. From AAA: “The national average for a gallon of regular gasoline dropped nearly 7 cents from last week to $4.41. This follows a record-setting September at the pump. The monthly average was $4.33, 50 cents higher than the previous September record of $3.83 set in 2023. Crude oil prices have dipped back into the $90 per barrel range, lowering the national average, but overall gas prices remain the highest they’ve ever been for this time of year.“
Here’s a longer-term look at the trajectory of gas and diesel prices, as tracked by the EIA.
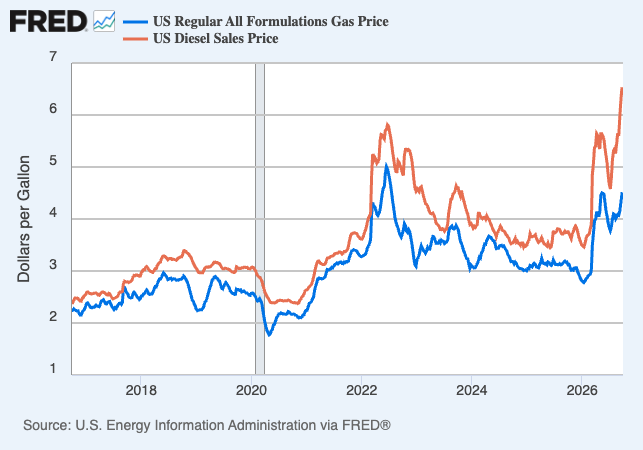
For more on energy prices, read: Our love-hate relationship with rising oil prices in charts 💔🛢️📊
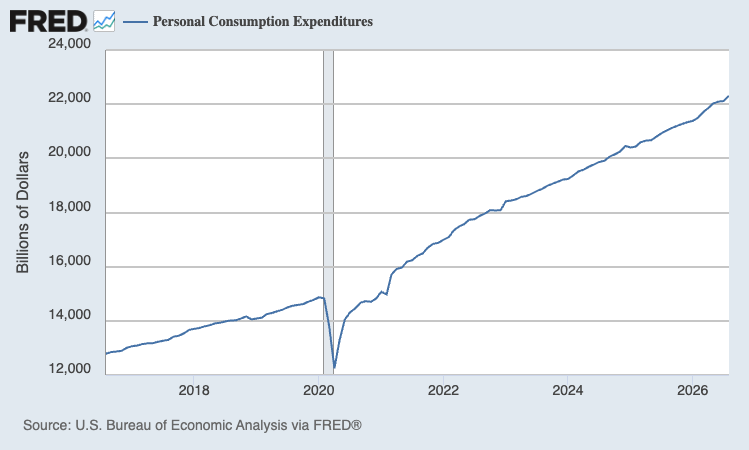
🛍️ Consumer spending ticks higher. According to BEA data, personal consumption expenditures increased 0.9% month-over-month in August to an annual rate of $22.3 trillion, an all-time high.
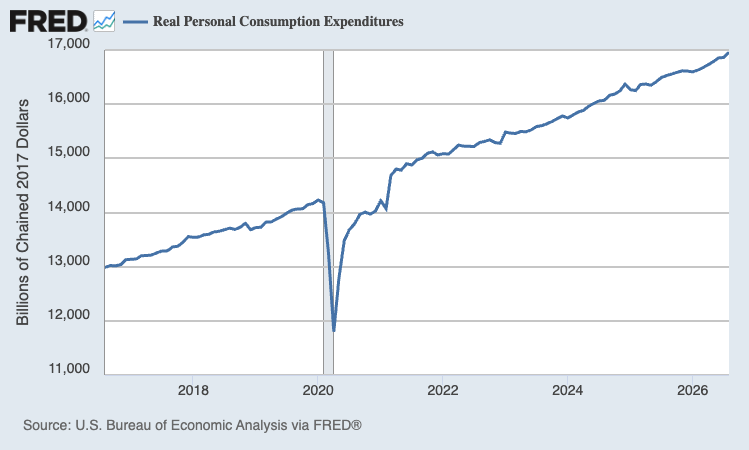
Adjusted for inflation, real personal consumption expenditures was unchanged from the prior month’s all-time high.
Here’s a breakdown of spending growth by category.
💰The personal saving rate is low, but that’s not obviously a bad sign. Personal saving — disposable personal income less personal consumption — has been shrinking over the past two years, causing the personal saving rate — personal saving as a percentage of disposable personal income — to trend lower. In August, the saving rate was 4.1%, its lowest level since Nov. 2022.
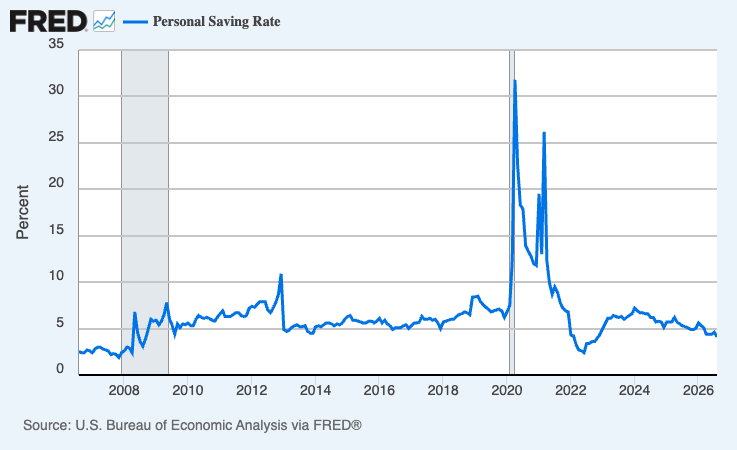
All else equal, this is not great. The implication is that more people are drawing from their savings to support their spending amid inflationary pressures. However, the saving rate tends to decline when net worths are rising. And net worths have been rising, driven by record-high home prices and elevated stock prices.
For more on this dynamic, read: A contrarian note about the falling personal saving rate 💸
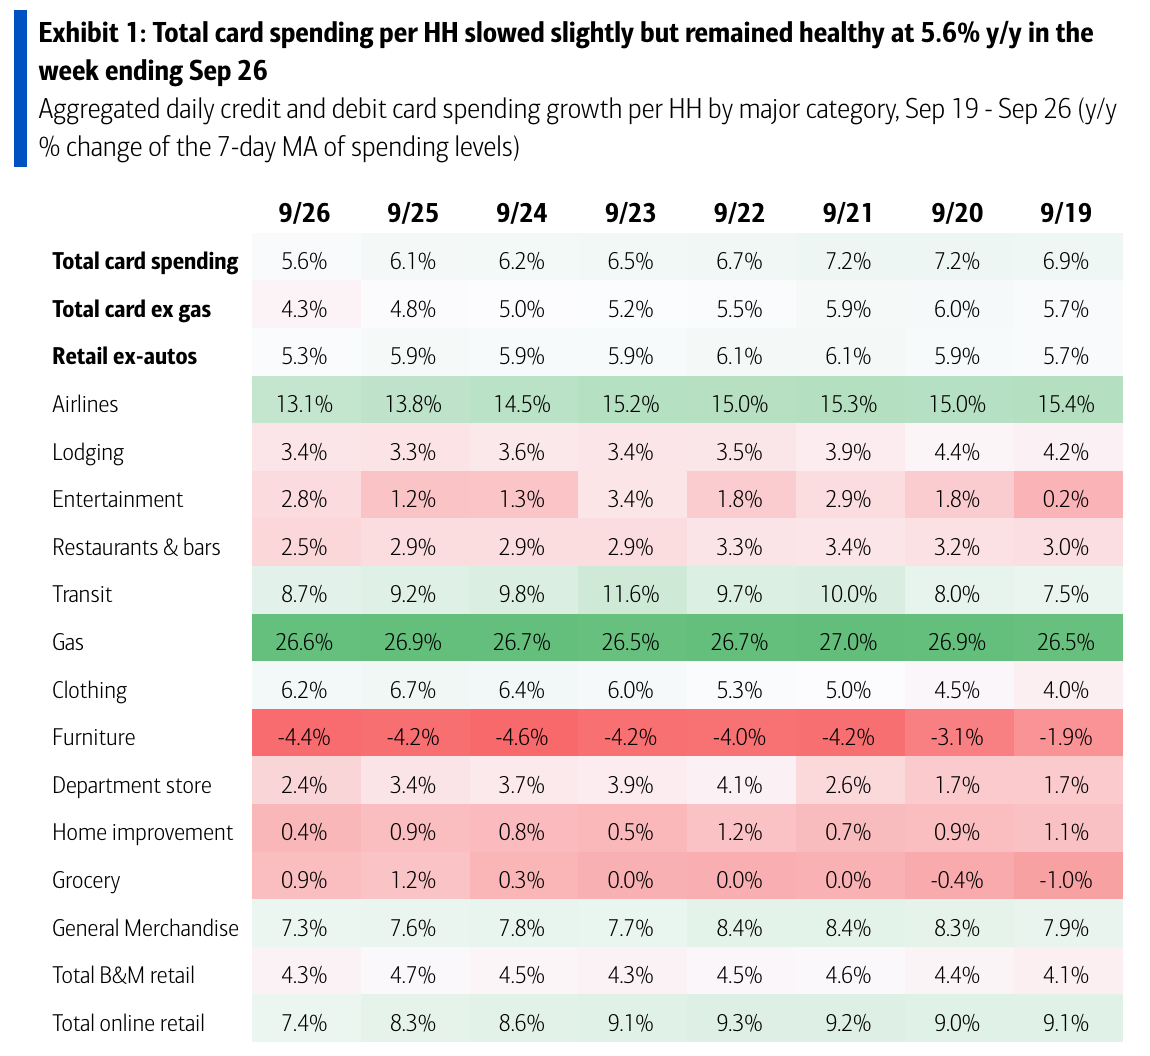
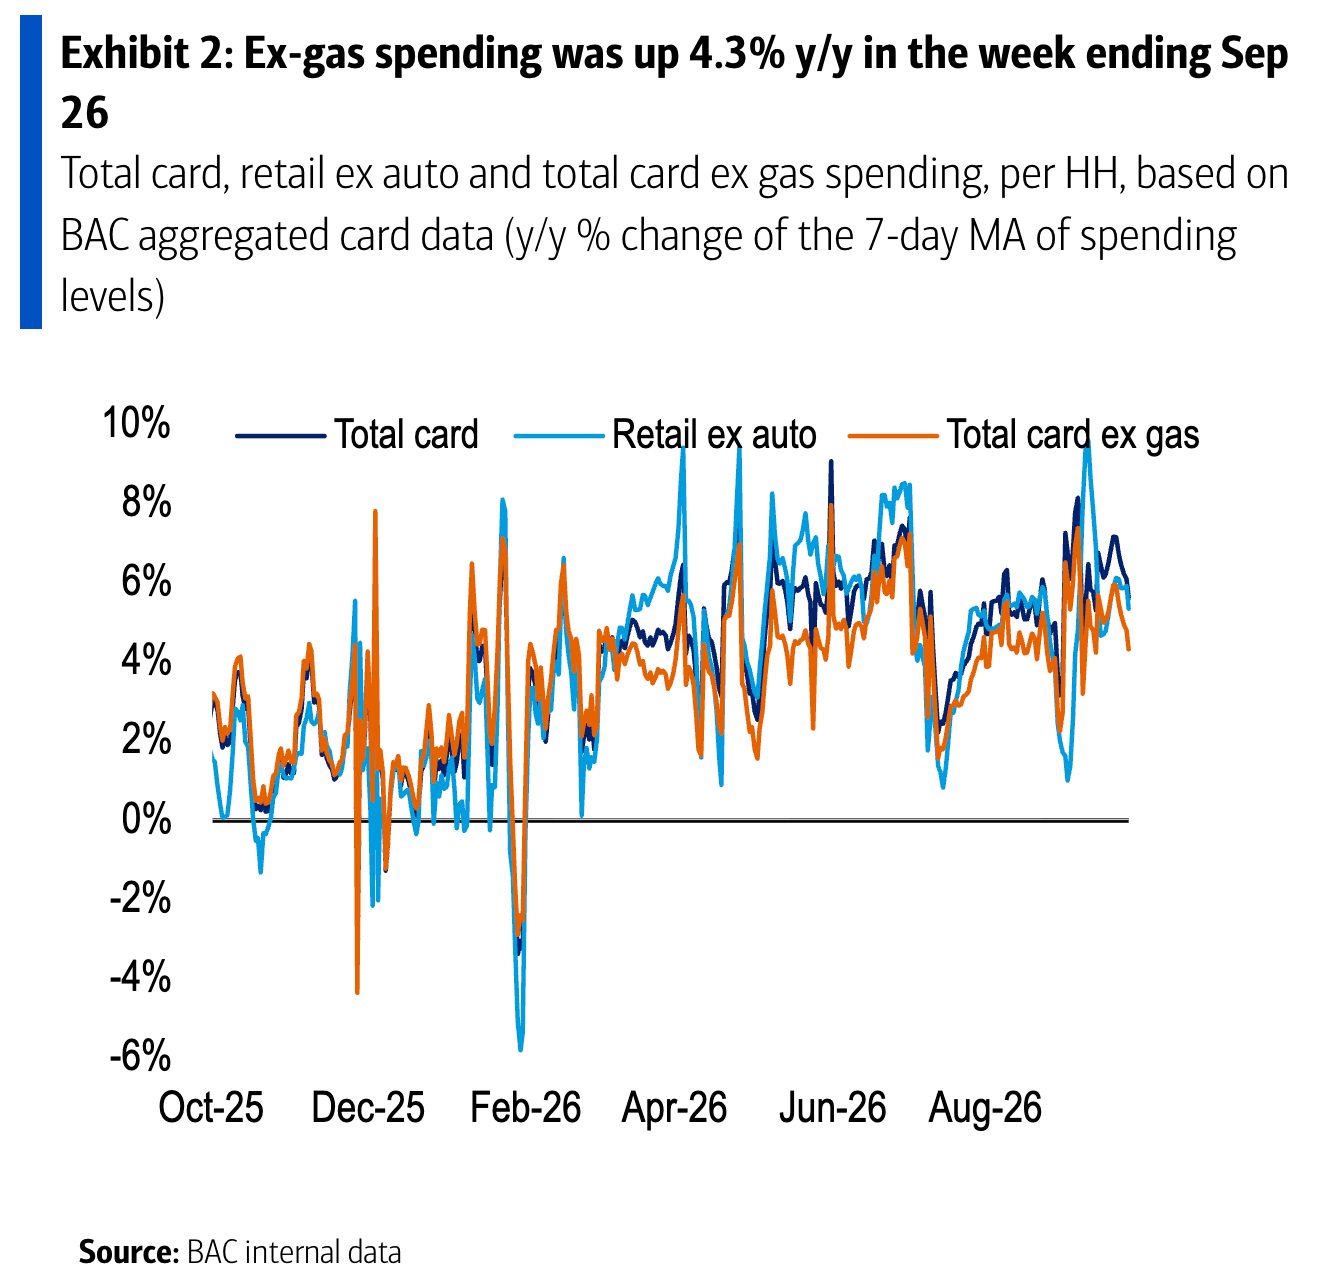
💳 Card spending data is holding up. From BofA: “Total card spending per HH was up 5.6% y/y in the week ending Sep 26, according to BAC aggregated credit & debit card data. Relative to last week, y/y entertainment spending growth increased the most while furniture spending saw the largest decline. After a brief reversal last week, lower-income spending growth again outpaced higher-income in the week ending Sep 26.”
Consumer spending data has looked a lot better than consumer sentiment readings. For more on this contradiction, read: We’re taking that vacation whether we like it or not 🛫 and Household finances are both ‘worse’ and ‘good’ 🌦️
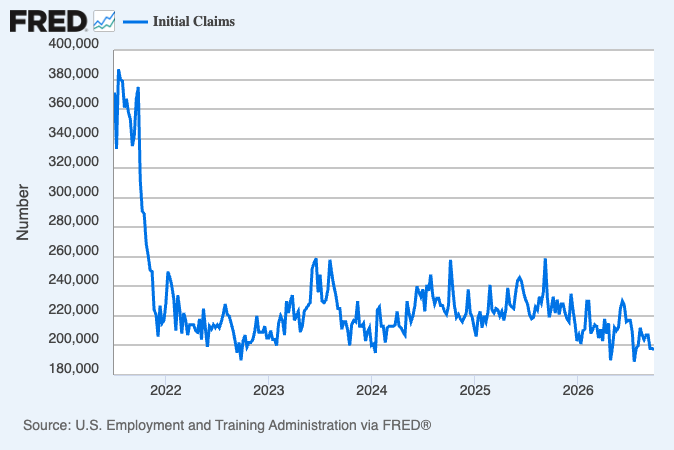
💼 New unemployment insurance claims, total ongoing claims remain low. Initial claims for unemployment benefits ticked down to 197,000 during the week ending Sept. 26, down from 198,000 the week prior. This metric remains at levels historically associated with economic growth.
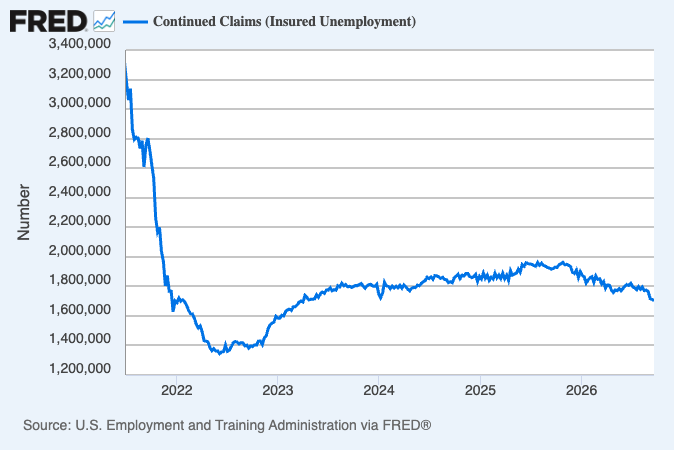
Insured unemployment, which captures those who continue to claim unemployment benefits, ticked down to 1.70 million during the week ending Sept. 19.
For more on the labor market, read: Why mass tech layoffs have little effect on total employment 💾
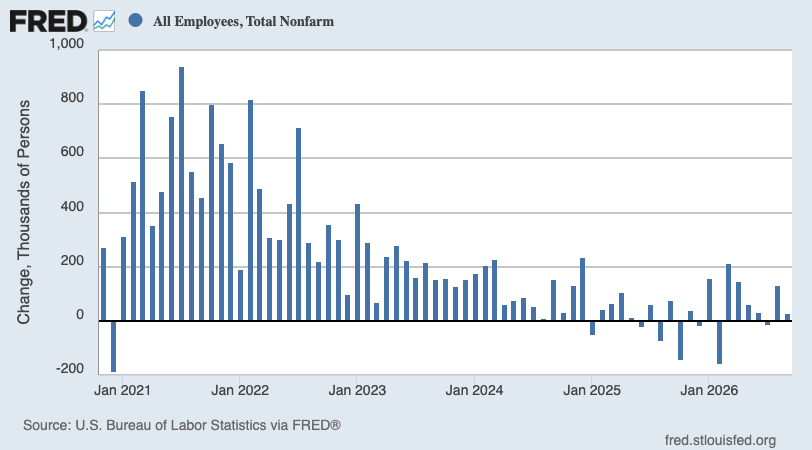
💼 Jobs were created. According to the BLS’s Employment Situation report, U.S. employers added 29,000 jobs in September.
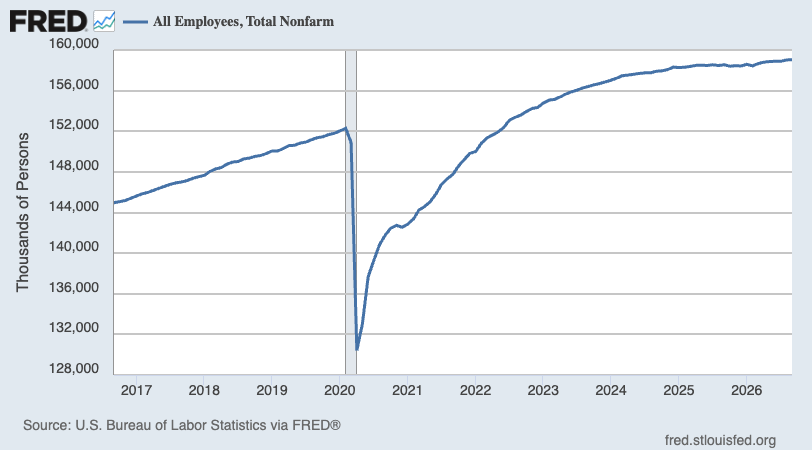
Total payroll employment rose to a record 159.04 million jobs in September.
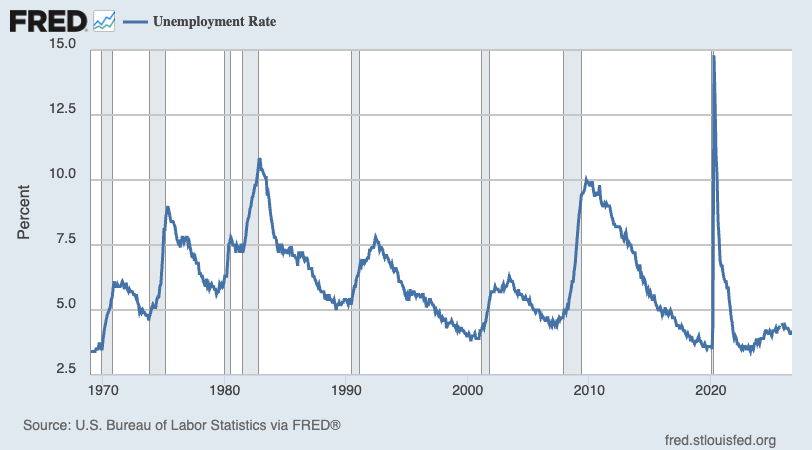
The unemployment rate — that is, the number of workers who identify as unemployed as a percentage of the civilian labor force — ticked up to 4.2% during the month. This was largely driven by entrants into the labor force.
The labor force participation rate — that is, the number of employed and unemployed job seekers as a percentage of the civilian population — ticked up to 61.8% as 485,000 people entered the labor force.
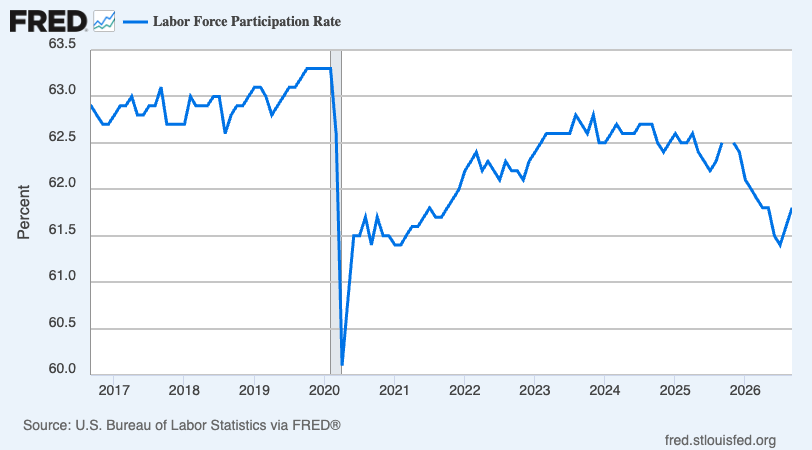
The labor market is in decent shape, but clearly isn’t as hot as it was just a few years ago.
For more on the labor market, read: Things are looking up in the labor market 👍
💸 Wage growth is cooling. Average hourly earnings rose by 0.1% month-over-month in September. On a year-over-year basis, September’s wages were up 3.0%.
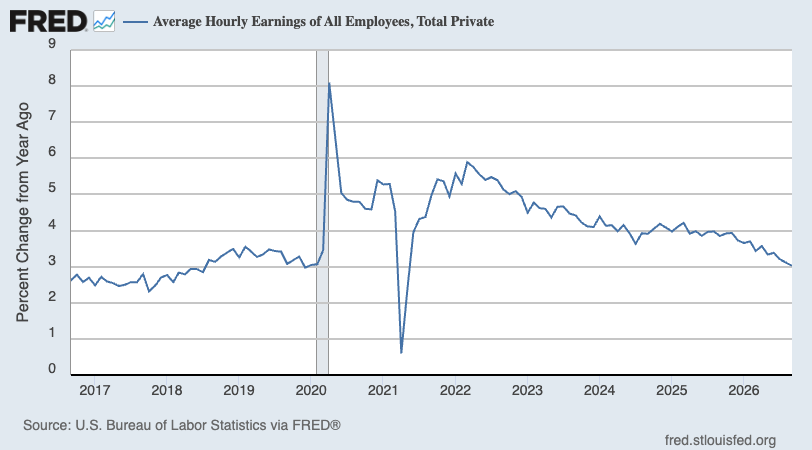
💰 Job switchers still get better pay. According to ADP, annual pay in September for people who changed jobs was up 4.8% from a year ago. That better-pay gap has been widening a bit in recent months. For those who stayed at their job, pay was up 3.0%, about what it’s been for the past year.
For more on why policymakers are watching wage growth, read: Revisiting the key chart to watch amid the Fed’s war on inflation 📈
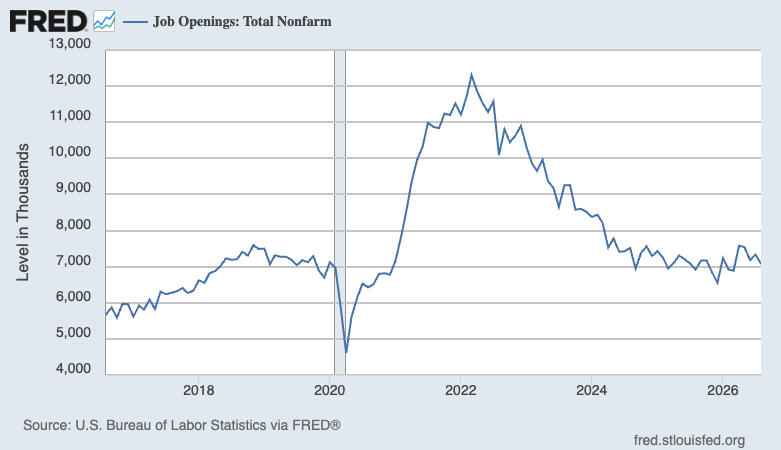
💼 Job openings declined. According to the BLS’s Job Openings and Labor Turnover Survey, employers had 7.08 million job openings in August, down from 7.34 million in July.
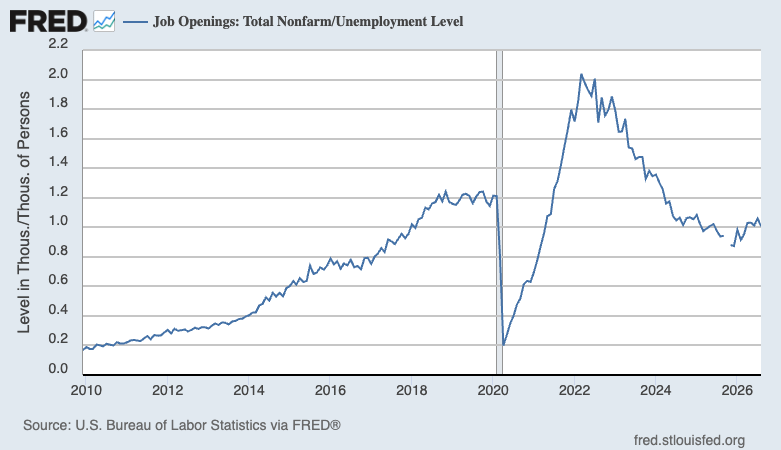
During the month, 7.03 million people were unemployed — meaning there were 1.0 job openings per unemployed person. This remains one of the most straightforward indicators of labor demand. However, this metric has returned to prepandemic levels.
For more on job openings, read: Were there really twice as many job openings as unemployed people? 🤨
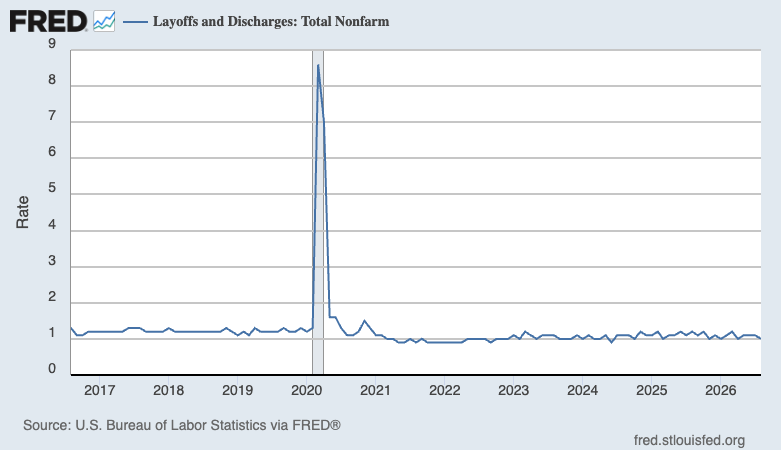
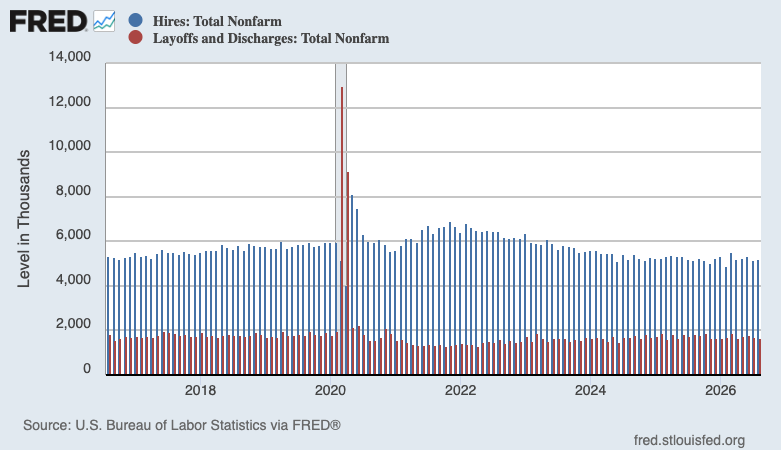
👍 Layoffs remain depressed, hiring remains firm. Employers laid off 1.64 million people in August. While challenging for the people affected, this figure represents just 1.0% of total employment. This metric remains slightly below prepandemic levels.
For more on layoffs, read: Mathematical context can totally change the story 🧮
Hiring activity remains well above layoff activity. During the month, employers hired 5.19 million people.
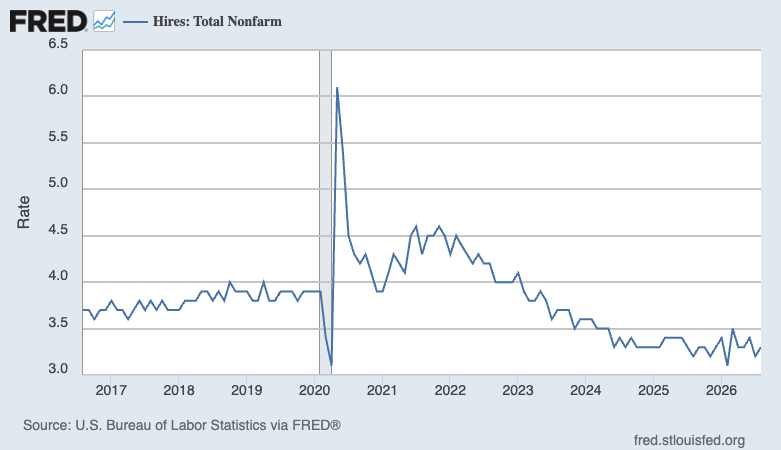
That said, the hiring rate — the number of hires as a percentage of the employed workforce — is relatively low, which could signal trouble ahead in the labor market.
For more on why this metric matters, read: The hiring situation 🧩
🤔 People are quitting less. In August, 3.07 million workers quit their jobs. This represents 1.9% of the workforce. The rate continues to trend below prepandemic levels.
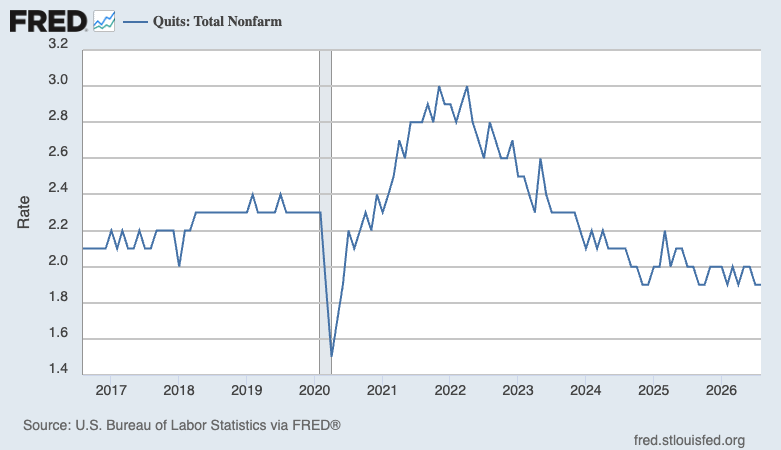
A low quits rate could mean a number of things: more people are satisfied with their job, workers have fewer outside job opportunities, wage growth is cooling, or productivity will improve as fewer people are entering new, unfamiliar roles.
For more on this dynamic, read: The crummy labor market is yielding a ‘tenure dividend’ for corporations 💰
👎 Consumer vibes tumbled. The Conference Board’s Consumer Confidence Index fell by 6.7 points in September. From the report: “The Present Situation Index fell sharply, while the Expectations Index slipped further into negative territory. Consumer appraisals of current business conditions became negative for the first time since September 2024. Perceptions of the current labor market also worsened, though remained within positive territory. Over the next six months, consumers expected both business conditions and the labor market to weaken. Consumers still anticipated their household incomes to rise, but less so compared to previous months.”
More from the report: “On a six-month moving average basis, confidence across all age groups and nearly all income groups trended downward. While higher-income groups remained generally more optimistic, those with a household income of $125,000-$149,000 reported the greatest decline in confidence over the last six months. By generation, confidence for Gen Z, followed by Millennials, remained the highest on a six-month moving average basis. Confidence among the three oldest generations—Generation X, Baby Boomers, and the Silent Generation—continued to weaken. Confidence fell in September across all political affiliations—Democrats, Republicans, and Independents.”
For more on consumer sentiment, read: What consumers do > what consumers say 🙊 and The economy may not be working for everyone right now, but it’s at least working for stock market investors 🎭
👎 Consumers feel worse about the labor market. From The Conference Board: “Consumers’ views of the labor market softened in September: 23.6% of consumers said jobs were ‘plentiful,’ down from 24.5% in August. 21.9% of consumers said jobs were ‘hard to get,’ up from 20.3%.”
Many economists monitor the spread between these two percentages (a.k.a., the labor market differential). The direction of the spread reflects a cooling sentiment toward the labor market.
More from The Conference Board: “Consumers were also more negative about the labor market outlook in September: 14.0% of consumers expected more jobs to be available, down from 14.8% in August. 28.4% expected fewer jobs, up from 26.1%.“
For more on the labor market, read: Things are looking up in the labor market 👍
🏠 Mortgage rates rise. According to Freddie Mac, the average 30-year fixed-rate mortgage rose to 7.28%, up from 7.03% last week. This is the highest average rate since Nov. 2023.
As of Q2, there were 149.5 million housing units in the U.S., of which 87.0 million were owner-occupied and about 40% were mortgage-free. Of those carrying mortgage debt, almost all have fixed-rate mortgages, and most of those mortgages have rates that were locked in before rates surged from 2021 lows. All of this is to say: Most homeowners are not particularly sensitive to the weekly movements in home prices or mortgage rates.
For more on mortgages and home prices, read: Why home prices and rents are creating all sorts of confusion about inflation 😖
🏠 Home prices rose. According to the S&P CoreLogic Case-Shiller index, home prices were up 1.9% year-over-year in July and 1.6% month-over-month. From S&P Dow Jones Indices’ Rebecca Kaufman: “While home prices continued to decline in real terms in July 2026, marking the 14th consecutive month of real declines, slightly lower inflation and stronger nominal home price appreciation helped narrow the gap.”
For more on how home prices and how they may be affecting the economy, read: A contrarian note about the falling personal saving rate…💸
📋 Manufacturing activity surveys signal growth, but also challenges. From S&P Global’s September U.S. Manufacturing PMI: “September has seen the pace of US manufacturing growth pick up a gear again, the PMI lifting to its highest since May 2022 as a surge in new orders encouraged factories to lift output sharply higher and take on workers in increasing numbers. Order book backlogs are rising and suppliers are increasingly busy, pointing to stretched capacity as companies struggle to meet demand across both consumer-facing and business sectors. This is most notable in the investment and production of machinery and equipment, linked in many cases to rising AI-related spend. Safety stock building amid price and supply chain worries also continues to support demand, though the ongoing loss of export orders remains a disappointment. While sending an encouraging signal for further growth of manufacturing capacity in the coming months, the indication that demand is outstripping supply also means inflationary pressures remain a key area of concern, especially amid high oil prices.”
Similarly, the ISM September Manufacturing PMI signaled growth.
The ISM survey also signaled inflation.
Keep in mind that during times of perceived stress, soft survey data tends to be more exaggerated than actual hard data.
For more on this, read: What businesses do > what businesses say 🙊 and 4 sometimes-conflicting ways I’m thinking about the economy 😬😞😎🙃
🏭 Business investment activity rose. Orders for nondefense capital goods excluding aircraft — a.k.a. core capex or business investment — increased 1.6% in August to a record $87.6 billion.
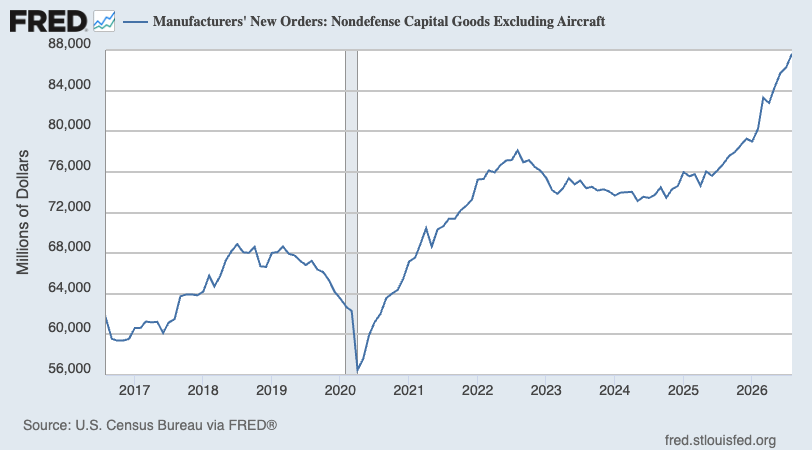
Core capex orders are a leading indicator, meaning they foretell economic activity down the road.
📈 Near-term GDP growth estimates are tracking positively. The Atlanta Fed’s GDPNow model sees real GDP growth rising at a 3.7% rate in Q3.
For more on GDP and the economy, read: It’s too ambiguous to just say ‘the economy’ 🤦🏻♂️ and Economic data can often be both ‘worse’ and ‘good’ 🌦️
Earnings look bullish: The long-term outlook for the stock market remains favorable, bolstered by expectations for years of earnings growth. And earnings are the most important driver of stock prices.
Demand is positive: Demand for goods and services remains positive, supported by healthy consumer and business balance sheets. Personal spending activity remains at record levels. Core capex orders, which are a leading indicator of business spending, have been trending higher.
Growth rates have cooled: While the economy remains healthy, growth has normalized from much hotter levels earlier in the cycle. The economy is less “coiled” these days as major tailwinds like job openings and excess savings have faded. Job creation, while positive, is not as hot as it used to be. It has become harder to argue that growth is destiny.
Actions speak louder than words: We are in an odd period, given that the hard economic data decoupled from the soft sentiment-oriented data. Consumer and business sentiment has been relatively poor, even as tangible consumer and business activity continues to grow and trend at record levels. From an investor’s perspective, what matters is that the hard economic data continues to hold up.
Stocks are not the economy: There’s a case to be made that the U.S. stock market could outperform the U.S. economy in the near term, thanks largely to positive operating leverage. Since the pandemic, companies have aggressively adjusted their cost structures. This came with strategic layoffs and investment in new equipment, including hardware powered by AI. These moves are resulting in positive operating leverage, which means a modest amount of sales growth — in the cooling economy — is translating to robust earnings growth.
Mind the ever-present risks: Of course, we should not get complacent. There will always be risks to worry about, such as U.S. political uncertainty, geopolitical turmoil, energy price volatility, and cyber attacks. There are also the dreaded unknowns. Any of these risks can flare up and spark short-term volatility in the markets.
Investing is never a smooth ride: There’s also the harsh reality that economic recessions and bear markets are developments that all long-term investors should expect as they build wealth in the markets. Always keep your stock market seat belts fastened.
Think long-term: For now, there’s no reason to believe there’ll be a challenge that the economy and the markets won’t overcome. The long game remains undefeated, and it’s a streak that long-term investors can expect to continue.
For more on how the macro story is evolving, check out the previous review of the macro crosscurrents. »
Here’s a roundup of some of TKer’s most talked-about paid and free newsletters about the stock market. All of the headlines are hyperlinked to the archived pieces.
The stock market can be an intimidating place: It’s real money on the line, there’s an overwhelming amount of information, and people have lost fortunes in it very quickly. But it’s also a place where thoughtful investors have long accumulated a lot of wealth. The primary difference between those two outlooks is related to misconceptions about the stock market that can lead people to make poor investment decisions.
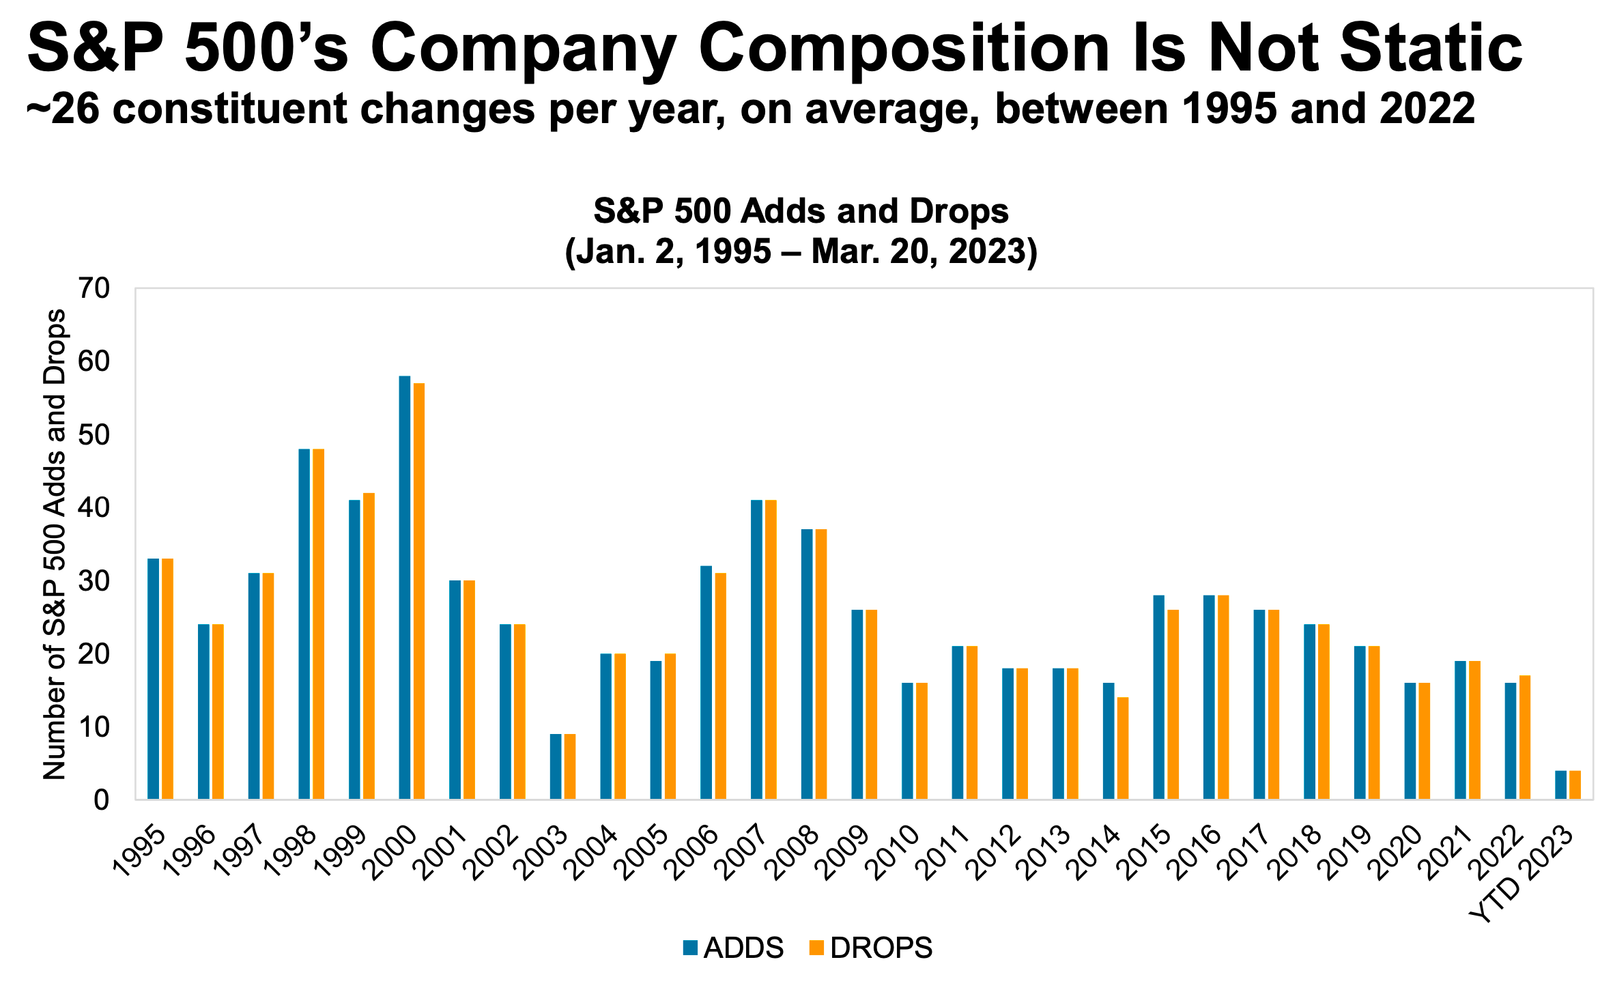
Passive investing is a concept usually associated with buying and holding a fund that tracks an index. And no passive investment strategy has attracted as much attention as buying an S&P 500 index fund. However, the S&P 500 — an index of 500 of the largest U.S. companies — is anything but a static set of 500 stocks.
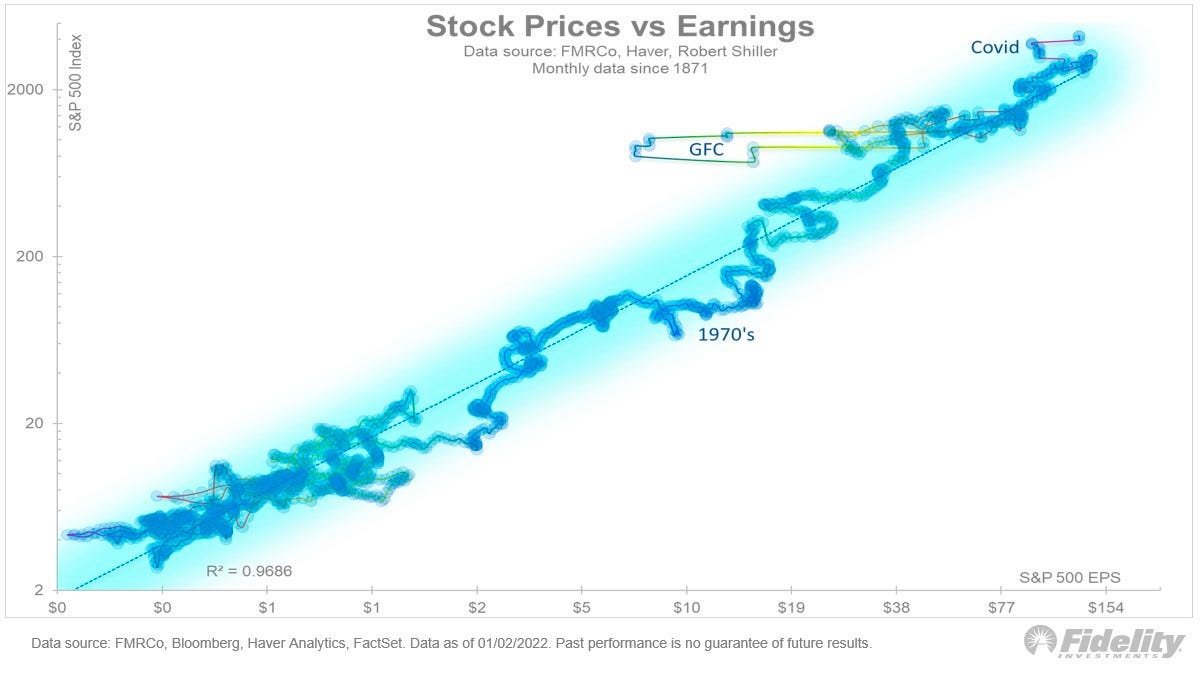
For investors, anything you can ever learn about a company matters only if it also tells you something about earnings. That’s because long-term moves in a stock can ultimately be explained by the underlying company’s earnings, expectations for earnings, and uncertainty about those expectations for earnings. Over time, the relationship between stock prices and earnings has a very tight statistical relationship.
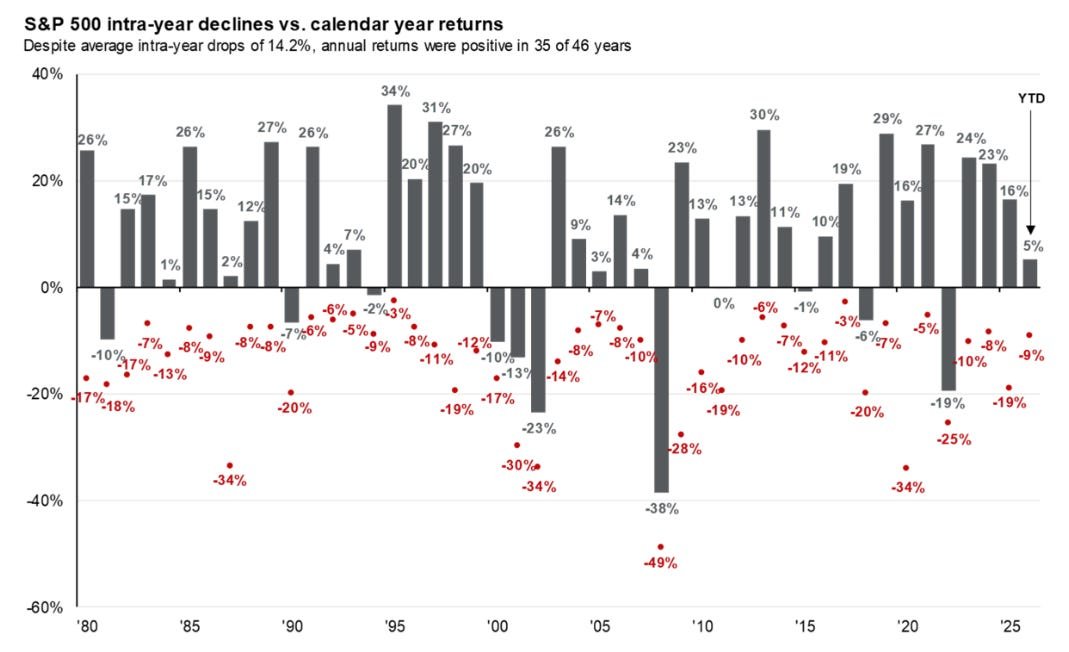
Investors should always be mentally prepared for some big sell-offs in the stock market. It’s part of the deal when you invest in an asset class that is sensitive to the constant flow of good and bad news. Since 1950, the S&P 500 has seen an average annual max drawdown (i.e., the biggest intra-year sell-off) of 14%.
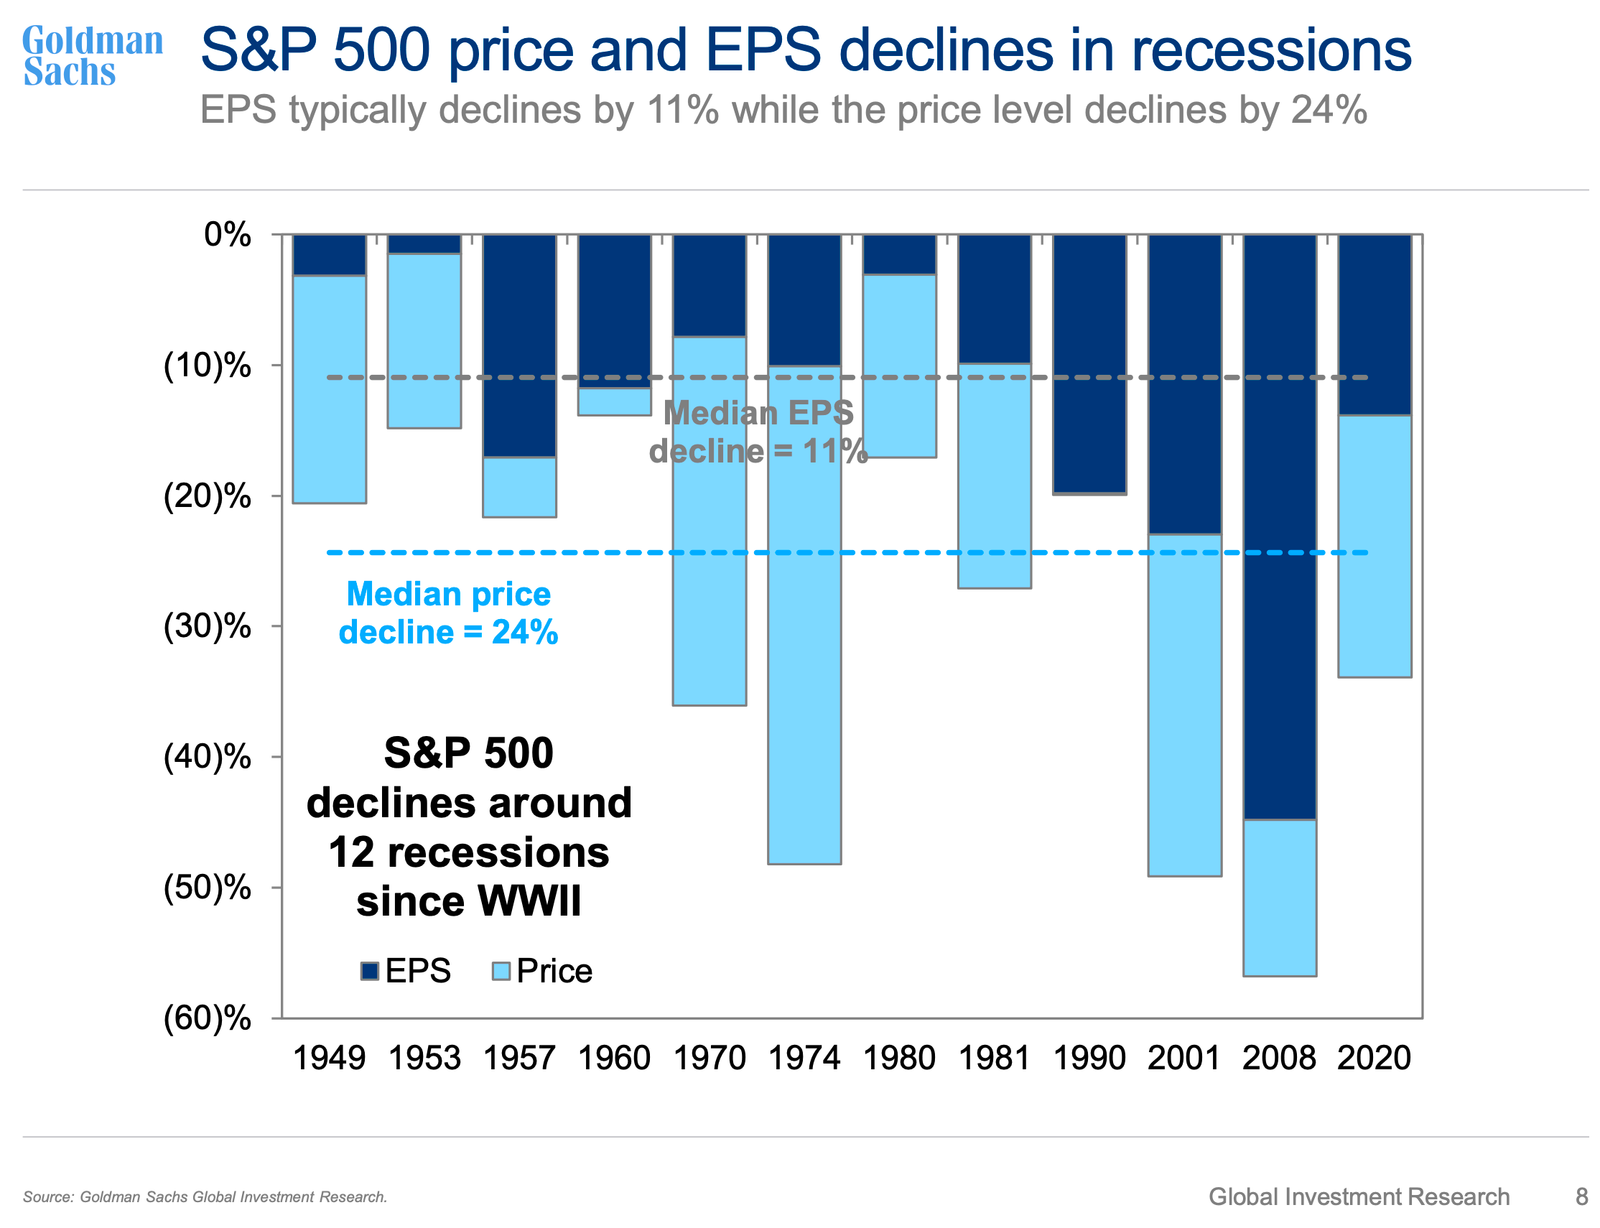
Every recession in history was different. And the range of stock performance around them varied greatly. There are two things worth noting. First, recessions have always been accompanied by a significant drawdown in stock prices. Second, the stock market bottomed and inflected upward long before recessions ended.
Since 1928, the S&P 500 has generated a positive total return more than 89% of the time over all five-year periods. Those are pretty good odds. When you extend the timeframe to 20 years, you’ll see that there’s never been a period where the S&P 500 didn’t generate a positive return.
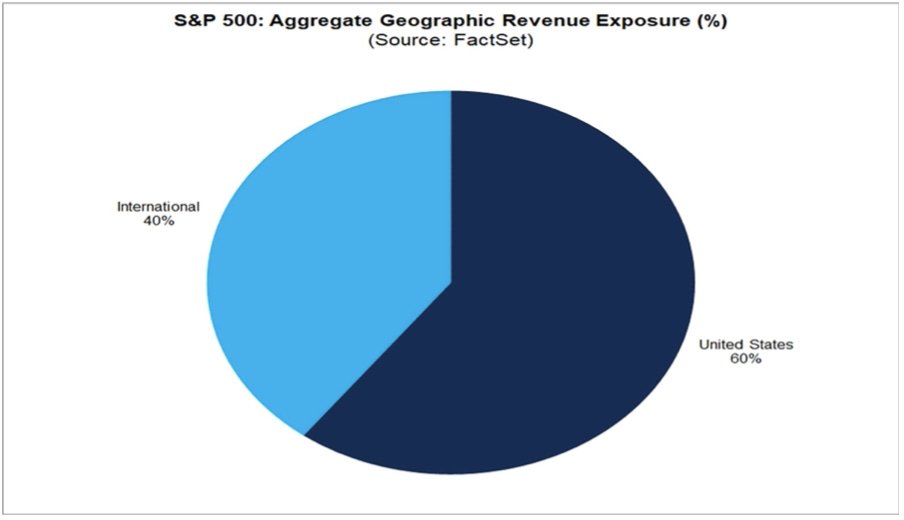
While a strong dollar may be great news for Americans vacationing abroad and U.S. businesses importing goods from overseas, it’s a headwind for multinational U.S.-based corporations doing business in non-U.S. markets.
…you don’t want to buy them when earnings are great, because what are they doing when their earnings are great? They go out and expand capacity. Three or four years later, there’s overcapacity and they’re losing money. What about when they’re losing money? Well, then they’ve stopped building capacity. So three or four years later, capacity will have shrunk and their profit margins will be way up. So, you always have to sort of imagine the world the way it’s going to be in 18 to 24 months as opposed to now. If you buy it now, you’re buying into every single fad every single moment. Whereas if you envision the future, you’re trying to imagine how that might be reflected differently in security prices.
Some event will come out of left field, and the market will go down, or the market will go up. Volatility will occur. Markets will continue to have these ups and downs. … Basic corporate profits have grown about 8% a year historically. So, corporate profits double about every nine years. The stock market ought to double about every nine years… The next 500 points, the next 600 points — I don’t know which way they’ll go… They’ll double again in eight or nine years after that. Because profits go up 8% a year, and stocks will follow. That’s all there is to it.
Long ago, Sir Isaac Newton gave us three laws of motion, which were the work of genius. But Sir Isaac’s talents didn’t extend to investing: He lost a bundle in the South Sea Bubble, explaining later, “I can calculate the movement of the stars, but not the madness of men.” If he had not been traumatized by this loss, Sir Isaac might well have gone on to discover the Fourth Law of Motion: For investors as a whole, returns decrease as motion increases.
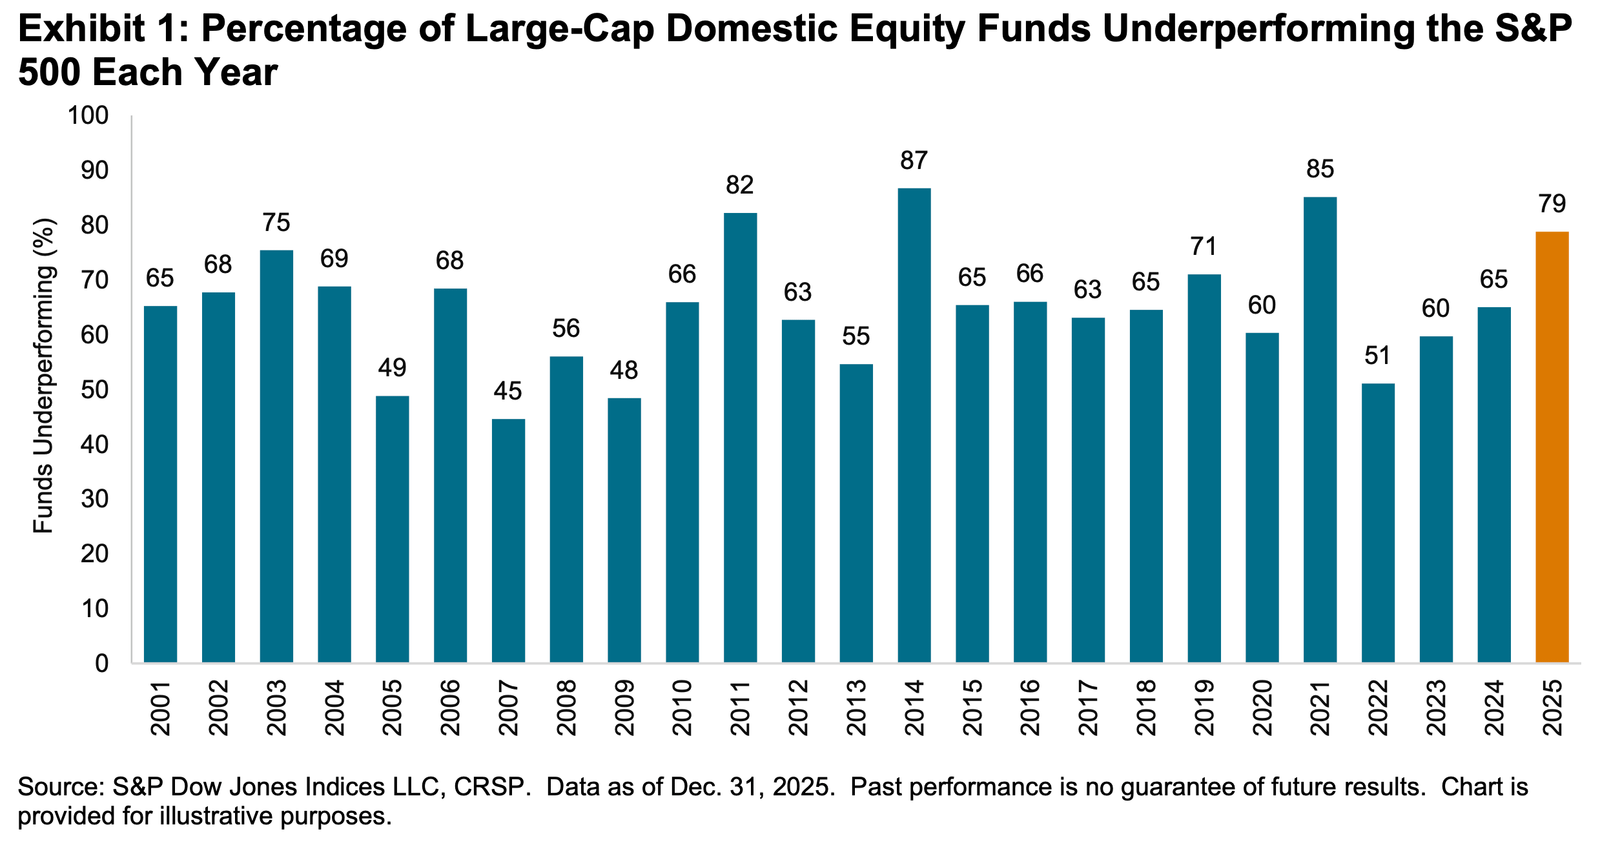
According to S&P Dow Jones Indices (SPDJI), 79% of U.S. large-cap equity fund managers underperformed the S&P 500 in 2025. As you stretch the time horizon, the numbers get even more dismal. Over three years, 67% underperformed. Over 5 years, 89% underperformed. And over 20 years, 93% underperformed. This 2025 performance was the 16th consecutive year in which the majority of fund managers in this category have lagged the index.
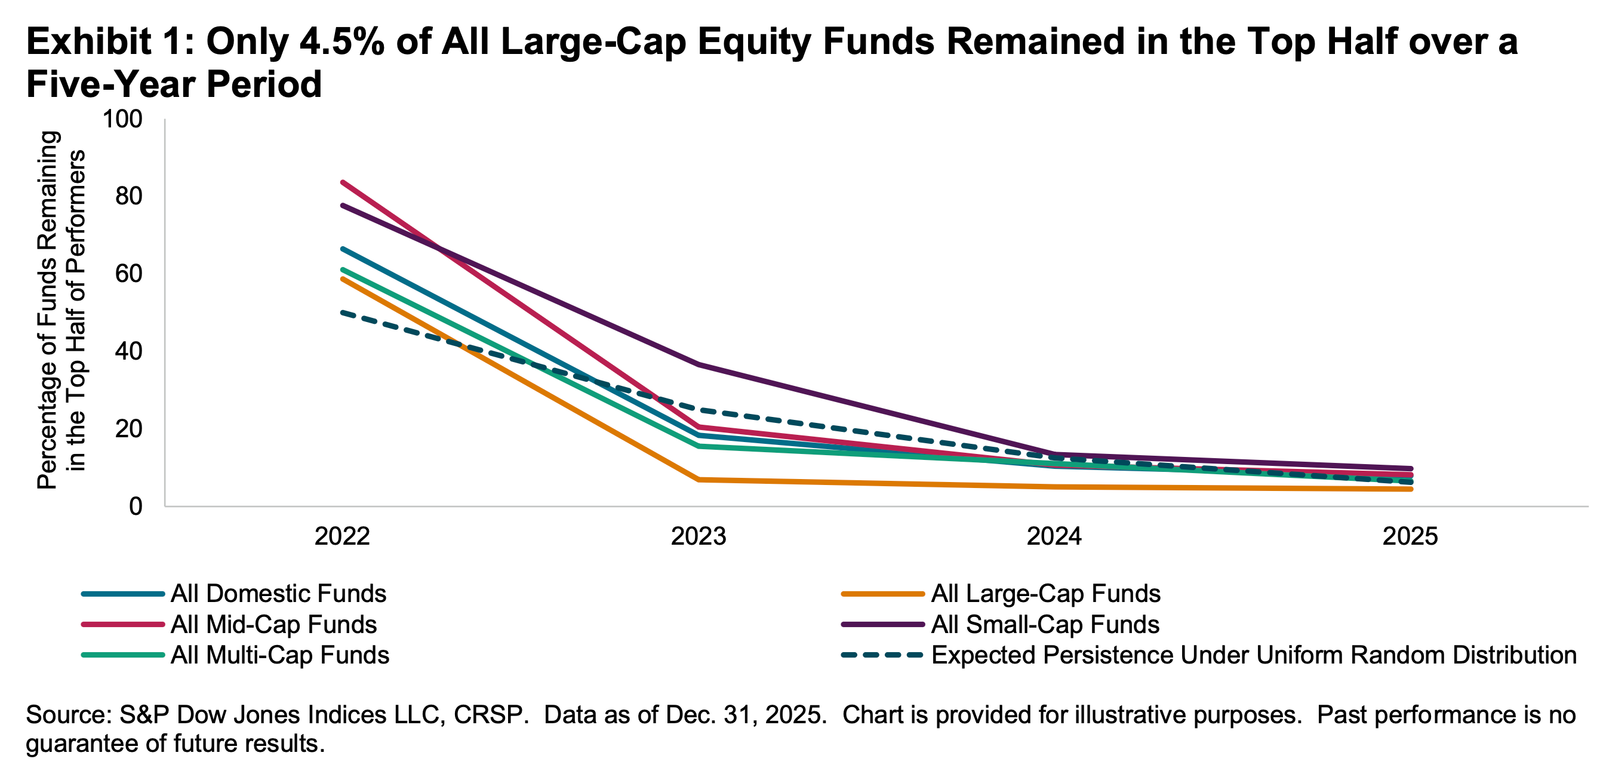
Even if you are a fund manager who generated industry-leading returns in one year, history says it’s an almost insurmountable task to stay on top consistently in subsequent years. According to S&P Dow Jones Indices, of the 334 large-cap equity funds in the top half of performance in 2021, 58.7% remained at the top half in 2022. However, just 6.9% remained on top through 2023. Only 4.5% stayed on top in the five consecutive years through 2025.
It’s much more dismal when you raise the bar. Of the 164 large-cap equity funds in the top quartile in 2021, just 20.1% remained in that category in 2022. That percentage fell to literally 0.0% in 2023.
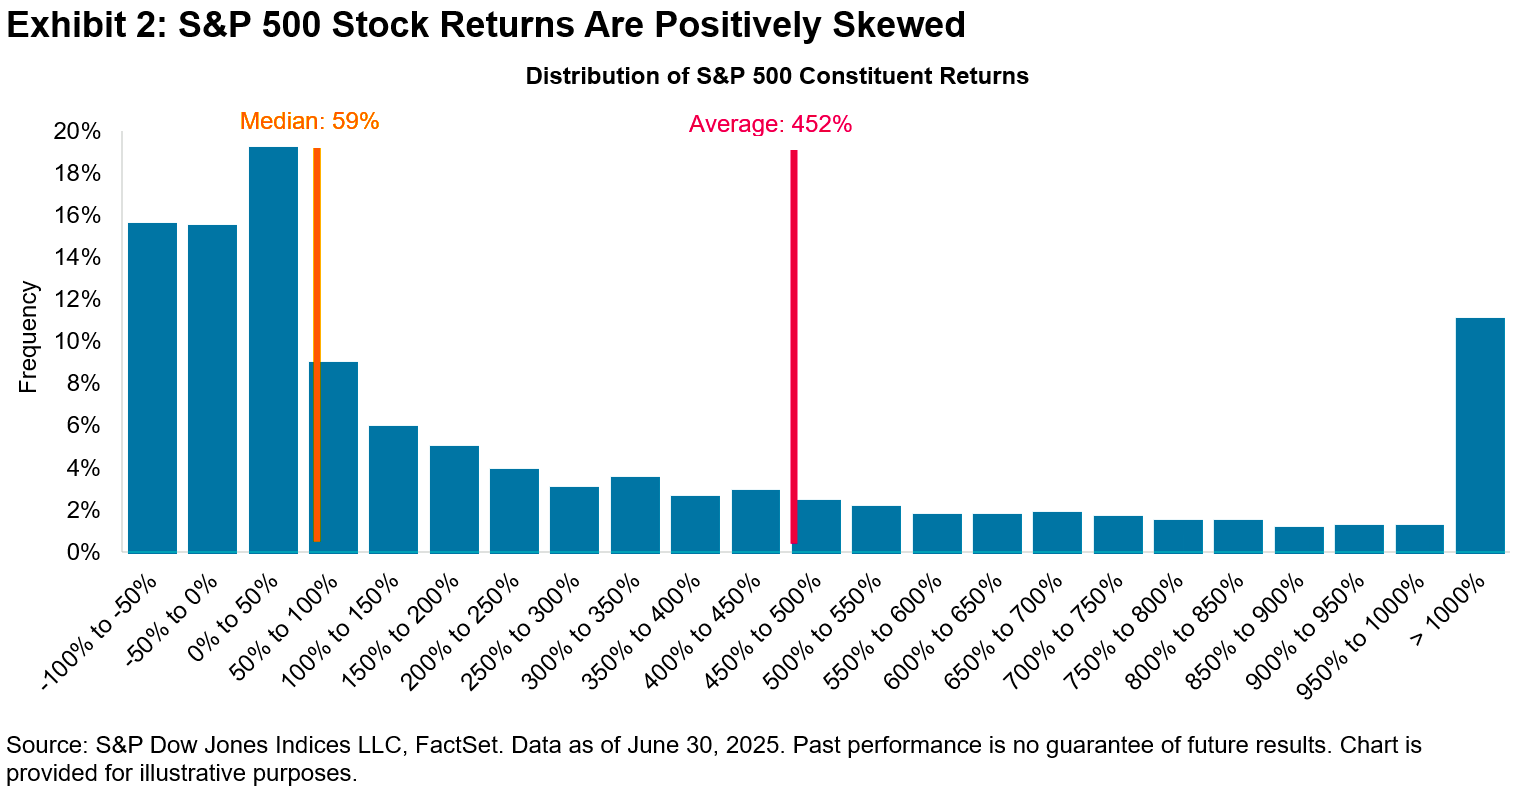
Picking stocks in an attempt to beat market averages is an incredibly challenging and sometimes money-losing effort. Most professional stock pickers aren’t able to do this consistently. One of the reasons for this is that most stocks don’t deliver above-average returns. According to S&P Dow Jones Indices, only 19% of the stocks in the S&P 500 outperformed the average stock’s return from 2001 to 2025. Over this period, the average return on an S&P 500 stock was 452%, while the median stock rose by just 59%.