Earlier this year, the S&P 500’s cyclically adjusted price-to-earnings ratio, better known as the CAPE ratio, reached 41.4. This might not sound scary all by itself, but consider that in more than 150 years, the CAPE ratio has exceeded 40 only one other time, and that was at the market’s 1999 peak before the dot-com bubble burst. Not even in the speculative mania that led to the Great Depression, or during the 2021 IPO bubble, did it reach this level. But it’s been over 40 continuously since May.
Of course, just because a metric reaches a certain level doesn’t mean the market is going to do anything in particular. After all, expensive markets can keep getting more expensive for years. But here’s a look at what happened last time the CAPE ratio broke through 40, and what might be different about this time.
Missed AI’s “Act 1”? Act 2 Could Be 14x Bigger. Most investors think they missed the AI boat because they didn’t buy Nvidia in 2005. But according to our analysts, we’re only at the end of “Act 1″—the R&D phase. “Act 2” is the global rollout. Continue »
Man looking at financial charts on a screen. Image source: Getty Images.
The last time the CAPE ratio was this high
First, a bit of context. The CAPE ratio was developed by economist Robert Shiller and compares stock prices to the average of the past 10 years’ earnings, adjusted for inflation. The goal is to look at earnings throughout the business cycle, so a particularly strong or weak earnings result doesn’t distort the valuation much.
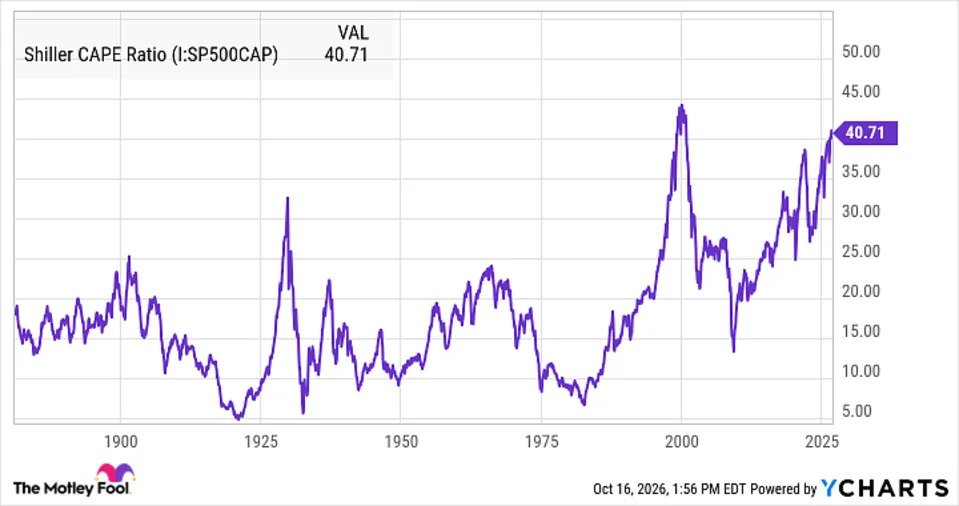
Historical chart of Shiller CAPE ratio. Image source: yCharts.
Throughout history, the S&P 500’s CAPE has averaged about 17. It peaked at 44 in December 1999, the only time it has been higher than the current level.
What happened next? The S&P 500 finished in the red in each of the next three years: 2000, 2001, and 2002, losing about half of its value from peak to trough. Investors who bought the S&P 500 at the CAPE ratio’s peak would have achieved a slightly negative total return over the next decade, which is historically rare.
Is this time different?
There’s an old saying that the worst thing you can hear as an investor is “this time is different,” but there is a reasonable argument that it could be.
For one thing, today’s largest companies are far more profitable than the average company was at the 1999 peak. Plus, there are many highly profitable businesses with asset-light models and high profit margins, and earnings have grown rather quickly.
On the other hand, it’s entirely possible for margins to shrink, AI spending to decline, and other factors that could cause a major valuation reset in the market.