What is driving Bloom Energy Corp (BE)’s stock price up today?
Bloom Energy experienced strong buying momentum driven by a major Wall Street analyst upgrade and a key clean-technology partnership announcement. Barclays raised its rating on the fuel cell manufacturer to Overweight, citing an accelerating demand curve for solid-oxide fuel cell servers, rapid accumulation of customer deposits, and substantial long-term supply commitments extending through 2029. Complementing this analyst endorsement, the company announced a non-binding memorandum of understanding with California Resources Corporation and its carbon management division, Carbon TerraVault, to evaluate building over one gigawatt of fuel cell power generation integrated with carbon capture and underground storage. This prospective project directly addresses power capacity constraints for utility, municipal, and data center customers.
The broader narrative surrounding Bloom Energy continues to be anchored by the surging power requirements of artificial intelligence infrastructure and hyperscale data centers. Local grid interconnection delays and utility capacity bottlenecks have positioned on-site power generation solutions as critical enablers for technology companies seeking rapid deployment. This macro trend was reaffirmed by the company’s recent third-quarter financial results, which featured triple-digit year-over-year revenue growth, expanded operating margins, and a third consecutive upward revision to full-year revenue and profitability guidance. The combination of strong execution in hardware shipments and expanding commercial interest reinforces investor confidence in Bloom Energy’s role within the digital energy ecosystem.
Despite positive operational momentum, institutional market participants remain focused on working capital dynamics and cash conversion timelines. The rapid scaling of manufacturing capacity and inventory buildup prior to milestone billings recently created free cash flow headwinds, contributing to short-term share price consolidation before the current rebound. However, the confluence of accelerating customer commitments, high-profile clean energy collaborations, and favorable Wall Street recommendations has restored bullish market sentiment. Investors will closely monitor the conversion of non-binding agreements into formal commercial contracts and the timing of cash collections as key indicators for sustained performance.
Technical Analysis of Bloom Energy Corp (BE)
Technically, Bloom Energy Corp (BE) shows a MACD (12,26,9) value of -4.452, indicating a sell signal. The RSI at 43.776 suggests neutral condition and the Williams %R at 53.399 suggests neutral condition. Please monitor closely.
Media Coverage of Bloom Energy Corp (BE)
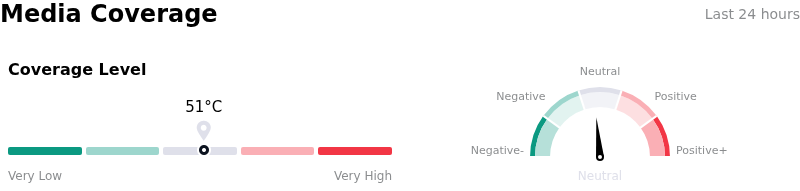
In terms of media coverage, Bloom Energy Corp (BE) shows a coverage score of 51, indicating a moderate level of media attention. The overall market sentiment index is currently in neutral zone.
Fundamental Analysis of Bloom Energy Corp (BE)
Bloom Energy Corp (BE) is in the Industrial Goods industry. Its latest annual revenue is $2.02B, ranking 78 in the industry. The net profit is $-88.43M, ranking 210 in the industry. Company Profile
Over the past month, multiple analysts have rated the company as Buy, with an average price target of $280.50, a high of $354.00, and a low of $98.94.
More details about Bloom Energy Corp (BE)
Company Specific Risks:
- Negative Free Cash Flow and Working Capital Drag: Despite strong Q3 revenue beat, Bloom Energy reported negative cash flow from operations of $27 million and negative free cash flow of $181 million. Capital remains heavily tied up in unbilled contract assets ($858.6 million) and expanding inventories and receivables, driving institutional anxiety regarding cash conversion efficiency.
- Extreme Customer Concentration Risk: The business model exhibits heavy reliance on a small cluster of buyers, with the top two customers alone accounting for approximately 69% of total Q3 revenue. This high concentration leaves future top-line stability vulnerable to capital expenditure pauses or deployment delays from key hyperscalers.
- Customer Incentive Dilution and Unit Economics Concerns: Profitability face headwinds from massive customer consideration assets, including over $306 million tied to warrants and financial incentives for hyperscaler anchor clients like Oracle. Analysts caution that high servicing costs and expensive hardware incentives raise questions about long-term unit economics once temporary grid power shortages ease.
- Elevated Valuation Multiples and Analyst Downgrades: With forward valuation multiples expanded to roughly 60x–74x earnings, recent Wall Street analyst downgrades to Hold ratings sparked heightened option implied volatility (IV30 near 88.9%) and profit-taking, leaving the stock vulnerable to further multiple compression if growth normalizes.
This article may include AI-generated content that is human-reviewed, which is for reference and general information purposes only and does not constitute investment advice.
Disclaimer: The information provided on this website is for educational and informational purposes only and should not be considered financial or investment advice.