Chris Lange
8 min read
Quick Read
-
Altria (MO) and British American Tobacco (BTI) fund dividends yielding about 5.5% or more through price increases and fast-growing nicotine pouches despite shrinking cigarette volumes.
-
Altria’s 61st dividend increase in 57 years makes it a Dividend King, with earnings covering the payout and leverage near 2x.
-
BAT trades at a cheaper valuation with faster smokeless growth, but US holders absorb currency swings and litigation risk in every quarterly check.
-
Building a portfolio and living off one are two completely different skills, and almost nobody teaches the second. This problem is what The Definitive Guide to Retirement Income helps, and it is free today. Read more here. (Sponsor)
Cigarette volumes keep shrinking, but shareholder payouts keep growing. Altria (NYSE:MO) and British American Tobacco (NYSE:BTI) both fund rising dividends with pricing power and fast-growing nicotine pouches, and at current prices each pays a forward yield of about 5.5% or better. That sits below the 6% ultra-high-yield line, but both still deliver healthy income from large, established businesses. The question for income investors is whether price increases and smoke-free products can keep paying for those dividends while the core business declines.
Altria
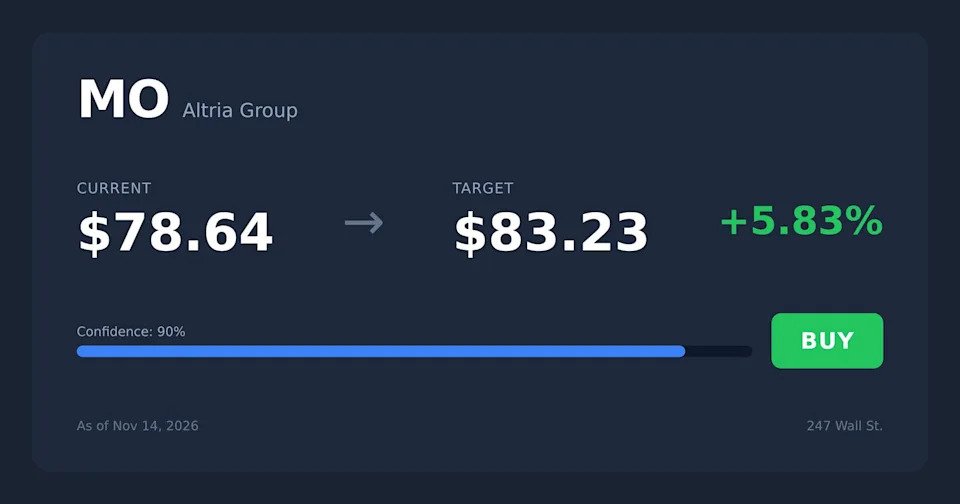
Altria pays $1.11 per share each quarter, an annualized $4.44. With the stock at $78.65, that works out to a forward yield of about 5.65%. Shares are up 43.02% year to date, so new buyers lock in a lower yield than shareholders who bought in January. Even so, new buyers still collect a forward yield above 5%.
Dividend Safety: Covered by Earnings, Backed by Decades of Raises
Full-year adjusted diluted EPS guidance was raised to $5.66 to $5.74, representing 4.5% to 6.0% growth. The $4.44 annual dividend uses about 77% to 78% of that range. That is a high payout ratio, but it is normal for a mature business that has little need for heavy reinvestment.
——
Now Available: The Definitive Guide to Retirement Income
Many successful investors eventually reach the same moment. The saving is done, the portfolio is built, and the question quietly changes from how much can I grow this to how much can I take out? Get that second question wrong and decades of good investing can come apart in a handful of years.
That is exactly what The Definitive Guide to Retirement Income helps answer. It covers what your retirement could actually cost, which income sources are worth using, and the withdrawal math that decides whether the money lasts. It is free today from Fisher Investments. Read More Here ›