Chris Lange
5 min read
Quick Read
-
EPD yields 6.2% versus WMB’s 3.0% and has raised its distribution for 27 consecutive years, including through Williams’ painful 2016 dividend cut.
-
Williams’ corporate structure delivers simple 1099-DIV tax reporting with no IRA penalty risk, while its 11%-plus EBITDA growth target rewards patient long-horizon investors.
-
Just released. Our analysts combed the entire stock market and named the ten best stocks to buy right now, and Enterprise Products Partners made the cut. Enter your email to see the other nine names and why EPD earned its spot. The report is free. Enter your email and see the full list.
How does a retirement-focused investor compare Enterprise Products Partners (NYSE:EPD) or Williams Companies (NYSE:WMB) right now? Both pipeline giants posted strong second-quarter 2026 results, but they pay retirees very differently. Enterprise offers a forward yield of about 6.2%. Williams yields about 3.0% and is spending heavily on faster growth. Here is how they compare on the three measures that matter most for income.
Yield and Income: Enterprise Pays Far More Today
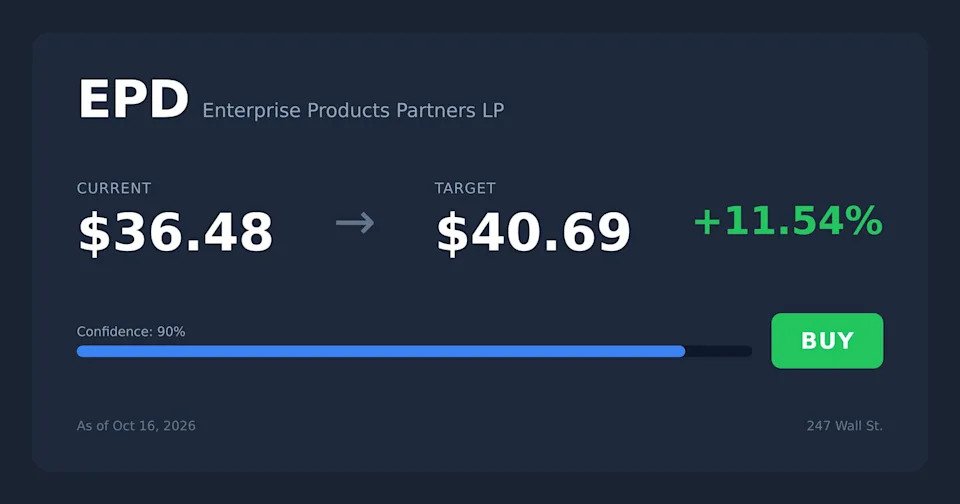
Enterprise raised its quarterly distribution to $0.56 from $0.55, which works out to $2.24 a year. At a unit price of $36.08, that is a yield of about 6.2%. The distribution is well covered. Second-quarter operational distributable cash flow hit a record $2.3B, or 1.9x the distribution. Enterprise also bought back $405M of units over the trailing 12 months.
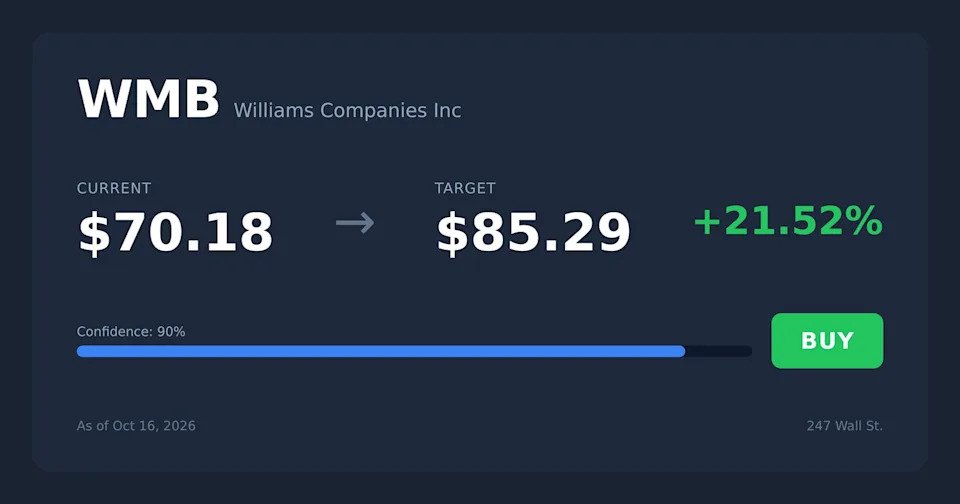
Williams pays $0.525 a quarter, up from $0.50, for $2.10 a year. At $69.94, that comes to about 3.0%. Its forecast 2026 coverage of 2.36x to 2.45x leaves a deeper cushion. Even so, a retiree who needs monthly cash gets far more income per dollar from Enterprise. Winner: Enterprise.
——
Free Report, Just Released
Why EPD Made Our Top 10 List
24/7 Wall St has helped investors make money for over two decades, and our top analysts just finished ranking the definitive Top 10 Stocks To Buy Now. Not the ten biggest companies. Not the ten everyone is arguing about. The ten best stocks to buy right now.
And EPD made the cut. See who else did.
The report is free, and you can see why we think each stock is a top investment today.
Enter Your Email and See the Ten →
——
Growth Trajectory: Williams Is Building at Twice the Scale
Williams expects $7.3B to $7.9B of growth capex in 2026, compared with $2.9B to $3.4B at Enterprise. It raised its 2026 adjusted EBITDA guidance to $8.3B to $8.5B and lifted its long-term compound annual EBITDA growth target through 2030 to “11 plus percent.” Its drivers include the $5.5B Momentum Midstream deal, 7.1 Bcf/d of pipeline projects already underway and power projects for data centers. Management also expects Gulf Coast LNG demand to rise by about 20 Bcf/d over the next decade.