- Evergy recently attracted fresh analyst coverage that highlighted its long term capital plan, data center and industrial contracts, and the execution risks around higher operating and financing costs tied to its large grid and generation build out.
- The new research attention puts Evergy’s reliance on long dated agreements with major data center and manufacturing customers under the spotlight. It raises sharper questions about how ramp timing, usage levels, and rate recovery interact with its dividend profile and sizeable investment program.
- We will now look at how Evergy’s refreshed analyst focus on data center linked load growth could influence the broader investment narrative.
Scan how Evergy’s data center load story compares with other potential grid beneficiaries by running your eye over 43 power grid technology and infrastructure stocks.
Evergy Investment Narrative Recap
To own Evergy, you have to buy into a simple idea. The utility needs its long term data center and industrial contracts to turn into real megawatt hours on the grid while a US$21.6b capital plan from 2026 to 2030 goes into the ground without blowing out bills. The near term swing factor is how quickly those large customers actually ramp usage and support the 7% to 8% retail load outlook.
On the flip side, the biggest immediate risk sits in execution and funding. Higher operations, maintenance, depreciation and interest costs can eat into the benefit of that load growth, especially with interest payments already not well covered by earnings and dividends not well covered by free cash flow. Truist’s new coverage shines a light on these pressures but does not on its own change the operational task in front of Evergy.
The most relevant datapoint alongside Truist’s fresh research is the earlier Dividend Discount Model work suggesting Evergy’s intrinsic value is below the current share price based on expected payouts. That analysis effectively stress tests whether the dividend and long term growth profile justify the capital program and equity issuance that are planned from 2026 to 2029.
For you as a shareholder or prospective investor, that creates a clear checklist: watch how Evergy balances funding US$700m to US$900m of annual equity, a US$3.5b revolver and heavy grid and generation spend against cash returns and regulatory outcomes. Progress on actual data center loads, rate case decisions and interest coverage looks more important than short term moves in analyst commentary.
Evergy Analyst Forecasts In Focus
Evergy’s narrative includes projected revenue of US$7.3b and earnings of US$1.3b by 2029. This is based on analysts assuming 6.4% yearly revenue growth and an earnings increase of about US$374m from current earnings of US$925.8m.
Uncover how Evergy’s fair value indicates a 6% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
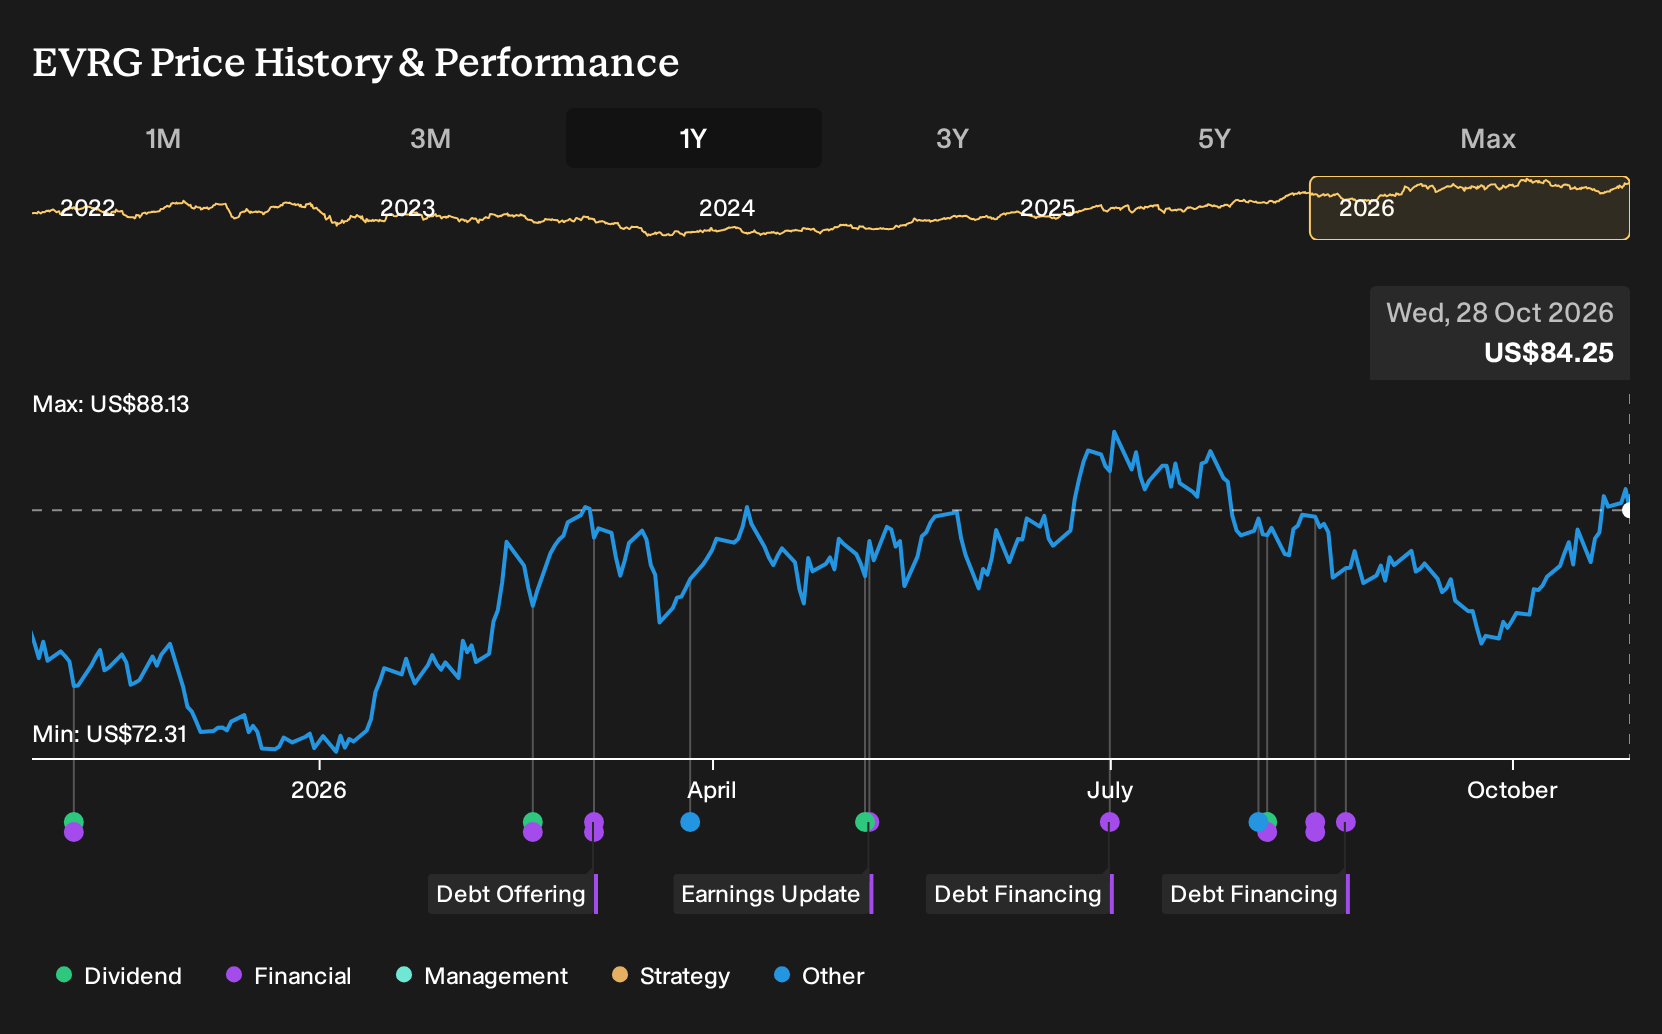
Two fair value views from the Simply Wall St Community span roughly US$61 to US$89, which already shows how far apart private investors can be on Evergy. Set that against Truist’s fresh Buy rating and US$97 target, and you get a clear message: you need to weigh data center ramp risk and heavy capex before taking a side.
Explore another Evergy fair value estimate, including one that suggests as much as 27% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Evergy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Evergy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Evergy’s overall financial health at a glance.
Looking For More Investment Ideas Beyond Evergy?
Once you have formed a view on Evergy, it can help to cross check that thesis against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- If you want potential upside with strict balance sheet discipline, scan through a list of solid balance sheet and fundamentals (24 results) that meet your quality bar.
- If resilience and fewer red flags appeal more than excitement, filter for 32 resilient stocks with low risk scores that might better fit a steadier approach.
- If you are hunting for overlooked opportunities with strong fundamentals, run your eye over 19 high quality undiscovered gems that could complement or challenge your Evergy view.
Valuation is complex, but we’re here to simplify it.
Discover if Evergy might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com