Zacks Equity Research
5 min read
Newell Brands Inc. NWL has delivered a strong stock-market performance in recent months as investors have gained confidence in its ongoing turnaround. The company’s shares have rallied 51.2% over the past six months, comfortably outperforming the S&P 500 index, which gained 13.9% during the same period and the Consumer Staples sector’s growth of 4.3%. Meanwhile, the broader Consumer Products – Staples industry fell 2%.
The recent rally reflects improving operating trends, stronger innovation, better retail execution and a return to sales growth. Newell reported year-over-year growth in both net sales and core sales in the second quarter of 2026 for the first time in more than four years. The company also raised its 2026 outlook across sales, margins, normalized earnings per share (EPS) and operating cash flow.
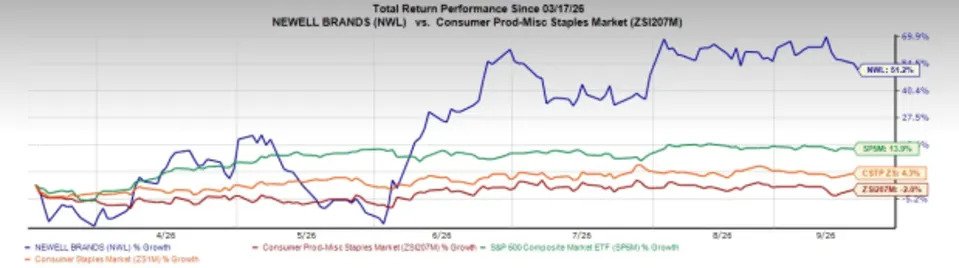
Image Source: Zacks Investment Research
NWL’s performance is notably stronger than that of its competitors, BJ’s Wholesale Club BJ, Colgate-Palmolive Company CL and Church & Dwight Co., Inc. CHD, which declined 3%, 1.6% and 1.7%, respectively, in the past six months.
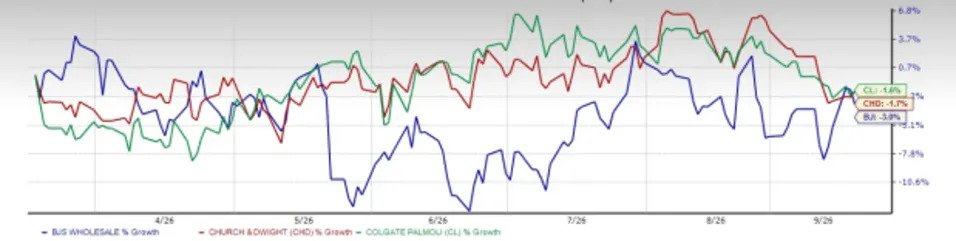
Image Source: Zacks Investment Research
Closing at $5.64, NWL stock stands almost 21% below its 52-week high of $7.13, attained on July 31, 2026. The company is trading above its 200-day simple moving average of 4.44, indicating that the stock’s recent recovery remains intact despite its pullback from the 52-week high.
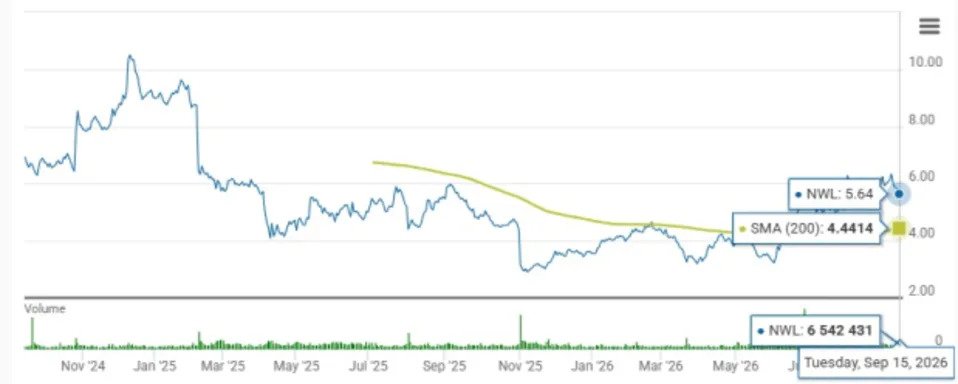
Image Source: Zacks Investment Research
What’s Fueling Newell’s Recent Stock Rally?
Newell’s second-quarter 2026 results provided a significant boost to investor sentiment. Net sales increased 3% year over year to approximately $2 billion, while core sales grew 2.3%, marking the company’s first year-over-year growth in both measures in more than four years. Normalized EPS rose to 42 cents from 24 cents a year ago and exceeded the Zacks Consensus Estimate of 19 cents.
The improvement was broad-based. Learning & Development generated 4.9% core sales growth, led by strength in Baby and a return to growth in Writing. Outdoor & Recreation delivered 3.7% core sales growth, while Home & Commercial Solutions remained under pressure but improved sequentially. Graco, Sharpie, EXPO and Coleman were among the brands benefiting from stronger innovation, distribution gains and improved retail execution.
Newell also raised its 2026 outlook. The company now expects net sales growth of 1-2%, core sales growth of 0-1%, normalized operating margin of 10-10.4% and normalized EPS of $0.73-$0.77, compared with its previous EPS outlook of $0.56-$0.60. Operating cash flow is expected to be around $400 million.
Newell’s improving fundamentals are being supported by strength in key brands such as Graco, Sharpie, Coleman and Oster, while distribution gains and increased advertising and promotional support are helping improve consumer engagement. At the same time, the company continues to face inflation, transportation costs and elevated debt levels, which could limit the pace of its recovery.