The AI chip king is closing in on a record high, riding high even as its peers struggle. But of all the tech darlings, Nvidia (NVDA) has the most modest multiple.
Despite being the heart of the AI trade and a shining example of post-COVID growth in the US, every other member of the “Magnificent Seven” has been trading at a higher premium. Per FactSet, Nvidia’s forward price-to-earnings multiple is even lower than that of the S&P 500 (^IXIC).
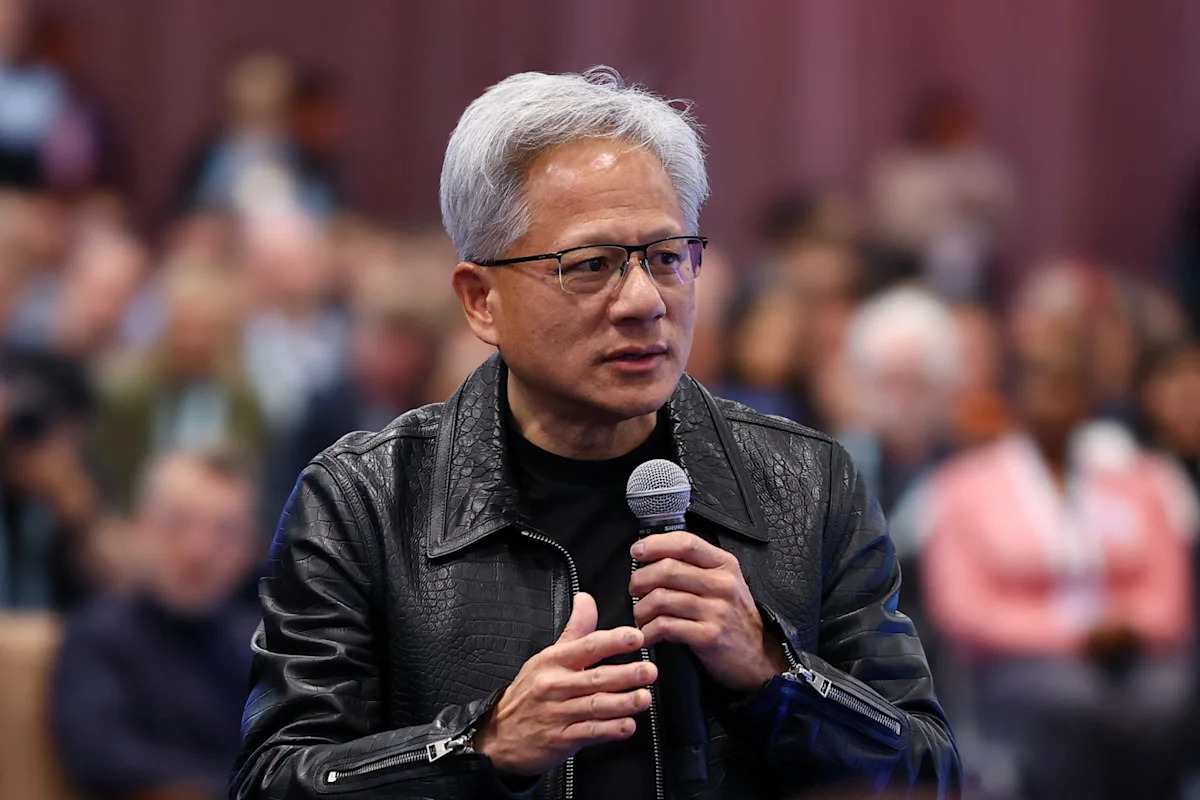
It’s almost a certainty that CEO Jensen Huang, clad in his leather jacket of bullish optimism, is not thrilled with his company’s valuation ratio, with way more work and profit required to reach that record high.
But Huang and Nvidia’s board wasted no time and took advantage of the low valuation to execute the largest buyback ever in the US, a $150 billion increase to its stock buyback program. Yet another instance of Nvidia flexing its cash.
Nvidia’s relative cheapness brings an unexpected comparison to mind: ExxonMobil (XOM). That’s the thrust of a new and surprising analysis by DataTrek co-founder Nicholas Colas, who frames the two firms as underrated tickers at the center of scarcity investment stories — data and oil.

ExxonMobil goes for 12.9x future 12-month estimates, per FactSet. Nvidia’s multiple is higher, at 18.7x, with both sitting below the benchmark index’s market multiple of 19.2x.
As Colas noted, you might expect a legacy energy company to trade at a discount. But if data is the new oil, why is the linchpin of the AI trade so cheap?
The so-called central bank of AI claims its investments in 13 public companies and more than 200 private ones have returned three times what it put in. And Nvidia said it plans to deploy those winnings through share repurchases and a growing dividend.
For Nvidia bears who believe the hype is overblown, the company’s growth trajectory offers a startling rebuttal. As Colas observed, Wall Street analysts’ revenue estimates pin the company’s fiscal year 2028 sales numbers at close to $700 billion.
That brings us back to the Exxon comparison. While the two companies in 2026 are roughly equivalent in revenue, Nvidia’s growth curve is on a different level, making the P/E comparison almost droll. Analysts expect Nvidia to be 66% larger than Exxon in terms of revenues next year.
“Exxon could merge with the second most valuable US energy company and still not be as large as Nvidia is likely to be in 12 months’ time,” Colas wrote. “That is the scale of expected growth in Nvidia’s business, driven by AI investment spending, and is almost beyond comprehension.”