President Donald Trump turned down Iran’s peace offer over the weekend. Oil went up, gold fell apart, and nearly every chipmaker had a miserable morning.
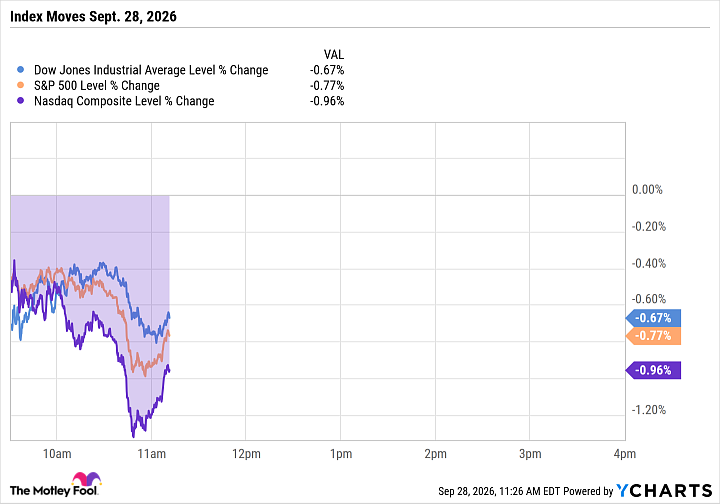
The Nasdaq Composite (^IXIC -0.71%) index dropped 1% as of 11:26 a.m. ET while the S&P 500 (^GSPC -0.59%) fell 0.8%. The Dow Jones Industrial Average (^DJI -0.48%) declined by 0.7%. Seventeen of the Dow’s 30 components traded lower in this Wall Street snapshot.
A rejected offer put crude back over $100
Iranian foreign minister Abbas Araghchi had offered to reopen the Strait of Hormuz and restart nuclear talks within seven days in exchange for lifting the naval blockade, waiving oil sanctions, and observing a ceasefire. Trump turned down Iran’s peace proposal, calling the terms “unacceptable.” He reportedly told aides that he expects strikes to resume after November’s midterms.
So Brent spiked above $108 in early trading before settling back near $100, still up roughly 2.7% in 24 hours. The United States Oil Fund (USO +1.06%) rose 3.3%. Energy was the only sector to post a real gain with a composite 0.9% uptick, though the major oil and energy companies generally moved less than the barrel price. Among the 13 largest energy stocks (measured by market cap), each one rose or fell less than 2%.

Image source: Nvidia.
Nvidia (NVDA +2.51%) is marching to a different beat, up 2.1% and pretty much alone in the green. It’s the largest mover in the Nasdaq and S&P 500 indexes today after announcing a $150 billion expansion of its buyback program. The remaining authorization is $235 billion, the largest share repurchase authorization ever presented by an American company.
Nvidia also rolled out OpenShell, an agent-safety platform it claims could have stopped the OpenAI agents that broke into Hugging Face last month.
Every other major chip name fell. I mean, it’s a broad downturn in the semiconductor sector today, despite Nvidia’s gains. SK Hynix (SKHY -4.78%) dropped 5.9%, Advanced Micro Devices (AMD -3.96%) 5.2%, Qualcomm (QCOM -6.30%) 5.7%, and Micron Technology (MU -2.65%) 3.7%. Their investors are concerned about Iran-driven increases in the Federal rate in the coming weeks, and OpenAI will pause its back-end training until further notice. That’s a different way to address AI agent security threats.
Rising yields did the rest of the damage. The 10-year Treasury rose to 5.26%, pushing gold prices nearly 4% lower as investors sought high-yielding safe havens. 10-year bonds just hit their highest level since the spring of 2002.
Index
NASDAQ Composite Index
Today’s Change
Index Level
26,876.60
Buckle up for a heavy data week
This will be a dense data week. Job openings arrive tomorrow. Core consumer-side inflation and final second-quarter GDP reports are due on Wednesday. September’s job report is scheduled for Friday. Forecasters expect 84,000 new jobs, way down from August’s 162,000, with unemployment steady at 4.1%. Any of those could move rate expectations in a market already braced for another Federal rate hike.
Micron squeezes in a much-watched earnings report on Wednesday evening, covering the fourth quarter and full fiscal year of 2026. The offbeat timing feels awkward since memory stocks just took the worst of Monday’s selling.
And before I forget, the U.S. and China agreed to cut tariffs on $60 billion of goods. The tariff cuts run to Jan. 10, 2027, split evenly between the parties. I see American corn and meat on one side and Chinese gadgets on the other.
Chinese stocks fell anyway amid a bipartisan U.S. push to ban Chinese components from government data centers.