Micron Technology (MU +0.16%) is poised to release its fiscal 2026 fourth-quarter results on Sept. 30, and Wall Street will look to the company’s numbers and guidance to gauge whether the memory market’s red-hot growth is sustainable.
The good news for Micron stock investors is that there is enough evidence suggesting that the memory market’s impressive growth isn’t going anywhere. Let’s see why the company could crush expectations once again.

Image source: Getty Images.
Why Micron’s results could lift the stock market
The healthy demand for high-bandwidth memory (HBM), which consumes thrice the wafer capacity of conventional dynamic random-access memory (DRAM), should ensure that tight supply conditions in the memory market continue. Citi predicts that HBM bit demand could increase by 62% in 2027, followed by a bigger jump of 69% in 2028.

Today’s Change
Current Price
The overall DRAM market, meanwhile, is anticipated to witness a 30% jump in demand in 2027 and a 35% spike in 2028. However, DRAM supply growth will be significantly lower. Citi estimates that DRAM supply will increase by 19% next year 22% in 2028.
So, the tight supply and strong demand conditions supporting Micron’s growth are here to stay. These factors should enable the memory specialist to deliver stronger-than-expected earnings and guidance, which could send the stock soaring. After all, Micron continues to trade at just 25 times earnings despite its exponential growth.
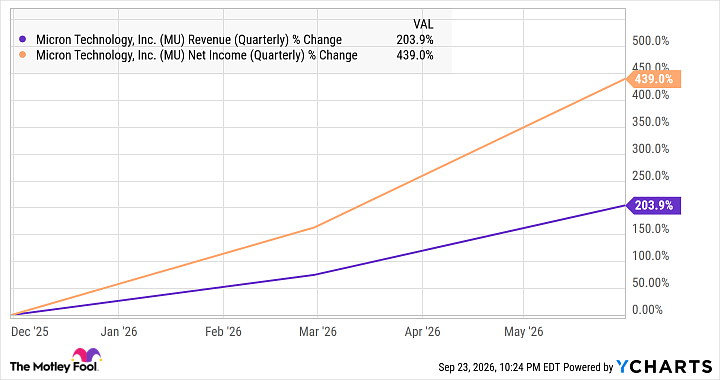
MU Revenue (Quarterly) data by YCharts
Analysts are expecting the company’s revenue to increase by 90% in fiscal 2027 (which has just begun) to $247.5 billion. What’s more, the company’s earnings per share are estimated to increase by 116% to $158.93. What’s worth noting is that analysts have raised their expectations for Micron this year, which isn’t surprising given the points discussed above.
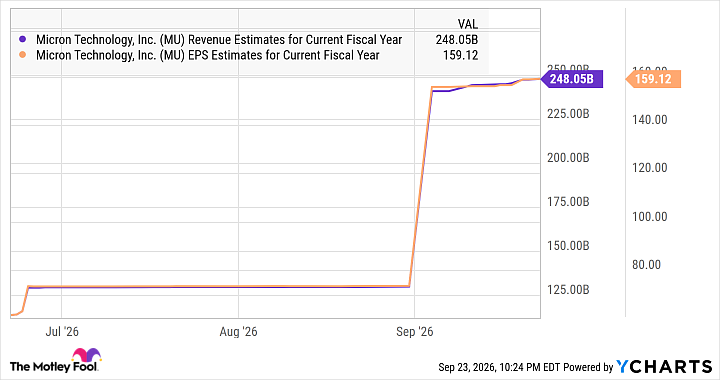
MU Revenue Estimates for Current Fiscal Year data by YCharts
Also, strong results and guidance from the company could give the stock market a nice boost. That’s because Micron has been one of the hottest tech stocks on the market over the past year. Its shares have risen by 551% over this period. That’s well above the 18% jump in the Nasdaq Composite and the 15% spike in the S&P 500, two indexes that the company is a part of.
So, don’t be surprised to see Micron’s results triggering an impressive stock market rally in the final quarter of 2026. Micron stock could jump significantly following its Sept. 30 earnings report, making it a buy right now given its cheap valuation. However, there is one more stock that could get a nice shot in the arm following Micron’s results that is worth buying right now.
Healthy memory capex will be a tailwind for Lam Research
The ongoing shortage of memory chips explains why memory manufacturers are poised to spend more on capital equipment. The capital expenditure of memory makers is poised to jump from $58 billion last year to $146 billion in 2027, according to Deloitte. Importantly, these solid investments can continue beyond next year, as the memory shortage is anticipated to persist at least until 2030.
This is great news for Lam Research (LRCX +2.62%), which supplies memory manufacturing equipment to Micron and others.

Today’s Change
Current Price
Lam sells semiconductor manufacturing equipment and derives a significant share of its revenue from the memory industry. Specifically, 46% of Lam’s revenue came from sales of memory equipment in the fourth quarter of fiscal 2026. This is one of the primary reasons why Lam’s growth rate is picking up.
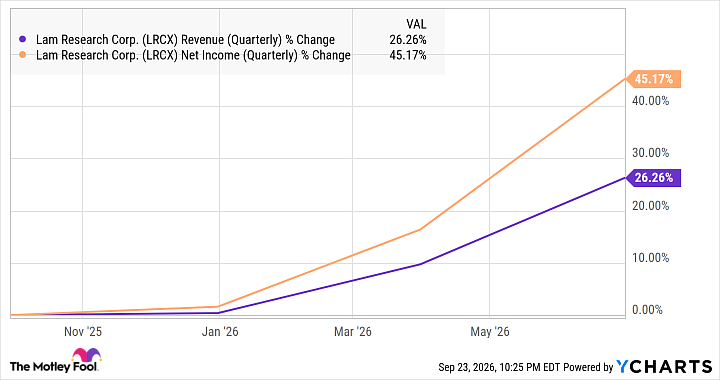
LRCX Revenue (Quarterly) data by YCharts
The company posted a 26% increase in revenue in fiscal 2026 to $23.2 billion. Its net income per share increased almost 39% last year to $5.76. Lam’s earnings per share could jump by 63% in the current fiscal year, according to analysts’ estimates. The stronger earnings growth could result in more upside for this semiconductor stock, considering that it trades at 32 times forward earnings, a discount to the Nasdaq Composite’s average earnings multiple of 39.
Also, Lam can sustain its healthy earnings growth beyond the current fiscal year amid a favorable memory capex environment. Analysts expect the company’s earnings per share to grow at a 26% annual rate over the long run, according to YCharts. Assuming Lam can sustain this rate for three years beyond fiscal 2027 (which ends in June 2027), its earnings per share could reach $19.02 in 2030 (using fiscal 2027’s projected earnings per share of $9.51 as the base).
If this AI stock trades at 39 times earnings at that time, in line with the Nasdaq Composite’s earnings multiple, its stock price could reach $742. That implies a potential upside of 142% over the next four years. So, investors looking to capitalize on the secular growth of the memory market can consider buying Lam stock ahead of Micron’s earnings report, as its key role in the memory industry could spark a rally in its shares.