Procter & Gamble (PG) is up about 3% so far this year, putting it behind the S&P 500. However, on Oct. 6, 2026, Evercore ISI upgraded Procter & Gamble from In Line to Outperform and raised its price target to $166 from $161.
The new target points to about a 14% increase from the stock’s close on Oct. 5. After investors heard news of the upgrade, PG shares rose between 1.5% and 2% in afternoon trading.
This is the first time Evercore has given P&G a clear bullish rating since the firm became cautious about the stock back in mid-2025. Evercore turned cautious because it noticed P&G underperforming across the Amazon channel.
P&G’s Amazon market share was only about a third of what it held at Walmart and Costco, even as Amazon drove roughly half of U.S. HPC growth.
Investors are now wondering why Evercore has changed its mind about the stock.
The Procter & Gamble cost problem Evercore flagged
Before the upgrade, one of the biggest reasons Evercore stayed on the sidelines was that P&G was being squeezed on costs.
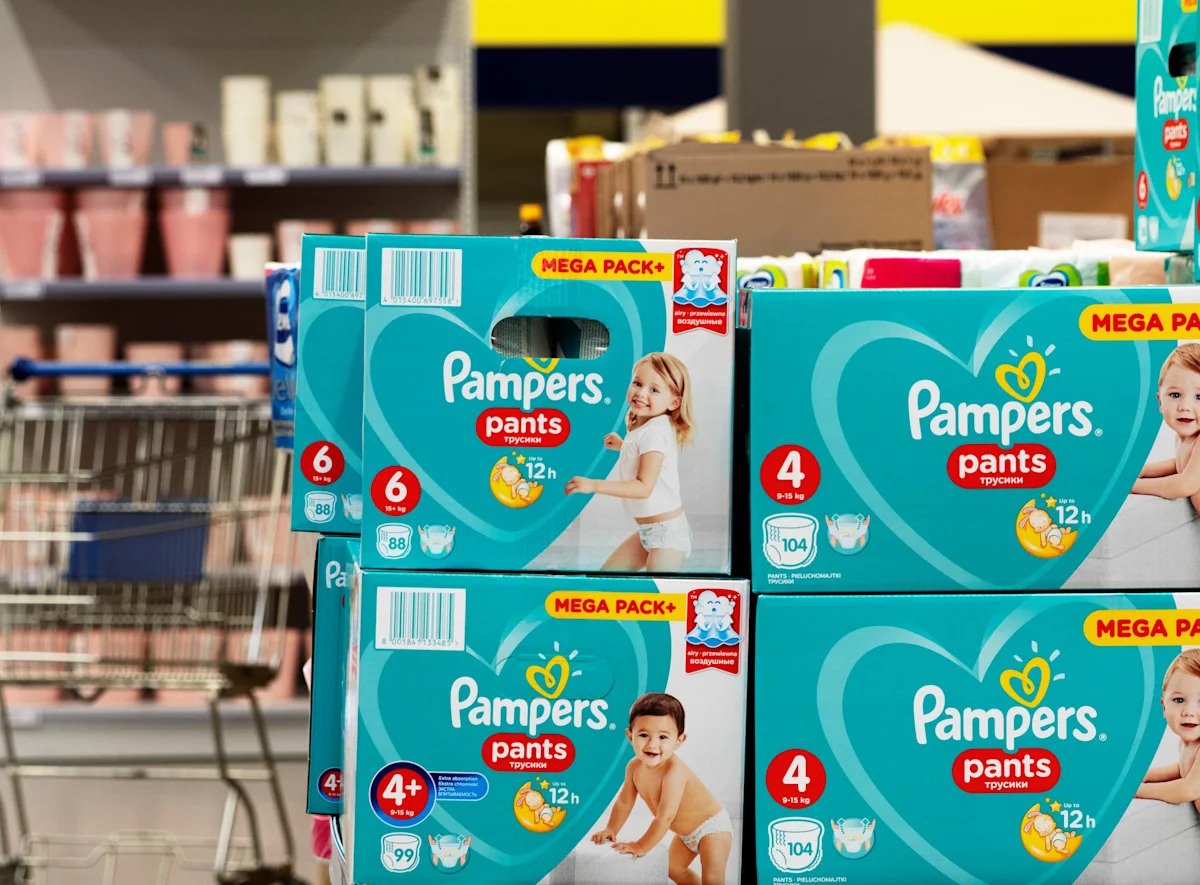
Oil prices had been climbing, which pushed up the price of plastic packaging that P&G uses — for example, Tide bottles, Pantene shampoo containers, and Pampers packaging, according to a Reuters report on U.S. News.
Shipping and freight rates were also moving higher, which meant it was becoming more expensive for the company to move finished products from its factories to retailers like Walmart, Costco, and Target.
On top of that, tariff-related expenses added another layer to the input cost base. All of these costs emerged at the same time, and P&G had not fully baked them into the guidance it gave investors earlier in the year.
Also read: TJMaxx, Marshalls appear to have a customer problem
The reason this mattered so much to analysts is that P&G sells products at relatively fixed shelf prices, and retailers tend to push back when suppliers try to raise prices too quickly. So when raw materials and shipping get more expensive, the company either absorbs the hit on its margins or risks losing shelf space to cheaper rivals if it passes the cost on.
Evercore’s earlier concern was that this cost pressure, combined with the Amazon channel issue, could cap sales growth below the 4% level the firm sees as the threshold for operating leverage.
That is the backdrop against which the latest upgrade must now be understood.
Why Evercore became bullish on P&G after 15 months on the sidelines
Robert Ottenstein is the analyst behind the call. He has covered consumer staples at Evercore ISI for more than a decade, and his past calls on names including Coca-Cola and Diageo have made him well known to investors in the sector.