Inflation came in cooler than expected on Wednesday morning, which is exactly the news this market has been awaiting for weeks. Then six stocks drove the entire rally, leaving the rest of the market standing still.
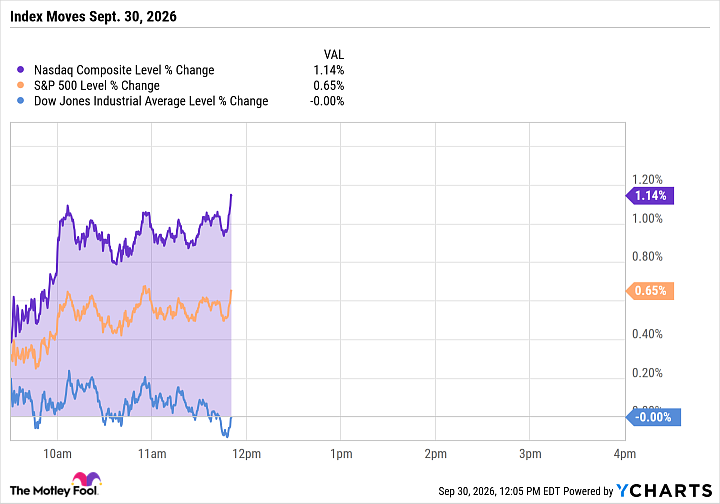
The Nasdaq Composite (^IXIC +1.02%) climbed 1.1% as of 12:05 p.m. ET and the S&P 500 (^GSPC +0.53%) added 0.6%. The Dow Jones Industrial Average (^DJI -0.08%) sat exactly flat. The Dow’s 30 components split 15 up and 15 down, continuing the balanced-flatness theme.
Mild inflation pushed the next rate hike to December
Core PCE, the inflation gauge the Fed actually watches, rose just 0.2% in August for an annual rate of 3%. Economists expected 0.3% and 3.3%, respectively. The headline PCE figure came in at 3.4%, below the 3.7% forecast. As a result, Treasury yields dropped, and traders quietly moved their next expected rate hike from October to December.
Context matters here. The Bureau of Economic Analysis changed how it measures prices for legal services, software, and computer accessories, revisions that lowered July core PCE by 0.36 percentage points. The data also predates September’s surge in diesel prices.

Image source: Getty Images.
The tech sector didn’t care about caveats, though. Alphabet (GOOG +3.23%) (GOOGL +3.24%) jumped about 3.1% after signing a White House AI accord that includes audit commitments, and its two share classes together contributed 0.49 percentage points to the Nasdaq Composite. Apple (AAPL +2.10%) rose 2.4%, erasing Tuesday’s drop. The iPhone maker rose on reports of an Oct. 13 event with a new smart home hub.
Add Nvidia at 1.6%, Microsoft with a 1.9% gain, and Amazon’s 2% rise, and six stocks account for 1.11 percentage points of the Nasdaq’s 1.14% gain. Essentially, everything else was a rounding error.
The Dow tells the other half of that story. Heavyweights Caterpillar and Goldman Sachs fell roughly 1% each, and those two canceled out everything Alphabet, Microsoft, and Apple put in. Price-weighted indexes can behave quite differently from the cap-weighted Nasdaq and S&P 500 lists.
Zooming way out, the average stock went nowhere. Equal-weight S&P 500 funds slipped slightly while the cap-weighted versions rose 0.6%.
Index
Dow Jones Industrial Average
Today’s Change
Index Level
51,307.83
Friday’s jobs report still has the last word
New York Fed President John Williams set the tone Tuesday, saying there is no need for urgency after September’s hike while allowing that another increase may be appropriate late this year. Wednesday’s data reinforced that read, effectively moving the next expected move from October to December.
The inflation fight isn’t exactly over, despite a respite from soaring figures in August. PCE is still running hot, however you slice it. Some market analysts expect a sharply higher inflation reading in September, chiefly due to higher gas and diesel prices. Gasoline alone rose 4.4% in August, and both inflation readings are still way above the Fed’s 2% long-term target rate.
Second-quarter growth got revised up to 2.2% from 1.5%. That sounds good until you notice income rose 0.2% last month while spending rose 0.9%. So the economy is hot, but not in a way that helps anyone.
Micron Technology (MU +0.72%) reports fiscal fourth-quarter results after tonight’s close. Whatever the memory-chip giant says will surely move the market tomorrow. Friday brings September’s jobs report. Five trillion-dollar companies can carry an index for a day, not a quarter. Stay tuned.
Anders Bylund has positions in Alphabet, Amazon, Invesco S&P 500 Equal Weight ETF, Micron Technology, Nvidia, and Vanguard S&P 500 ETF. The Motley Fool has positions in and recommends Alphabet, Amazon, Apple, Caterpillar, Goldman Sachs Group, Micron Technology, Microsoft, Nvidia, and Vanguard S&P 500 ETF. The Motley Fool has a disclosure policy.