Sunstone Hotel Investors (SHO) just paired a sharp jump in quarterly net income with higher full year earnings guidance, giving investors fresh numbers to reassess how the lodging REIT’s current share price lines up with its fundamentals.
Recent traders have already reacted to the stronger earnings picture, with the share price up 8.1% over the past month and a 40.1% year to date share price return. The 1 year total shareholder return of 39.7% points to momentum that has been building rather than fading.
Scan beyond Sunstone Hotel Investors to see how other lodging and real estate plays are shaping up in our hand picked 34 high quality undervalued stocks list, which features companies with solid fundamentals and potential for rerating.
Sunstone Hotel Investors now trades with a very different earnings profile than it had a year ago, yet the recent rally has already reset expectations. How much of the repricing is in the rear view, and how much might still be on the table?
Most Popular Narrative: 9% Undervalued
Against a last close of $12.79, the most popular narrative on Simply Wall St anchors Sunstone Hotel Investors to a fair value of $14.00, using an 8.33% discount rate and leaning on the most optimistic analyst forecasts. That bullish analyst Narrative on Simply Wall St builds its case around how capital recycling, RevPAR trends and margin assumptions could support that higher figure.
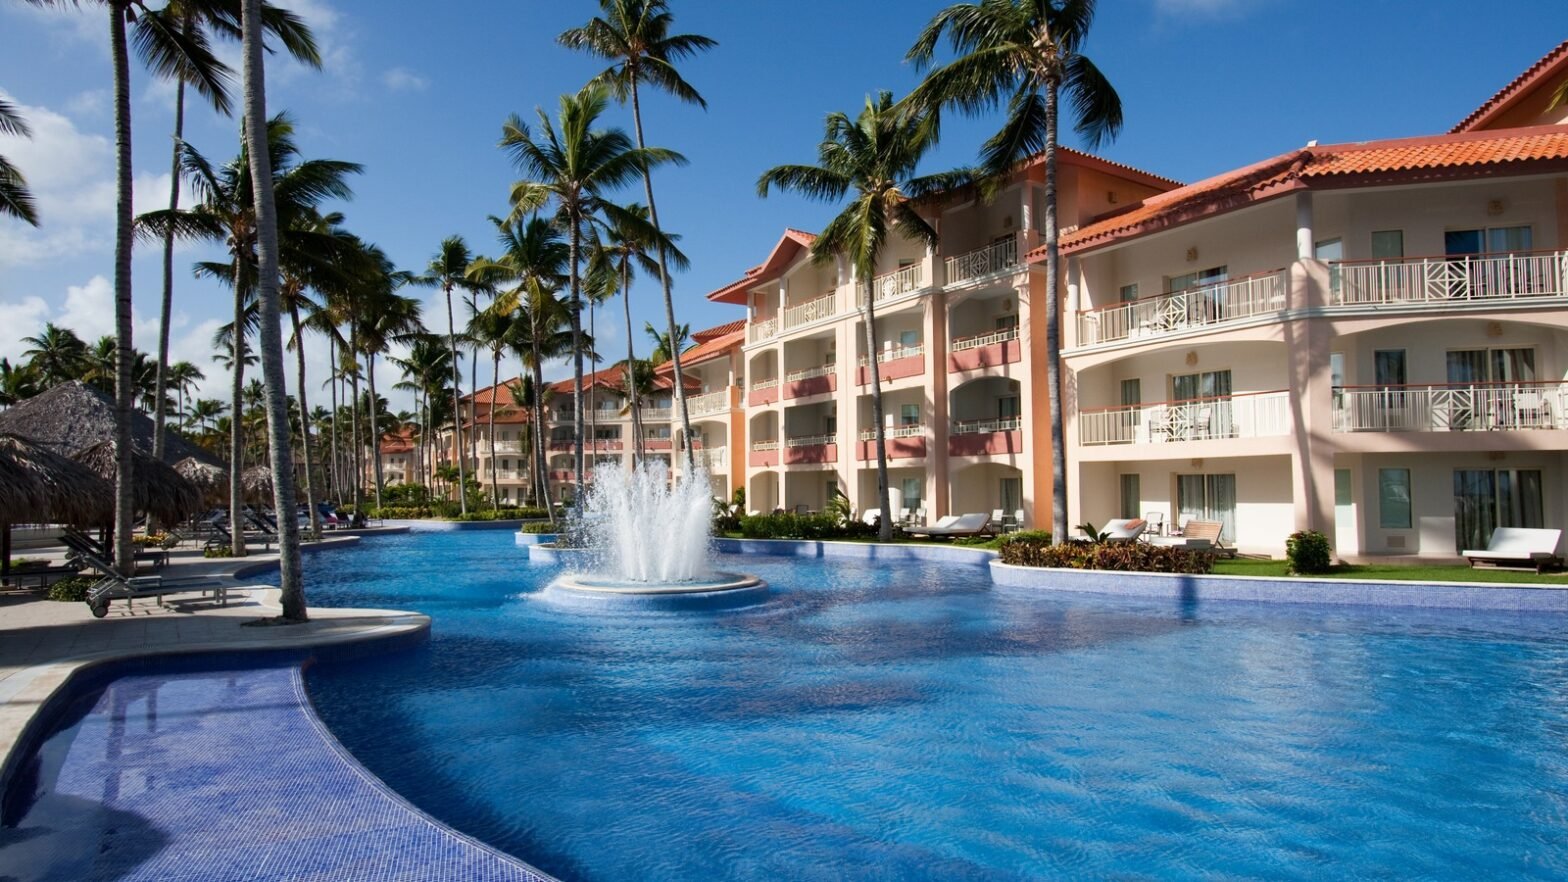
The multi year ramp of Sunstone Hotel Investors resort and luxury portfolio, led by Andaz Miami Beach, Wailea Beach Resort and the Wine Country resorts, where RevPAR and EBITDA are already rising with room for further rate and mix gains relative to peers, can add incremental revenue growth and widen EBITDA margins as these assets mature.
Disciplined expense control, with management targeting total expense growth of 3.5% to 4% for 2026 and indicating potential moderation toward or below the low end of that range in 2027, creates room for incremental RevPAR gains at properties such as Wailea Beach Resort and the Wine Country resorts to fall through at a higher rate to EBITDA and FFO.
See why 0 investors see Sunstone Hotel Investors as 9% undervalued.
Result: Fair Value of $14.00 (UNDERVALUED)
Still, a softer convention calendar at properties like Hilton San Diego Bayfront, along with ongoing renovation disruption, could cap RevPAR progress and pressure Sunstone Hotel Investors margins.
Find out about the key risks to this Sunstone Hotel Investors narrative.
Next Steps
If the combination of stronger earnings and ongoing risks around Sunstone Hotel Investors appears finely balanced, consider reviewing the data while it is current and test the story yourself by weighing up the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Sunstone Hotel Investors?
Do not stop at a single REIT when you can scan fresh opportunities side by side and pressure test your thesis against other high quality businesses.
- Target potentially resilient cash generators by reviewing a curated 6 dividend fortresses that combine income with balance sheet support.
- Hunt for mispriced quality by working through the 19 high quality undiscovered gems that pair solid fundamentals with lighter market attention.
- Dial back portfolio volatility by focusing on the 29 resilient stocks with low risk scores that score well on financial strength and risk metrics.
New: Manage All Your Stock Portfolios in One Place
We’ve created the ultimate portfolio companion for stock investors, and it’s free.
• Connect an unlimited number of Portfolios and see your total in one currency
• Be alerted to new Warning Signs or Risks via email or mobile
• Track the Fair Value of your stocks
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com